
The 30-day wash sale rule is a crucial IRS regulation that every investor needs to understand. It’s designed to stop you from selling a security at a loss to get a tax break, only to turn around and buy it right back. If you trigger this rule, that tax loss you were counting on gets disallowed for the year.
What Is the 30 Day Wash Sale Rule?
At its heart, the 30-day wash sale rule is the IRS’s way of ensuring that the investment losses you claim are legitimate economic losses, not just clever paper shuffling for a tax deduction.
Think about it this way: imagine you sell a stock for a $500 loss on Monday just to lock in that tax deduction. But you still believe in the company, so you buy the same stock back on Tuesday. From an economic standpoint, nothing has really changed—you still own the stock. But you've tried to create a tax loss out of thin air.
To close this loophole, the IRS created a specific time frame around the sale. This rule is a long-standing piece of U.S. tax law, first put on the books way back in 1921 when Congress got tired of seeing investors game the system. You can explore more about the history of the wash sale rule and see how its core principles have stood the test of time for over a century.
The Critical 61-Day Window
Here’s where most people get tripped up: the "30-day" name is a bit of a misnomer. The rule actually casts a much wider net, covering a full 61-day period.
This window is centered on the day you sell a security for a loss and includes:
- The 30 days before the sale.
- The day of the sale itself.
- The 30 days after the sale.
If you buy a substantially identical security at any point within this 61-day timeframe, the wash sale rule kicks in, and your loss is disallowed. It’s that simple, and it’s why understanding this full window is non-negotiable for anyone serious about tax-loss harvesting.
The key takeaway is that the rule looks both backward and forward from the date of your sale. A purchase made two weeks before you sell at a loss can trigger the rule just as easily as a purchase made two weeks after.
To help visualize this, here’s a breakdown of the three distinct periods that make up the wash sale window.
The 61-Day Wash Sale Window Explained
| Time Period | Description | Investor Action to Avoid |
|---|---|---|
| Before the Sale (Day -30 to -1) | The 30 days leading up to your sale at a loss. | Buying the same or a substantially identical security. |
| Day of Sale (Day 0) | The date you execute the trade that results in a capital loss. | Re-buying the security on the same day you sold it. |
| After the Sale (Day +1 to +30) | The 30 days immediately following your sale at a loss. | Buying the same or a substantially identical security. |
This table makes it clear that your trading activity, both before and after you lock in a loss, matters to the IRS.
This timeline diagram offers another great visual of the full 61-day period, showing how it stretches out on both sides of the sale date.
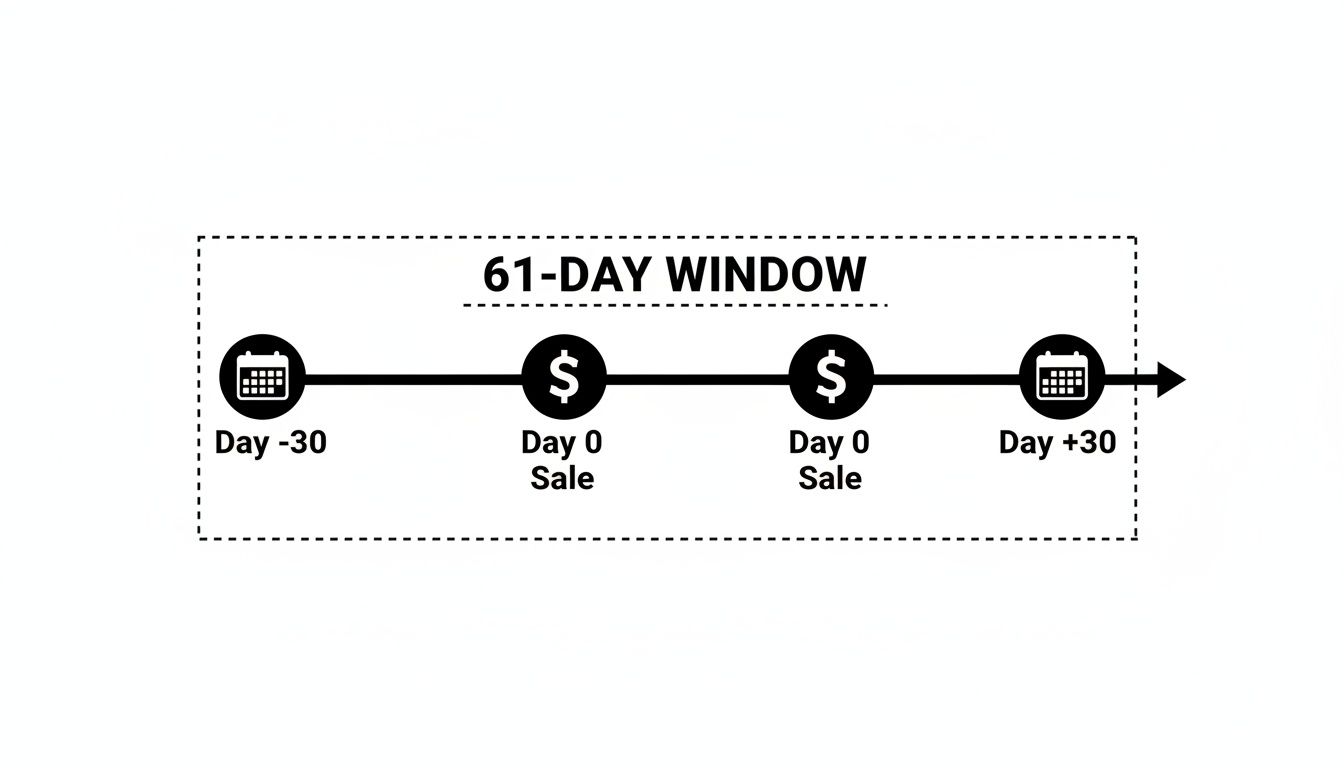
As you can see, any repurchase activity from Day -30 to Day +30 can wipe out the tax deduction you were hoping to claim. This single concept is the foundation of all wash sale compliance, and getting it right is the first step to smart, tax-efficient investing.
How the Wash Sale Rule Actually Works
The moment an investor triggers the 30-day wash sale rule, there’s often a wave of panic. The common misconception is that the capital loss just vanished into thin air, a permanent casualty of an obscure IRS regulation.
Fortunately, that’s not how it works at all. The loss isn’t gone forever—it’s just deferred.
Think of it like getting a rain check at a store. The IRS says you can't use your coupon (the tax deduction for your loss) right now, but they let you staple its value onto your new purchase. This happens through a simple but critical accounting tweak to your cost basis.
The disallowed loss from your sale gets rolled into the cost basis of the new, replacement shares you bought. This adjustment bumps up the official purchase price of your new position, which in turn will either lower your taxable gain or increase your loss when you eventually sell those shares for good.
A Step-by-Step Example of a Wash Sale
Let's walk through a classic scenario to see this in action. Say you bought 100 shares of a hypothetical tech company, "Innovate Corp" (ticker: INVT), a few months back.
- Initial Purchase: You bought 100 shares of INVT at $50 per share, for a total investment of $5,000.
- The Sale: The stock takes a hit. On June 10th, you sell all 100 shares at $40 per share, getting $4,000 back. This locks in a $1,000 capital loss ($5,000 cost – $4,000 proceeds).
- The Repurchase: By June 25th, you're having second thoughts and still believe in the company's future. You jump back in, buying 100 shares of INVT at $42 per share for a total of $4,200.
Because you repurchased the same stock within 30 days of selling it at a loss, you've triggered a wash sale. That $1,000 loss you were hoping to deduct is disallowed for this tax year.
So, what happens to that $1,000? It's not lost. Instead, it gets added directly to the cost basis of your newly purchased shares. This is the core mechanic of the wash sale rule.
Here’s how you calculate your new adjusted cost basis:
New Purchase Price ($4,200) + Disallowed Loss ($1,000) = Adjusted Cost Basis ($5,200)
This means your 100 new shares now have an official cost basis of $52 per share ($5,200 / 100 shares), even though you only paid $42 out of pocket. When you finally sell these shares down the road, your profit or loss will be calculated from this higher $52 price point, effectively letting you recognize that original $1,000 loss at that time.
Demystifying "Substantially Identical" Securities
This is where the rule gets a bit tricky. It doesn’t just apply to buying the exact same stock. It also kicks in if you purchase substantially identical securities. Unfortunately, the IRS is famously vague here, offering no bright-line test. It often comes down to the specific facts and circumstances.
Still, there are some well-established guidelines from years of practice:
- Different Companies: Stock in one company (like Ford) is never considered substantially identical to stock in another (like General Motors), even if they're direct competitors in the same industry.
- Bonds: Bonds from the same issuer are generally seen as substantially identical if they have similar maturity dates and interest rates. A bond from a different company or one that matures 20 years later would almost certainly be safe.
- Options: Buying a call option on a stock you just sold is a definite no-go. The IRS considers it substantially identical to buying the stock itself, as it's a contract to acquire that security.
Consider this classic example of the rule's reach. Let’s say you sell 100 shares of XYZ stock for a $5,000 loss on December 15th. But then, on December 20th, your spouse buys 100 identical shares in their IRA. That loss is now disallowed. That $5,000 gets tacked onto the cost basis of the shares in the IRA, deferring your tax benefit until those shares are sold. This 61-day window covers stocks, options, and other contracts. You can learn more about the specifics on the wash sale rule entry on Wikipedia.
Understanding this direct link between a disallowed loss and your adjusted cost basis is the single most important concept for managing your investments around this rule.
Getting Into the Weeds: Complex Wash Sale Scenarios
The basic idea of the 30-day wash sale rule seems simple enough: you can't sell a stock at a loss and immediately buy it back just to claim a tax deduction. But once you move beyond that simple definition, things can get messy, fast. The rule has a much wider reach than most investors realize, and understanding its nuances is key to avoiding some nasty tax surprises.
Let's dive into a few of the more complex situations that trip people up.
Partial Wash Sales: It's Not All or Nothing
One common misunderstanding is that the wash sale rule is an all-or-nothing affair. That’s not how it works. The rule is applied on a share-for-share basis, leading to what’s known as a partial wash sale.
Imagine you sell 100 shares of XYZ Corp and realize a $1,000 loss. Feeling a bit of seller's remorse a week later, you decide to get back in, but only with 50 shares.
So, what happens?
- The IRS matches the 50 new shares to 50 of the shares you just sold.
- The loss on those 50 shares ($500, or half your total loss) is disallowed for now.
- That $500 disallowed loss gets added to the cost basis of your new 50-share position.
- The good news? The other half of your loss—the $500 from the 50 shares you didn't replace—is still a valid, deductible loss for the current tax year.
The core principle here is matching. The rule only punishes you for the shares you actually replace within that 61-day window.
The IRA Trap: Turning a Temporary Loss into a Permanent One
Triggering a wash sale in your regular brokerage account is annoying, but it's usually just a timing issue. Triggering one between your taxable account and an IRA, however, is a financial disaster. This is hands-down the most dangerous wash sale pitfall.
Here’s the trap: you sell a stock at a loss in your taxable account. Within 30 days, you buy that same stock back inside your Roth or Traditional IRA. The wash sale is triggered, and your loss is disallowed. But here's the crucial—and painful—difference: you can't adjust the cost basis of assets inside an IRA. The tax-deferred (or tax-free) nature of these accounts makes the concept of cost basis irrelevant for tax calculations.
This means the disallowed loss from your taxable sale vanishes into thin air. It can’t be added to the IRA shares' basis, so you can never use it to offset future gains. The loss is gone. Forever.
The IRS Sees All: The Rule Crosses Account Boundaries
A lot of investors think they can sidestep the rule by spreading their trades around. They'll sell a stock for a loss in their E*TRADE account and buy it back in their Schwab account, thinking they're in the clear. Unfortunately, the IRS doesn't see it that way.
The wash sale rule applies to you, the taxpayer, not to your individual accounts. The IRS aggregates all your trading activity. It even extends to your spouse. If you sell a stock for a loss and your spouse buys it back within the 61-day window—even in their own separate account—your loss is still disallowed. For tax purposes, the IRS often treats a married couple as a single financial unit.
"Substantially Identical" Is Broader Than You Think
The rule gets even murkier when you move beyond simple common stock. The IRS disallows losses when you replace a security with something "substantially identical," a term that can be surprisingly broad.
- Options: This is a classic trigger. Selling a stock at a loss and then buying a call option on that same stock is a definite wash sale. The option gives you the right to buy the underlying stock, making it a direct substitute in the eyes of the IRS.
- Share Classes: What about different classes of stock in the same company, like Class A vs. Class B shares? This is a gray area. If the classes have different voting rights or dividend structures, they're generally not considered identical. But if one class is convertible into the other, the IRS could argue they are substantially the same.
For now, the world of crypto has been a bit of a wild west. These complicated rules haven't applied to Bitcoin, Ethereum, or other digital assets, but that could always change with new legislation. To get a handle on the current landscape, you can learn more by exploring our detailed guide on crypto tax loss harvesting. The main takeaway is to always assume the wash sale rule has a wider reach than you might first expect.
Reporting Wash Sales on Your Tax Return
Knowing the theory behind the 30-day wash sale rule is one thing, but the real test is getting it right on your tax return. It can feel a bit daunting at first, but once you know the process, it’s really just a matter of connecting the dots.
The starting point is a document you'll get from your brokerage firm: Form 1099-B, "Proceeds from Broker and Barter Exchange Transactions." This is your year-end summary of all trading activity. The good news? Modern brokers are required to track wash sales for you and report them directly on this form.
When you get your 1099-B, look for any trades that have been flagged as a wash sale. You should see a column for adjustments and a specific code—usually "Code W"—next to the transaction, indicating that a wash sale loss was disallowed.
From Your Brokerage Statement to Form 8949
Once you spot a wash sale on your 1099-B, the next step is to carry that information over to IRS Form 8949, "Sales and Other Dispositions of Capital Assets." Think of this form as the detailed log of every single sale you made. The totals from here will eventually flow to your Schedule D.
Here’s how you handle a wash sale entry on Form 8949, step-by-step:
- Report the Sale: First, report the original sale just like any other trade. You'll list the stock's name, the date you bought it, the date you sold it, the proceeds you received, and your original cost basis.
- Enter the Adjustment Code: In column (f) of Form 8949, enter the code "W". This is the signal to the IRS that this transaction is a wash sale.
- Record the Disallowed Loss: In column (g), enter the amount of the disallowed loss. This number should match what your 1099-B shows as the wash sale adjustment. This is the key step that makes it all official for tax purposes.
By adding the disallowed loss as a positive number in the adjustment column, you effectively cancel out the loss for this specific transaction on paper. This ensures your total capital gains and losses are calculated correctly according to tax law, deferring the benefit of that loss to a future sale.
Finalizing the Numbers
The adjustment you make on Form 8949 has a direct impact on your final tax bill. It works by increasing the cost basis of the replacement shares, which means when you finally sell them for good, you’ll either have a smaller gain or a larger loss. Getting this deferral right is crucial for accurate tax filing. If you want to dive deeper into the mechanics of these calculations, check out our guide on how to calculate capital gains.
While you're at it, it's also smart to understand broader concepts like the available day trading tax deductions and how different trader classifications can affect your overall tax picture. Even though your broker does most of the heavy lifting on tracking, the ultimate responsibility for correct reporting lands squarely on your shoulders. Taking the time to understand these forms transforms a confusing chore into a manageable part of your investment strategy.
Common Wash Sale Mistakes and How to Avoid Them
Even the most experienced investors get tripped up by the 30-day wash sale rule. It’s one of those tricky regulations where the devil is truly in the details, and a seemingly smart tax-loss harvesting move can quickly backfire into a costly mistake.
And these aren't just edge cases. Think about it: for a trader who realizes just 20 losses in a year, the odds of accidentally repurchasing one of those stocks within the 61-day window can be higher than 50%. Recent IRS data backs this up, showing a staggering $15.2 billion in wash sale deferrals reported on 1099-Bs. What's surprising is that 65% of these came from individual accounts under $1 million—the exact demographic that includes many real estate investors, crypto holders, and entrepreneurs.
So, let's walk through the most common blunders I see and, more importantly, how to stay clear of them.
Forgetting the 30-Day Look-Back Period
The name itself is a bit of a head-fake. Most people fixate on the 30 days after they sell for a loss, but they completely forget the IRS is looking in the rearview mirror, too. Buying a stock within 30 days before you sell it for a loss will also trigger the rule.
Here's how it plays out:
You buy 50 shares of Company A on May 15th. Then, on June 5th, you decide to sell your original 100 shares of Company A (which you bought months ago) to lock in a tax loss. Well, because you bought more shares just 21 days before that sale, the loss on 50 of those sold shares is now disallowed.
The Fix: Always check your transaction history for the 30 days before you sell any position at a loss. It's a simple step that can save you a major headache.
The Dividend Reinvestment Plan (DRIP) Trap
Automatic dividend reinvestment plans are fantastic for building wealth on autopilot, but they can create a real mess when you're harvesting losses. A DRIP will quietly use your dividend payouts to buy more shares of the stock, and you might not even realize it happened.
If you sell a stock for a loss, but a tiny DRIP purchase hits your account within that 61-day window, boom—you've triggered a wash sale. Even a fractional share is enough to disallow a portion of your loss.
The Fix:
Simply turn off the DRIPs for any stocks you plan to sell at a loss. You can always turn them back on after the 31-day post-sale period has safely passed.
Overlooking Spousal and IRA Transactions
This is a big one. The IRS sees you and your spouse as a single unit when it comes to wash sales. If you sell a stock for a loss in your brokerage account, and your spouse buys the exact same stock in their account within the window, the rule still applies.
The IRA trap is even worse. If you sell a stock in your taxable account and then buy it back in your IRA or 401(k), the loss is not just disallowed—it’s gone forever. You can't adjust the cost basis inside a retirement account, so that tax benefit is permanently lost.
Key Takeaway: The wash sale rule isn't tied to a single account; it's tied to you, the taxpayer. It follows you across all your accounts, your spouse's accounts, and your retirement plans.
Trading "Substantially Identical" Securities
Thinking you can outsmart the rule by selling one S&P 500 ETF (like SPY) and immediately buying another (like VOO) is playing with fire. While not explicitly defined, the IRS could easily argue these are "substantially identical," and your loss would be disallowed.
The Fix:
The safest bet is to switch to a fund that tracks a different, even if similar, index. For instance, you could sell a fund that tracks the S&P 500 and buy one that tracks the Russell 1000 instead. While keeping the wash sale rule in mind, it's also a good idea to stay aware of other common trading mistakes that can chip away at your returns.
Strategic Ways to Navigate the Wash Sale Rule
Learning the ins and outs of the 30-day wash sale rule is more than just a defensive move to stay out of trouble with the IRS. It's about flipping the script—moving from simply avoiding a penalty to actively planning your tax strategy. Once you get comfortable with the rules of the game, you can legally and powerfully use tax-loss harvesting to your advantage.
There are a few well-established ways to lock in an investment loss without tripping over the wash sale rule. Let's walk through them so you can turn what seems like a headache into a real tool in your financial toolkit.
The Simplest Strategy: Just Wait It Out
The most direct path to avoiding a wash sale is exactly what it sounds like: patience. After you sell a stock or fund at a loss, just wait 31 days before you buy it back.
It’s that simple. Mark your calendar, set a phone alert, whatever it takes. Once you're past that 31-day mark, you're free and clear to repurchase the same security if you still believe in its future. This approach takes a little discipline, but it’s completely foolproof.
Swapping for a Similar (But Not Identical) Asset
But what if you want to book that loss and stay invested in a particular industry or market segment? This is where a little strategic swapping comes in handy. The idea is to sell your losing investment and immediately use the cash to buy something similar, but not "substantially identical."
This tactic is incredibly common with exchange-traded funds (ETFs) and mutual funds.
For instance:
- You sell an ETF that tracks the S&P 500, like the SPDR S&P 500 ETF (ticker: SPY).
- You immediately reinvest the proceeds into an ETF that tracks the entire U.S. stock market, like the Vanguard Total Stock Market ETF (ticker: VTI).
Even though both funds give you broad exposure to U.S. companies, they follow different indexes. That distinction is usually enough to sidestep the wash sale rule, letting you claim the loss while keeping your skin in the game.
A quick word of caution: Selling one S&P 500 index fund and immediately buying another from a different company is a bit of a gray area. To be on the safe side, it’s always better to pick a replacement that tracks a different, even if it's closely related, index.
The "Doubling Up" Technique
This one's a bit more advanced and is perfect for investors who are still bullish on a stock they're holding at a loss. Instead of selling, you actually buy more first.
Here’s the step-by-step:
- Buy More: Purchase the same number of shares you already own, doubling your position.
- Wait 31 Days: Now, you hold this larger position for at least 31 days. This is the crucial waiting period.
- Sell the Original Shares: After the wait, you specifically sell your original shares—the ones with the higher cost basis—to finally realize the capital loss.
Because you waited more than 30 days between the new purchase and the sale of the old lot, you don't trigger the wash sale rule. You've successfully harvested the tax loss without ever giving up your position in the company. This move does require more capital upfront, but for a committed long-term investor, it can be a very savvy play.
Answering Your Top Wash Sale Questions
Even when you've got the basics down, the 30-day wash sale rule can throw some curveballs. Let's tackle some of the questions that come up most often.
Does the Wash Sale Rule Apply if I Sell for a Profit?
Nope. This is one of the most common points of confusion, but the answer is a simple no. The wash sale rule only cares about losses.
The whole point of the rule is to stop people from claiming a tax loss on paper while essentially holding the same investment. If you sell for a gain, the IRS is happy to take your tax money, so you can buy that same security back five minutes later without any issue.
What Happens if I Create a Wash Sale in My IRA?
This is the absolute worst-case scenario and a costly mistake to avoid. Let's say you sell a stock at a loss in your regular brokerage account. Then, within the 61-day window, you buy that same stock back inside your IRA.
That loss from your brokerage account is gone. Forever. You can't claim it. Because an IRA is a tax-advantaged account, you can't adjust the cost basis of the shares inside it. The loss doesn't get deferred—it just vanishes.
This is a permanent loss of a valuable tax deduction, so be extremely careful when trading the same securities in both taxable and retirement accounts.
Does the Rule Apply to My Spouse’s Trades?
It absolutely does. For the purpose of the wash sale rule, the IRS views you and your spouse as a single unit.
If you sell a stock for a loss, and your spouse repurchases that same stock within the 30-day window (before or after your sale), it triggers the rule. Your loss will be disallowed. This is why communication is key, especially when you're both managing separate portfolios and trying to do some tax-loss harvesting at year-end.
Does the 30-Day Wash Sale Rule Apply to Cryptocurrency?
For now, the answer is no. The IRS currently classifies cryptocurrencies like Bitcoin and Ethereum as property, not securities. This means the wash sale rule, which is written specifically for securities, doesn't apply to them.
However, this could change. Washington has been buzzing with proposals to apply wash sale rules to digital assets. It's a space you'll want to watch closely for any new legislation.
Navigating the wash sale rule and other tax complexities doesn't have to be a solo effort. The team at Allied Tax Advisors offers personalized tax planning to help you make smarter financial moves. Learn more at https://alliedtax.com.