
If you're trying to get a handle on your business's finances, two documents are absolutely essential: the Profit & Loss (P&L) statement and the Balance Sheet. The easiest way to remember the difference comes down to time.
Think of it this way: your P&L is like a movie, documenting your company's financial performance over a specific period. On the other hand, the Balance Sheet is a single snapshot, capturing your financial position at one precise moment in time. The P&L tells you if you made money, while the Balance Sheet shows what you own and what you owe.
The Core Difference: A Snapshot vs. A Movie
To really see how these reports work together, it helps to understand what a financial statement is at a high level and the distinct job each one does. The P&L, often called an income statement, tells the story of your company's operations. It tracks all the revenue you’ve earned and the expenses you’ve paid out over a quarter or a year, ultimately leading to your net profit or loss—that all-important "bottom line." This narrative is crucial for spotting trends, managing costs, and judging your overall profitability.
The Balance Sheet has a completely different mission. It isn't concerned with performance over a stretch of time; its purpose is to give you a crystal-clear picture of your company’s financial health on one specific day. It all boils down to a fundamental accounting equation: Assets = Liabilities + Equity. This statement reveals your company’s solvency by listing everything it owns (assets) against everything it owes to others (liabilities) and to its owners (equity).
Key Takeaway: The P&L shows performance over a period, answering, "How did we do?" The Balance Sheet shows position at a point in time, answering, "Where do we stand right now?"
This infographic does a great job of breaking down the core differences in their focus, purpose, and the key elements they contain.
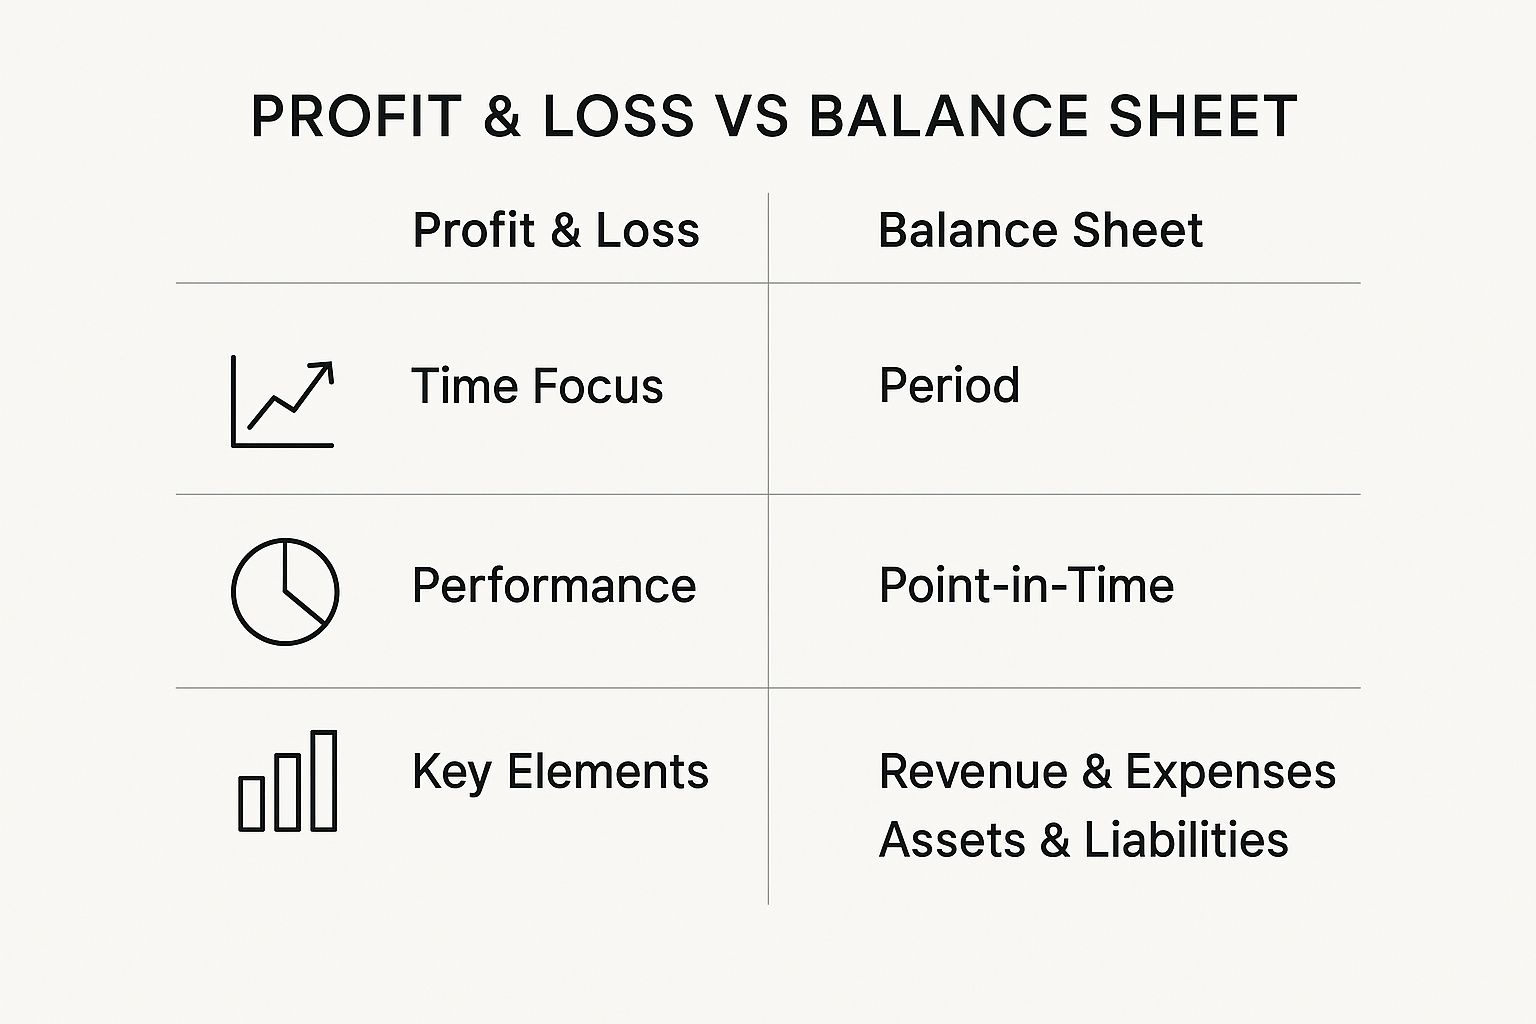
As you can see, one document tracks dynamic activity (the P&L), while the other captures a static condition (the Balance Sheet).
P&L vs. Balance Sheet: At a Glance
The core difference between these two reports really is about their function and timing. The P&L is all about profitability over a period, while the Balance Sheet is a snapshot of your financial standing. How you record transactions also matters—understanding the https://alliedtax.com/difference-between-cash-basis-and-accrual-basis/ is key, as this choice directly impacts how numbers show up on both statements.
This table neatly summarizes the key distinctions to help you keep them straight.
Key Distinctions: P&L vs. Balance Sheet at a Glance
| Attribute | Profit & Loss (P&L) Statement | Balance Sheet |
|---|---|---|
| Time Frame | Shows performance over a period of time (e.g., a month, quarter, or year). | Provides a snapshot of financial position at a single point in time (e.g., as of Dec 31). |
| Purpose | To measure a company's profitability and operational efficiency. | To show a company's overall financial health, solvency, and liquidity. |
| Core Components | Revenues, Expenses, Gains, and Losses. | Assets, Liabilities, and Owner’s/Shareholder's Equity. |
| Key Equation | Revenue – Expenses = Net Income (or Loss) | Assets = Liabilities + Equity |
In short, you can't get a full picture with just one of these reports. You need both the movie and the snapshot to truly understand your business's financial story.
Decoding the Profit and Loss Statement
If the balance sheet is a static photo, the Profit and Loss (P&L) statement is the movie of your company's financial story. It captures the action, showing exactly how your business performed over a specific stretch of time—be it a month, a quarter, or a full year. The P&L answers the most fundamental question any owner has: "Did we actually make any money?"
The P&L is laid out intuitively, starting at the top and flowing down to the famous "bottom line." This structure is designed to show you precisely where your money comes from and where it all goes, step by step. Let's break down the key parts.
Top-Line Revenue and Gross Profit
Everything kicks off with Revenue (also called Sales). This is the total amount of money your business brought in from its core operations. It's the "top line," representing every dollar earned before a single expense is taken out.
Right after revenue, you subtract the Cost of Goods Sold (COGS). These are the direct costs of producing what you sell. For a retail shop, it’s the wholesale cost of the items on your shelves. For a coffee shop, it’s the coffee beans, milk, and cups.
Subtracting COGS from your revenue gives you the Gross Profit. This is a powerful number. It tells you how efficiently you're producing your goods or services, and it's the pot of money you have left over to pay for everything else.
Operating Expenses and Net Income
Next up on the P&L are your Operating Expenses (OPEX). Think of these as the cost of keeping the lights on. They're all the expenses necessary to run the business that aren't directly part of the product itself.
This category covers a lot of ground, including things like:
- Salaries and Wages: What you pay your team.
- Rent and Utilities: The cost of your office or storefront, plus electricity, water, and internet.
- Marketing and Advertising: Everything you spend to get the word out.
- Depreciation: This is a unique one. It's a non-cash expense that accounts for the wear and tear on your long-term assets, like a delivery van or a big piece of machinery, by spreading its cost over its useful life.
Once you subtract all these operating expenses from your Gross Profit, you get your Operating Income. This figure reveals the profit you've made purely from your main business activities.
A healthy gross profit but a weak net income is a classic red flag. It tells you your core product is profitable, but your overhead and operating costs are eating up all the cash before it hits your bank account.
After factoring in other items like interest payments and taxes, you finally arrive at the Net Income. This is the bottom line, the ultimate measure of whether your business was profitable during that period. It's the final score.
Mastering the Balance Sheet Equation
If the P&L statement is the movie of your business's financial performance, the balance sheet is a single, revealing snapshot. It offers a static, crystal-clear picture of your company’s financial health on one specific day—say, the last day of the quarter or the fiscal year. This whole report hinges on one elegant and unbreakable rule: the accounting equation.
At its core, the equation is simple: Assets = Liabilities + Equity.
This formula must always balance. If it doesn't, you know something is off in your books. It's a built-in check that perfectly summarizes what a business owns (Assets), what it owes (Liabilities), and what’s left over for the owners (Equity). Grasping this is fundamental to seeing the real difference between P&L and balance sheet reporting. The P&L tracks flow over time, while the balance sheet captures a position in time.
Breaking Down Assets
Assets are simply the economic resources your company controls that are expected to provide future benefit. To make sense of them, we usually split them into two groups based on how quickly they can be turned into cash.
- Current Assets: Think of these as your short-term resources. They're assets you expect to use up or convert into cash within a year. This bucket includes the cash in your bank account, accounts receivable (what your customers owe you), and inventory on the shelves.
- Long-Term Assets: Sometimes called fixed assets, these are the workhorses of your business. They’re not intended for quick sale and include things like property, major equipment (that fancy espresso machine), and company vehicles.
It's important to remember that these long-term assets wear out. They lose value over time, and we account for this through depreciation. The depreciation expense for a single period hits your P&L, but the accumulated depreciation—the total wear and tear over the asset's life—reduces its value on the balance sheet.
Understanding Liabilities and Equity
Now for the other side of the equation. Liabilities and equity explain who has a claim on all those assets we just talked about.
Liabilities are your company's debts and obligations to others. Just like assets, they're sorted by their due date.
- Current Liabilities: These are the bills you have to pay within the next year. It includes things like accounts payable (what you owe your suppliers), short-term loans, and accrued expenses like the upcoming payroll.
- Long-Term Liabilities: These are obligations that won't come due for more than a year. A multi-year business loan or a mortgage on your building are perfect examples.
Equity is the owners' stake in the business. It's what's left over after you subtract all the liabilities from all the assets. You can think of it as the net worth of the company—what the owners would theoretically walk away with if they sold everything and paid off every single debt.
Let's go back to our coffee shop. On December 31st, its balance sheet would list cash, coffee bean inventory, and the espresso machine under assets. On the other side, it would show what it owes its milk supplier and the outstanding balance on its business loan as liabilities. The value that remains is the owner's equity.
Seeing it laid out can make all the difference. Taking a look at a sample balance sheet for a small business is a great way to see how all these pieces fit together in a real-world format.
Comparing How Financial Events Impact Each Statement
Knowing the definitions is one thing, but the real "aha!" moment comes when you see these statements react to actual business events. The true difference between a P&L and a balance sheet shines through when you trace how a single transaction ripples through your financials.
Let's walk through a few everyday scenarios. Watching how these two reports respond differently to the same event is the best way to understand their unique jobs in telling your company's story.
Scenario 1: Taking Out a Business Loan
Let's say you secure a loan from the bank. That cash hits your account, and while it feels like a big financial move, it doesn't touch your P&L at all—at least, not at first.
Here's how it plays out:
- On the Balance Sheet: Your Cash (an asset) goes up. At the same time, a new Loan Payable (a liability) appears for the exact same amount. The fundamental accounting equation, Assets = Liabilities + Equity, stays perfectly balanced.
- On the P&L: Nothing happens. There's no initial impact. That loan isn't revenue; it's money you have to pay back. Since it doesn’t reflect your company's operating performance, it has no place on the P&L.
The P&L only comes into play later when you start making payments. The interest expense portion of each payment will show up on the P&L, reducing your net income for that period.
Scenario 2: Buying Equipment with Cash
Now, imagine you take some of that cash and buy a new machine for the workshop. This is a classic example of a transaction that lives entirely on the balance sheet. You’re simply trading one type of asset for another.
- On the Balance Sheet: Your Cash account (a current asset) decreases. Simultaneously, your Equipment account (a long-term asset) increases by the very same amount. Your total asset value doesn't change; it’s just been rearranged.
- On the P&L: Once again, no immediate impact. Buying a long-term asset is a capital expenditure, not a day-to-day operating expense. The P&L won't see this transaction until depreciation kicks in.
Key Insight: Over time, that new machine will lose value. This is recorded as a depreciation expense on the P&L each month or year. It’s a non-cash expense that reduces your net income and reflects the "using up" of the asset's value.
Scenario 3: Making a Sale on Credit
Finally, what happens when you sell a product to a customer and send them an invoice due in 30 days? This is where you see the two statements working in tandem, a perfect illustration of accrual accounting.
- On the P&L: The sale is recognized as Revenue the moment it happens. This instantly boosts your gross profit and flows right down to the bottom line, reflecting a successful period of performance.
- On the Balance Sheet: You haven't been paid yet, so cash doesn't change. Instead, your Accounts Receivable (an asset) increases. This line item represents the money you’re now owed by the customer.
Later, when the customer pays that invoice, the action is confined to the balance sheet: your Cash goes up, and your Accounts Receivable goes down.
Analytical methods like vertical analysis, which you can learn more about in this guide from WallStreetPrep.com, make these distinctions even clearer. By converting line items to percentages, you can see how balance sheet ratios focus on financial risk and stability, while P&L metrics are all about operating efficiency. It reinforces that you need both to get the full picture of a company's health.
How the P&L and Balance Sheet Connect
It’s easy to think of the P&L and balance sheet as two separate documents, but they’re actually two sides of the same coin. They work together, telling a complete financial story that one report alone simply can't capture. The real insight comes when you see how the story of your performance (the P&L) directly feeds into the snapshot of your financial position (the balance sheet).
This connection is the key to understanding how your business evolves over time.
The most direct link between them is net income. Think of it as a bridge. At the end of every accounting period, whether it's a month, quarter, or year, the net income—the "bottom line" from your P&L—flows straight into the equity section of your balance sheet.
This transfer is what builds your company's financial foundation. A profitable period increases your equity, strengthening the business. A loss, on the other hand, will chip away at it. This specific line item where the magic happens is called Retained Earnings.
The Retained Earnings Connection
Retained Earnings is the running tally of all the profits your business has generated and kept since it started. When you close out a new P&L period, the net income you earned is added to the Retained Earnings balance from the previous period. This is how past performance directly shapes your current financial standing.
Let's say your company had $50,000 in retained earnings at the start of the year. Your P&L for that year shows a net income of $20,000. Your new retained earnings balance is now $70,000. That increase in equity makes the business more valuable and financially stable. This is precisely why learning how to prepare financial statements accurately is so critical—it ensures this vital link is reported correctly.
The Flow of Profit: Net Income (from the P&L) → Increases Retained Earnings (on the Balance Sheet) → Increases Total Equity. This single flow is the most important interaction between the two reports.
Seeing the Connection Over Time
This dynamic relationship is why you can't get the full picture from just one statement. A single profitable year on the P&L looks fantastic, but the balance sheet might reveal that all that profit is stuck in unpaid invoices (Accounts Receivable). That could signal a serious cash flow problem brewing beneath the surface.
Looking at the history of large public companies really drives this point home. You can see how years of profits or losses on the P&L have shaped their balance sheets, for better or worse. Changes on a company's balance sheet are essential for assessing its financial health and capital structure, while its P&L shows how effectively it generated that profit or loss over the same period. For a deeper dive, balance sheet trend analysis on Saylor Academy offers great examples of how these static positions and dynamic performance figures provide different, yet complementary, perspectives.
Who Uses These Statements and Why It Matters
Financial statements aren't just for accountants or tax season. They're the go-to tools for anyone with a stake in a company's success, but different people look at them for very different reasons. The real magic happens when you know which report answers which question.
A business owner might obsess over the P&L to track monthly sales, while a banker lending money will zero in on the balance sheet to assess risk. Each person is pulling out the specific information they need to make a smart decision.
For Business Owners and Managers
If you're running the show, these two statements are your command center. They just control different parts of the operation.
The P&L is your operational scorecard. It’s what you look at to see if your pricing is right, if your marketing campaigns are paying off, or if your costs are getting out of hand. It answers the crucial, everyday question: "Are we actually making any money?"
The balance sheet is for the big-picture, strategic thinking. It helps you manage debt, decide if you can afford that new piece of equipment, and make sure you have enough cash to pay your bills next month. It answers the fundamental question: "Is this business built to last?"
For Investors and Lenders
People on the outside, like investors and lenders, look at your financials to size up risk and potential reward. They absolutely need both statements to get a clear picture before putting their money on the line.
-
Investors often start with the P&L. They’re hunting for growth—climbing revenue and fat profit margins tell them the business has a winning formula. But they’ll quickly flip to the balance sheet to check for red flags, like scary debt levels or flimsy assets.
-
Lenders, on the other hand, are all about the balance sheet’s stability. They want to see that you have more assets than liabilities before they'll even consider a loan. Once they’re comfortable with your solvency, they'll use the P&L to confirm you're profitable enough to make the monthly payments.
The Bottom Line: The P&L shows if a company is good at making a profit. The balance sheet shows if it's strong enough to pay its bills and survive tough times.
At the end of the day, one report just doesn't tell the whole story. You need the P&L's tale of performance and the balance sheet's snapshot of stability to communicate your company's true financial health.
A Few Common Questions About Financial Statements
Even with a solid grasp of the basics, a few practical questions always pop up when people start working with these reports. Let's tackle some of the most frequent ones to clear up how this all works in the real world.
How Often Should I Prepare These Reports?
For most businesses, running a P&L monthly is standard practice. It’s the best way to keep a finger on the pulse of your performance and spot trends early.
The balance sheet is then typically prepared at the end of each of those same periods. This gives you a financial snapshot that lines up perfectly with the end date of your P&L, whether that's the last day of the month, the quarter, or the year.
So, Where Does the Cash Flow Statement Fit In?
Think of the Statement of Cash Flows as the third, essential piece of the puzzle. It’s the bridge that connects your P&L and balance sheet. It shows you exactly how cash moved in and out of the company from three core activities: operations, investing, and financing.
Ultimately, its job is to explain how you got from the net income on your P&L to the change in the cash balance on your balance sheet over that same period.
Key Takeaway: Your P&L might show a healthy profit, but the Cash Flow Statement tells you if you actually have the cash on hand to pay your bills. For any business owner, that distinction is everything.
If you're looking to get more comfortable with interpreting these critical documents, you can find excellent guidance on reading company financial statements.
At Allied Tax Advisors, we help you move beyond the numbers and turn your financial data into actionable insights for your business. Let us handle the complexities of your accounting and tax needs so you can focus on growth. Learn more at https://alliedtax.com.