
Think of bonus depreciation as hitting the fast-forward button on your tax deductions. Instead of spreading out the tax write-off for a new piece of equipment over several years, this powerful tax incentive lets you deduct a huge chunk—and until recently, 100% of it—in the very first year you put it to work.
The result? A lower tax bill, right now. This strategy is all about improving your immediate cash flow, freeing up money you can put back into your business when you need it most.
The Big Picture: What Is Bonus Depreciation?
Let's say your business invests in a new delivery van for $50,000. Under the old rules of standard depreciation, you might only get to deduct a small piece of that cost, maybe $10,000, in the first year. Bonus depreciation completely changes the game. It allows you to write off a much larger portion, potentially the entire $50,000, right away.
It's crucial to understand this isn't some extra "free" deduction. You're simply taking the tax benefit you would have received over the asset's entire life and pulling it all into year one. By front-loading the deduction, you dramatically reduce your taxable income for the current year.
Core Benefits for Your Business
This front-loaded approach isn't just a neat accounting trick; it’s a cornerstone of savvy tax planning that can have a real, immediate impact on your company's financial health.
Here’s what that looks like in practice:
- Boosted Cash Flow: A lower tax bill means more cash stays in your bank account. You can use that money to hire new staff, invest in marketing, pay down debt, or simply build a stronger financial cushion.
- Accelerated ROI: When you get a significant tax break right after buying an asset, you effectively lower its after-tax cost. This helps you recoup your investment and see a positive return much faster.
- Simplified Tax Planning: While the rules can be complex, taking the deduction all at once can simplify your long-term depreciation schedules for those assets, making future tax years a little cleaner.
How It Became a Go-To Tax Strategy
Bonus depreciation is a tax incentive designed to encourage businesses to invest in themselves. It allows for the immediate deduction of a large percentage of the purchase price of qualifying property—think machinery, equipment, computers, and even vehicles—in the year you start using it.
The game really changed with the Tax Cuts and Jobs Act (TCJA) of 2017. This legislation supercharged the incentive, bumping the first-year deduction from 50% all the way up to a full 100% for assets acquired and placed in service after September 27, 2017.
The essence of bonus depreciation is simple: it prioritizes your current financial health. By allowing a significant upfront deduction, it gives you immediate access to capital that would otherwise be tied up for years.
It’s important not to confuse this with other tax concepts, like the flat https://alliedtax.com/understanding-the-bonus-tax-rate-how-much-of-your-bonus-you-keep/ that applies to employee bonuses. While both involve the word "bonus," they operate in completely different areas of the tax code.
To wrap your head around the core advantages, this quick summary table breaks it down.
Key Benefits of Bonus Depreciation at a Glance
| Benefit | Business Impact |
|---|---|
| Immediate Tax Savings | Lowers your current year's taxable income, resulting in a smaller tax bill. |
| Increased Liquidity | Frees up cash that can be immediately reinvested into the business. |
| Stimulates Investment | Encourages purchasing new equipment by reducing the after-tax cost. |
Ultimately, bonus depreciation provides a direct and immediate financial reward for investing in your company's growth.
Who and What Qualifies for This Tax Break
So, who actually gets to take advantage of bonus depreciation? And what kinds of purchases count? Getting these answers right is the first step to using this powerful tax-saving tool. The good news is the rules are pretty broad, designed to encourage all sorts of businesses to invest in themselves. Still, there are a few key details every owner needs to know.
First off, nearly every kind of business entity is on the approved list. It doesn't matter if you're a sole proprietorship, a partnership, an S Corp, or a C Corp—this incentive is on the table for you.
The main exception to the rule? Certain regulated public utility companies. They're generally excluded because their pricing and rate structures already build in asset costs, so from a policy standpoint, giving them this extra break would be redundant.
Identifying Eligible Assets
The real nitty-gritty of bonus depreciation is figuring out which assets qualify. The IRS has laid out a clear set of guidelines for what kind of property is eligible for this big, upfront deduction.
The main rule of thumb is that the asset must have a depreciable life of 20 years or less under the standard tax system (known as MACRS). This simple rule covers a huge range of common business purchases.
Here’s a quick rundown of the things that typically qualify:
- Machinery and Equipment: This is the big one. It covers everything from heavy manufacturing gear and farm equipment to specialized tools for your trade.
- Computers and Software: All your office computers, servers, and any off-the-shelf software you buy are good to go.
- Office Furniture and Fixtures: Think desks, chairs, cabinets, and anything else you use to furnish your workspace.
- Certain Vehicles: Business vehicles can be a huge deduction. Heavier trucks, vans, and SUVs with a gross vehicle weight over 6,000 pounds often qualify for a 100% write-off in the first year. Regular passenger cars have some specific dollar limits, though.
- Qualified Improvement Property (QIP): This is a fancy term for most interior, non-structural upgrades you make to a commercial building you're already using.
Bonus depreciation is a fantastic tool, but it's just one piece of the puzzle. To build a complete financial strategy, it's smart to explore all the other valuable small business tax deductions available to you.
The New vs. Used Property Rule
One of the biggest changes in recent years came from the Tax Cuts and Jobs Act (TCJA) back in 2017. Before that law, bonus depreciation was almost exclusively for brand-new stuff. The TCJA opened the door for businesses to claim it on used property, too.
This was a game-changer, especially for small businesses. It meant buying a used delivery truck or pre-owned equipment could suddenly trigger the exact same powerful, first-year tax deduction as buying something straight from the factory.
This simple change made bonus depreciation far more flexible. Businesses working with a tighter budget could now make smart investments in used assets and still get the full, immediate tax benefit.
The "Placed in Service" Requirement
Here's a critical timing rule: just buying an asset isn't enough. To claim the deduction for a tax year, you have to officially "place it in service" during that year. This is IRS-speak for the asset being ready and available for its specific job in your business.
For example, you buy a new piece of equipment on December 28th, but it just sits in a crate in the corner until January. You can't claim the deduction for the year you bought it. But if you unbox it, set it up, and have it ready for an employee to use on December 31st, you've met the requirement.
This makes "placed in service" a huge factor in year-end tax planning. You have to make sure your qualifying purchases are actually up and running before the ball drops on New Year's Eve if you want to lock in that deduction for the year.
How Legislative Changes Have Shaped Current Rates
To really get a handle on bonus depreciation today, you have to understand its recent, and frankly, pretty wild history. The rules and rates have been a moving target, which has a massive impact on how businesses plan their big-ticket purchases. The journey from a temporary shot in the arm to a stable part of the tax code is a story of legislative whiplash that has completely changed financial strategy for companies nationwide.
The biggest shake-up came with the Tax Cuts and Jobs Act (TCJA) of 2017. This law basically put bonus depreciation on steroids, cranking the deduction all the way up to 100%. It was a game-changer, letting businesses write off the entire cost of new equipment and other qualifying assets in the year they bought them. But there was a catch—it wasn't meant to last forever.
The Original Phase-Down Plan
The TCJA came with a built-in expiration date for the 100% rate. It was designed to slowly fade away, with a gradual phase-down scheduled to kick off in 2023. This created a ticking clock for businesses, essentially telling them to "buy now or get a smaller tax break later."
This planned reduction threw a real wrench into long-term capital planning. The phase-out schedule that started in 2023 was set to slash the deduction each year: down to 80% in 2023, then 60% in 2024, and eventually hitting 0% by 2027. If you want to dive deeper into the original schedule, you can find a good historical overview of the TCJA's impact on business investment planning on cbh.com.
Imagine you were planning a major purchase in 2024. Under that old schedule, you were looking at a much smaller tax break than if you had pulled the trigger just a year earlier. That kind of uncertainty can grind investment decisions to a halt.
This is a great visual for seeing just how powerful the immediate write-off is compared to spreading it out over time.
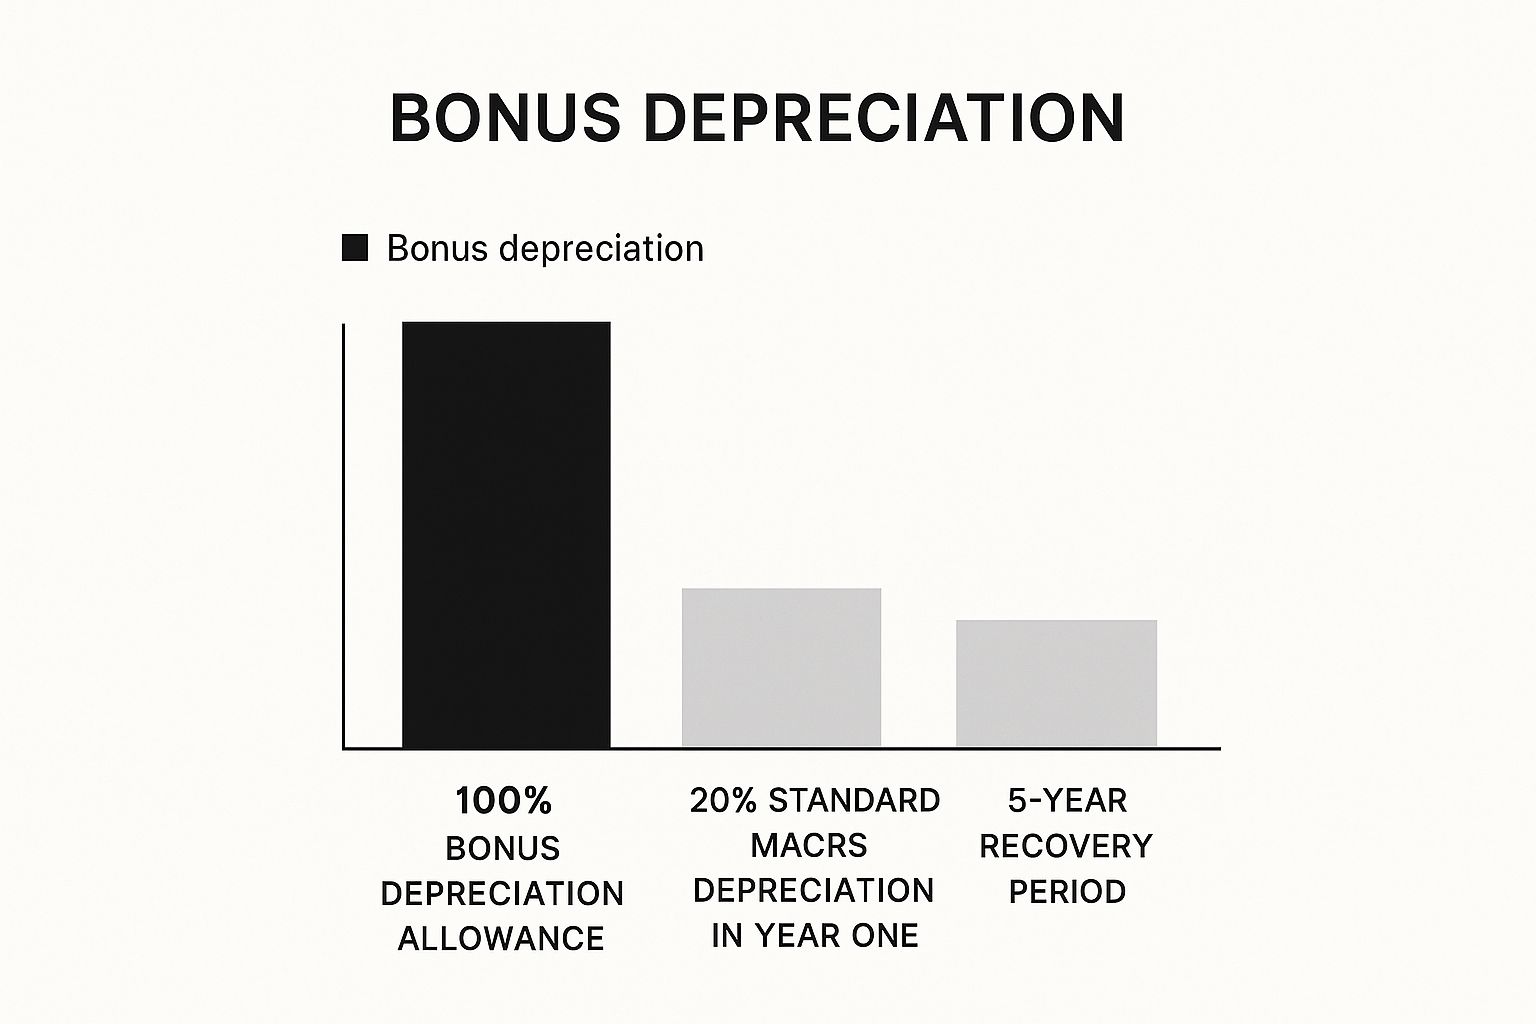
As you can see, the 100% allowance delivers a massive first-year deduction, which directly translates to more cash in your pocket right away.
A Legislative Reversal Secures 100 Percent
Thankfully, lawmakers saw the uncertainty this phase-down was causing and decided to act. A major legislative reversal in 2025 changed the game again, but this time for the better—it made the 100% bonus depreciation rate permanent.
This was a fundamental shift in tax policy.
Instead of being a temporary stimulus that was slowly fizzling out, the 100% deduction became a reliable, long-term planning tool. Businesses could finally breathe a sigh of relief and budget for future investments knowing the full tax benefit would be there when they needed it.
That stability is everything. It allows companies to make smart, strategic decisions based on what the business actually needs, not just on trying to beat a looming tax deadline. Making the 100% rate permanent has cemented its role as a key financial planning tool for any business that relies on heavy equipment and other major assets.
To see just how big of a deal this change is, let's look at the real-world dollars and cents. The table below shows the first-year deduction a business would get on the same asset under the old phase-down plan versus the current permanent rate.
Bonus Depreciation Rate Phase-Down vs. Reinstatement
The difference is stark. This table illustrates the first-year write-off for a $100,000 asset under the old, declining rates compared to the now-permanent 100% rate.
| Tax Year | Original Phase-Down Rate | Current Permanent Rate | First-Year Deduction on a $100,000 Asset |
|---|---|---|---|
| 2023 | 80% | 100% | $100,000 (vs. $80,000) |
| 2024 | 60% | 100% | $100,000 (vs. $60,000) |
| 2025 | 40% | 100% | $100,000 (vs. $40,000) |
| 2026 | 20% | 100% | $100,000 (vs. $20,000) |
The numbers don't lie. Locking in the 100% rate provides a much larger and, more importantly, a consistent tax advantage year after year. This newfound stability gives businesses the confidence to plan for the future and invest in the tools they need to grow.
Let's Run the Numbers: A Real-World Example
Theory is great, but seeing how the numbers shake out on a real purchase is where the power of bonus depreciation really clicks. Let's move from concept to cash flow by walking through a practical example, step-by-step. This will show you exactly how the calculation works and just how significant the financial impact can be.
To make it concrete, let's invent a small company: "ForgeForward Manufacturing." They need to upgrade a key piece of their production line, and this scenario will highlight how the deduction directly impacts their bottom line.
Scenario: The $80,000 Equipment Purchase
ForgeForward Manufacturing decides to invest $80,000 in a new, state-of-the-art metal stamping machine. This equipment is a perfect candidate for bonus depreciation—it's tangible business property with a depreciable life under 20 years. They get it up and running in October, well before the end of the year.
The math behind the deduction is refreshingly simple.
- Start with the Asset's Cost Basis: The starting line is the equipment's full purchase price, $80,000.
- Apply the Current Bonus Depreciation Rate: For new equipment, the current rate is a full 100%.
- Calculate the Deduction: Just multiply the cost by the rate: $80,000 x 100% = $80,000.
And that's it. For that tax year, ForgeForward Manufacturing can deduct the entire $80,000 cost of the machine from its taxable income.
The Impact: A Tale of Two Depreciation Methods
To really grasp what a $80,000 first-year deduction means, you have to compare it to the old way of doing things—the traditional depreciation schedule known as the Modified Accelerated Cost Recovery System (MACRS). Without bonus depreciation, recovering that cost would be a much slower grind.
Under MACRS, this type of machine falls into the 7-year property class. In the first year, the formula only allows a deduction of 14.29% of the cost.
- MACRS Deduction: $80,000 x 14.29% = $11,432
- Bonus Depreciation Deduction: $80,000 x 100% = $80,000
The difference is staggering. Bonus depreciation gives ForgeForward an additional $68,568 in deductions in the first year alone. Assuming a 21% corporate tax rate, this translates to an immediate tax savings of approximately $14,400.
This isn't just a number on a spreadsheet; it’s real cash that stays in the company’s bank account. That extra liquidity can go straight to work covering payroll, funding a new marketing campaign, or buying more inventory. It’s an immediate and powerful boost for the business.
A More Nuanced Case: Vehicle Depreciation Limits
While the 100% write-off is a game-changer, it’s crucial to know that it sometimes bumps up against other tax rules. Business vehicles are a prime example, as they often have their own specific limitations, particularly when it comes to "luxury" passenger cars.
Let's imagine a consulting firm buys a new SUV for $70,000 to be used 100% for business. Because its gross vehicle weight rating (GVWR) is over 6,000 pounds, it qualifies as a "heavy" vehicle and sidesteps the usual luxury auto depreciation caps.
- Asset Cost: $70,000
- Bonus Depreciation Rate: 100%
- First-Year Deduction: $70,000
The firm gets to write off the entire vehicle cost right away. This specific rule is a huge reason why so many businesses opt for heavier SUVs, trucks, and vans.
But let's flip the script. A real estate agent buys a new sedan for $50,000, also for exclusive business use. As a standard passenger vehicle, it's subject to the luxury auto limits. For a new car put into service in 2024, the maximum first-year depreciation—even with the 100% bonus rule in play—is capped at $20,400.
Even though the bonus depreciation rate is 100%, the more specific vehicle rule takes precedence.
- Asset Cost: $50,000
- Bonus Depreciation Allowed: $20,400 (due to the cap)
- Remaining Basis: $50,000 – $20,400 = $29,600
The leftover $29,600 isn't lost, it just gets depreciated in the following years based on the standard MACRS schedule for vehicles. This is a perfect illustration of why you always have to look at the big picture—bonus depreciation is a fantastic tool, but you must account for any other specific rules that apply to your asset to stay compliant.
Making the Right Strategic Choice for Your Business
Knowing the mechanics of bonus depreciation is one thing, but the real art is knowing when to use it—and just as importantly, when to skip it. That 100% immediate deduction is a powerful tool, no doubt, but it’s definitely not a one-size-fits-all solution. Making the right call means looking past this year’s tax return and thinking about your company’s long-term financial picture.
For a lot of businesses, taking the full deduction is a no-brainer. It gives you a direct and immediate cash flow boost, freeing up money you can pour back into growth, use to pay down debt, or just keep as a rainy-day fund.
When to Go All In on Bonus Depreciation
Grabbing that 100% deduction makes the most sense in a few key situations. If your business is riding a wave of high profitability, a massive deduction can seriously slash your tax bill right when you need that relief the most. It’s a fantastic way to shelter income during your best years.
Think about these ideal scenarios for claiming the full amount:
- During High-Profit Years: When revenue is pouring in, your tax bill naturally swells. A huge deduction is the perfect counterpunch, maximizing your tax savings on the spot.
- When You Need Immediate Cash Flow: Got big plans? Maybe you're expanding, hiring, or launching a new marketing push. The tax savings can provide the exact liquidity you need to make it happen.
- Before Anticipated Tax Rate Increases: If you have a feeling tax rates are heading north, it's smart to take the biggest deduction you can right now while the rates are lower. It's a solid defensive play.
By lining up the deduction with your company’s peak earning periods, you get the biggest bang for your buck, right away.
The decision to claim bonus depreciation is a forecast about your company's future. It's a choice between a large, certain benefit today versus potentially smaller, spread-out benefits tomorrow.
The Strategic Decision to Elect Out
It might sound crazy, but sometimes the smartest move you can make is to pass on the immediate 100% deduction. This is called "electing out," and it’s a strategic choice for businesses with a different financial road ahead. When you opt out, you fall back to a traditional MACRS depreciation schedule, which spreads the deductions out over the asset's useful life.
So, why on earth would a business turn down a huge upfront tax break? It all comes down to what you expect in the future.
Take a startup, for example. It might be operating at a loss or with razor-thin profits in its first few years. In that case, a massive deduction would mostly go to waste because there’s little or no taxable income to offset.
This is where long-term planning is absolutely critical.
- Startups and Growth-Stage Companies: If you’re expecting profits to skyrocket in the coming years, spreading out your deductions can be far more valuable. A $20,000 deduction does a lot more good against a future $200,000 profit than it does against a $10,000 profit today.
- Navigating Net Operating Losses (NOLs): If a big deduction would either create or deepen a net operating loss, you might be better off saving those deductions for future, more profitable years when you can actually use them.
This approach is all about matching your tax strategy to your business’s growth curve, making sure every dollar of deductions pulls its weight. This is just one of many strategies; you can learn how to reduce your tax bill with a variety of deductions and credits to build a more complete plan.
Federal vs. State: The Great Divide
Here's one final, crucial piece of the puzzle: the disconnect between federal and state tax laws. While the federal government gives the green light for 100% bonus depreciation, many states do not. This is known as "decoupling," where a state decides to go its own way and not conform to the federal tax code.
This can create a real headache. You might take a massive deduction on your federal return, only to have to add it all back and depreciate the asset slowly on your state return. It adds accounting complexity and can lead to a much higher state tax bill than you were expecting. Before you pull the trigger, always check your state’s specific rules on bonus depreciation to avoid any nasty surprises.
Answering Your Key Questions About Bonus Depreciation
Once you get the hang of how bonus depreciation works, a whole new set of "what if" questions usually bubbles up. These are the practical scenarios that hit you when you try to apply the rules to your own business. Let's tackle some of the most common points of confusion with clear, direct answers.
We're moving past the basics to see how bonus depreciation plays with other tax rules, what happens when you sell an asset, and how it works for more complex property. Think of this as your field guide for the real-world situations you're bound to run into.
Can I Use Bonus Depreciation and Section 179 on the Same Asset?
Yes, you absolutely can, and it's a popular—and powerful—tax planning strategy. The trick is to apply them in the right order. Businesses typically use the Section 179 deduction first, writing off a chunk of the asset's cost up to the annual limit.
After taking Section 179, you can then apply 100% bonus depreciation to whatever cost is left. If there's still any basis remaining after that, regular MACRS depreciation kicks in for the rest.
This one-two punch is especially handy for state tax planning. Some states don't recognize bonus depreciation but do allow Section 179, so stacking them helps you maximize your deductions at both the federal and state levels.
What Happens When I Sell an Asset I Took Bonus Depreciation On?
This is a huge one, with serious financial implications. When you sell an asset that you previously claimed bonus depreciation on, you’ll almost certainly face something called depreciation recapture.
Since the 100% deduction effectively dropped the asset's book value to zero, any money you get from the sale (up to its original cost) is taxable. The kicker? That income is taxed at your regular ordinary income tax rate, not the much friendlier long-term capital gains rate.
Depreciation recapture is the trade-off for getting a massive tax deduction upfront. The IRS essentially says, "We let you write off the full cost, so if you sell it for a profit, we're taking our share back at your normal tax rate." It's a vital factor in your long-term asset management strategy.
It just means you need to plan for a potentially larger tax bill in the year you sell. It’s a classic balancing act: weigh the immediate tax break against future tax consequences.
Does Bonus Depreciation Apply to Real Estate?
This is a common source of confusion. Generally, bonus depreciation does not apply to a building’s structure, which gets depreciated over a very long time (usually 27.5 or 39 years). But there’s a powerful workaround: a cost segregation study.
A cost segregation study is a detailed engineering analysis that carves out specific parts of a commercial building and reclassifies them as personal property. These reclassified components have much shorter depreciation timelines—like 5, 7, or 15 years—which makes them eligible for bonus depreciation.
What kind of things can be reclassified?
- Specialty Electrical Wiring: Cabling for specific equipment or systems.
- Decorative Fixtures: Custom lighting or other non-structural design elements.
- Carpeting and Certain Flooring: Things that can be removed and replaced.
- Land Improvements: Assets like parking lots, fences, and landscaping.
By using a cost segregation study, you can dramatically accelerate deductions on a big piece of a building's cost, unlocking major tax savings that would otherwise be spread out over decades.
How Do I Elect Out of Bonus Depreciation?
What if taking the full 100% deduction isn't the right move for your business this year? You have to formally opt out—it’s not something that happens automatically.
To elect out, you need to attach a statement to your timely filed tax return for the year the property was placed in service. This election is made on a class-by-class basis. For example, you could opt out for all your 5-year property while still taking bonus depreciation on your 7-year property.
Just be aware, this decision is irrevocable for that asset class in that tax year, so it’s not a choice to make lightly. It’s a strategic move that should always be made with a clear picture of your future profit projections and, ideally, in consultation with a qualified tax advisor.
Navigating the complexities of bonus depreciation, Section 179, and long-term tax strategy requires expert guidance. At Allied Tax Advisors, our team of CPAs and enrolled agents specializes in creating personalized tax plans that align with your business goals. We help you make informed decisions today to build a stronger financial future tomorrow. Visit us at https://alliedtax.com to learn how we can optimize your tax position and support your growth.