
Figuring out your Cost of Goods Sold (COGS) is one of the most fundamental parts of business accounting. The classic formula is a great starting point: Beginning Inventory + Purchases – Ending Inventory. This simple calculation tells you the direct cost of the actual products you sold during a certain time, giving you a sharp, clear picture of your core profitability.
What COGS Is and Why It Matters
Before we get into the nitty-gritty of the math, let's talk about what COGS actually is and why it’s so critical to your business's financial health.
Put simply, the Cost of Goods Sold covers every direct cost involved in producing the items you sell. This is a completely different category from operating expenses—those are the costs of simply keeping the lights on, like marketing spend, office rent, or administrative salaries.
Let’s say you run an e-commerce boutique selling handcrafted leather bags. Your COGS would include things like:
- The cost of raw leather, buckles, and thread.
- Wages for the artisans who actually craft the bags.
- Shipping fees to get those raw materials to your workshop.
But the salary you pay your marketing manager? Or the monthly fee for your website hosting? Those are operating expenses, not COGS. Getting this distinction right is absolutely vital for accurate financial reports and making smart business decisions.
The Strategic Importance of Accurate COGS
Knowing your COGS isn't just about ticking a box for your accountant. It's a powerful tool that directly impacts how you run and grow your business. For small business owners, tracking this metric meticulously is non-negotiable. The IRS looks closely at inventory numbers; in fact, discrepancies were a factor in over 70% of small business audits between 2018 and 2023, often resulting in hefty penalties. For a deeper dive, you can learn more about how crucial cost tracking is in our guide on basic accounting for small business.
A precise COGS calculation is the bedrock of your financial statements. It directly determines your gross profit—the money left over after subtracting production costs. This single figure is a key indicator of your company's efficiency and pricing power.
A firm handle on your COGS allows you to set competitive prices that actually protect your profit margins. If your COGS is creeping up, it’s a signal that you might need to find more affordable suppliers or make your production process more efficient. On the flip side, a low COGS might mean you have the flexibility to lower prices and capture more of the market. This is especially true in industries like food service, where understanding COGS is essential for creating an accurate Profit and Loss (P&L) statement.
Ultimately, tracking COGS gives you a real-time pulse on your business's operational health. It’s a number that informs smarter decisions on everything from purchasing and pricing to tax planning, making it an indispensable metric for any business selling physical products.
Breaking Down The Standard COGS Formula

At its heart, the formula for calculating the cost of goods sold is beautifully simple: Beginning Inventory + Purchases – Ending Inventory = COGS. The math itself isn't the hard part. The real challenge, and where most businesses get tripped up, is nailing down what goes into each of those numbers.
Get one component wrong, and it can throw your entire calculation off kilter, messing with your profit margins and even landing you in hot water with the tax authorities.
Let's use a practical example to make this crystal clear. Imagine you run a local craft brewery where tracking every penny from grain to glass is essential for survival.
Starting With Your Beginning Inventory
The first piece of the puzzle is your Beginning Inventory. This is the value of all the inventory you have on hand the moment a new accounting period starts, whether that's a month, a quarter, or a year.
Here's the non-negotiable rule: your beginning inventory for this period must be the exact same number as your ending inventory from the last period.
There’s no fudging this figure. If you ended last year with $40,000 worth of raw materials (hops, malt, yeast) and finished beer, then your beginning inventory for this year is, without question, $40,000. This continuity is what keeps your financial records accurate and reliable over time.
For our brewery, let's say they closed the books on December 31st with an ending inventory value of $40,000. That means on January 1st, their beginning inventory is precisely $40,000.
Accounting For All Relevant Purchases
Next up is Purchases. This isn't just the price you paid for your raw materials. It's the total cost of acquiring and producing your inventory during the period. This is where I see a lot of mistakes happen—business owners either forget to include certain costs or, just as bad, they include expenses that don't belong here.
So, what should you track?
-
Costs to INCLUDE:
- Raw Materials: The money spent on hops, malt, and other key ingredients.
- Direct Labor: The wages you pay the brewers who are hands-on in the production process.
- Freight-In: Any shipping and handling charges to get those materials to your facility.
-
Costs to EXCLUDE:
- Marketing & Advertising: Your sales team's salaries or social media ad spend.
- Administrative Salaries: The pay for your office manager or bookkeeper.
- Rent for a Sales Office: Only overhead directly tied to the production facility counts.
Let's say our brewery spent $150,000 on malt and hops, $5,000 on freight to get those supplies delivered, and $60,000 on brewers' salaries. Add it all up, and their total Purchases for the year come to $215,000. Getting this number right is a cornerstone when you learn how to prepare financial statements.
Calculating Your Ending Inventory
Finally, we have Ending Inventory—the value of all the goods you have left at the close of the accounting period. This is often the most labor-intensive part of the formula because it demands a physical count and a valuation method (which we'll dig into later).
You can’t just estimate. You need to physically count every keg of unsold beer, every sack of grain, and every packet of yeast. Once you have the count, you assign a dollar value to it.
After a busy year, our brewery team does a full inventory count on December 31st. They determine they have $35,000 worth of inventory left on hand.
Putting It All Together
Now that we've carefully gathered all the figures, we can plug them into the formula and find the brewery's COGS for the year.
- Beginning Inventory: $40,000
- Purchases: $215,000
- Ending Inventory: $35,000
Here's the calculation:
$40,000 (Beginning Inventory) + $215,000 (Purchases) – $35,000 (Ending Inventory) = $220,000 (COGS)
The brewery’s Cost of Goods Sold for the year is $220,000. This figure tells them the direct cost of every pint they sold, giving them a clear line of sight into their production efficiency and a critical number for their income statement.
Choosing Your Inventory Accounting System
How you track inventory day-to-day isn't just an operational preference—it's a choice that fundamentally shapes how you calculate your COGS. There are really two main camps when it comes to managing stock: the perpetual system and the periodic system. Picking the right one for your business is a crucial first step toward getting financial data you can actually trust and use.
The biggest difference boils down to timing. A perpetual system gives you a live, constantly updated look at your inventory, while a periodic system is more like taking a snapshot at the end of each month or quarter. This choice will ripple out, affecting not just your COGS but also how you manage stock levels, spot sales trends, and decide when to reorder.
The Perpetual Inventory System
The perpetual inventory system is the modern, tech-forward approach. It's designed to continuously update your inventory records every single time a product is sold or a new shipment arrives. When you ring up a sale, your accounting software—think QuickBooks—doesn't just record the revenue; it simultaneously makes a second entry to reduce your inventory and post the cost of that specific item to COGS.
This method gives you an up-to-the-minute view of your stock, which is invaluable for any business that needs tight control. Imagine an electronics store or a high-end jeweler; they absolutely need to know what’s on hand at all times to avoid running out of popular, high-value items or to spot potential theft.
Here’s why so many businesses lean this way:
- Real-Time Data: You always have a clear, current picture of your stock levels and COGS.
- Improved Accuracy: It makes it much easier to spot discrepancies from theft, damage, or loss (often called shrinkage).
- Better Decision-Making: With timely data, you can make smarter purchasing decisions and forecast sales with more confidence.
Of course, this system relies on having the right tools. You'll need a solid point-of-sale (POS) system that talks to your accounting software and can handle all these automated entries without a hitch. If you're managing complex stock, it's worth seeing what's out there; for example, you can Explore timbercloud's inventory management features to get a sense of how automation can take the pain out of COGS calculations.
In practice, the perpetual system works hand-in-glove with the accrual method of accounting. It ensures that you recognize revenues and their direct costs in the very same period, giving you a much truer picture of your profitability at any given moment.
The Periodic Inventory System
On the other end of the spectrum is the periodic inventory system, which is a more traditional, manual approach. Instead of tracking the cost of each individual sale as it happens, you simply wait until the end of your accounting period—whether that’s a month, quarter, or year—and do a full physical count of everything on your shelves.
You then take that physical count to figure out your ending inventory value. From there, you just plug that number into the standard COGS formula to calculate the total cost for the entire period. It's often simpler to get started with, which is why you see it used by smaller businesses with limited inventory, like a seasonal pop-up shop or a weekend market stall.
It's also worth noting how this plays into your broader accounting choices. Many businesses using a periodic system are also weighing the difference between cash basis and accrual basis accounting for their overall books. The periodic system is definitely simpler, but the trade-off is that the information is far less timely.
Making the Right Choice for Your Business
So, which one is right for you? It really depends on the complexity of your business, your sales volume, and the value of your inventory.
| System Comparison | Perpetual System | Periodic System |
|---|---|---|
| Inventory Tracking | Continuous, real-time updates for every transaction. | Updated only at the end of an accounting period. |
| COGS Calculation | Calculated and recorded at the time of each sale. | Calculated for the entire period after a physical count. |
| Best For | High-volume or high-value inventory (e.g., electronics, auto parts). | Smaller businesses with low transaction volume or simple inventory. |
| Technology Needs | Requires integrated POS and accounting software. | Can be managed with simpler tools, even spreadsheets. |
| Insight Level | Provides deep, timely insights into stock levels and profitability. | Offers a basic, historical overview of performance. |
For most businesses that are looking to grow, making the jump to a perpetual system is a smart, strategic move. The accuracy and control it offers are fundamental for scaling up, managing cash flow effectively, and making the kind of informed decisions that actually drive profit. It turns inventory management from a reactive chore into a proactive business tool.
Mastering FIFO, LIFO, and Weighted Average Methods
Once you've decided between a periodic or perpetual inventory system, you've got another crucial choice to make: your inventory valuation method. This isn't just accounting jargon; it directly affects your reported COGS, the value of your remaining inventory, and ultimately, how much tax you pay.
The three main players here are First-In, First-Out (FIFO), Last-In, First-Out (LIFO), and the Weighted Average method. Each one makes a different assumption about how costs flow through your business. This choice can tell a completely different financial story, especially when your inventory costs are on the move.
Understanding First-In, First-Out (FIFO)
The First-In, First-Out (FIFO) method is exactly what it sounds like. It assumes the first items you bought are the first ones you sold. Think about a grocery store managing its milk supply—they always push the oldest cartons to the front to sell them before they expire.
With FIFO, your oldest inventory costs are the first ones to hit your income statement as Cost of Goods Sold. What’s left on your balance sheet is valued at the most recent—and often higher—prices.
Let’s go back to our coffee bean business. Imagine they purchase beans in three separate batches:
- January: 100 bags at $10 each
- February: 100 bags at $12 each
- March: 100 bags at $15 each
If they sell 150 bags, FIFO assumes the first 100 bags sold cost $10 each, and the next 50 bags cost $12 each. This gives you a COGS of $1,600 ($1,000 + $600). The leftover inventory—50 bags from February and all 100 from March—is valued at the most current prices.
A Look at Last-In, First-Out (LIFO)
The Last-In, First-Out (LIFO) method flips FIFO on its head. It assumes the newest items you bought are the first ones out the door. Picture a barrel of nails at a hardware store; customers grab the ones right on top, leaving the older stock sitting at the bottom.
When prices are rising, LIFO can be a smart tax move. You're expensing your newest, most expensive inventory first, which results in a higher COGS. A higher COGS means lower reported profits, which naturally leads to a lower tax bill.
Using our coffee example again, if the business sells 150 bags, LIFO assumes they sold the 100 bags from March ($15 each) and 50 bags from February ($12 each). That calculation gives a much higher COGS of $2,100 ($1,500 + $600). The ending inventory is then made up of the older, cheaper stock, which might not reflect what it would actually cost to replace it today.
A key thing to remember: While LIFO is a powerful tax strategy in the U.S., it's banned under International Financial Reporting Standards (IFRS). If you have any global operations or aspirations, this is a critical detail.
The Balanced Approach of Weighted Average
The Weighted Average Cost (WAC) method finds a happy medium. It smooths out those price fluctuations by calculating a single average cost for all the inventory you have on hand. It's a great fit for businesses selling identical items where it’s just not practical to track the cost of each individual unit.
To get the weighted average, you simply divide the total cost of goods available for sale by the total number of units.
For our coffee business:
- (100 bags * $10) + (100 bags * $12) + (100 bags * $15) = $3,700 total cost
- Total bags available for sale = 300
- Weighted Average Cost per bag = $3,700 / 300 = $12.33
If they sell 150 bags, the COGS is 150 * $12.33, which comes out to $1,850. This number lands right between the FIFO and LIFO results, giving you a more blended valuation that isn't so reactive to price volatility.
The choice between a perpetual and periodic inventory system is the foundation for applying any of these methods. This chart breaks down the key differences.
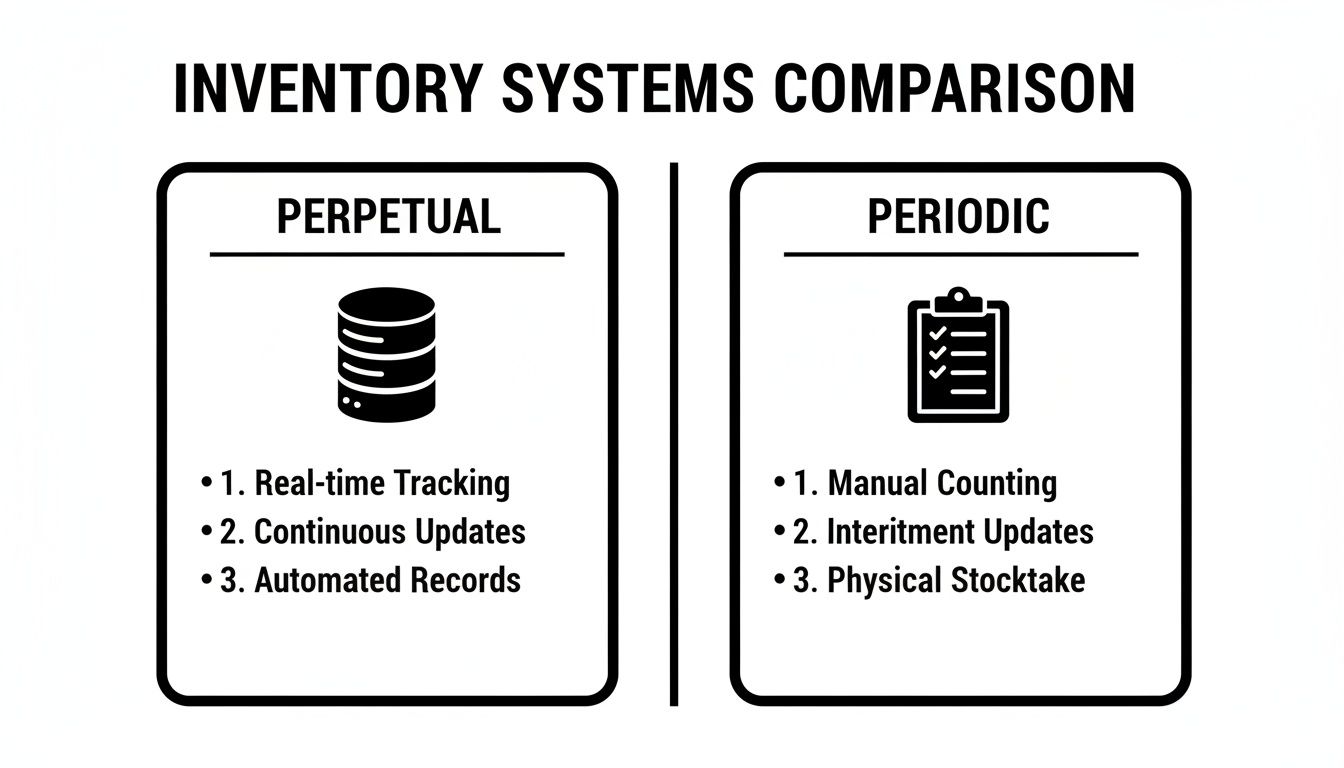
As the visual shows, perpetual systems give you a real-time view, while periodic systems rely on physical counts to figure out what you've sold.
Choosing the Right Method for Your Business
So, which method is best? It really depends on your industry, your financial goals, and your tax situation.
Recent economic shifts have put this decision in the spotlight. With supply chain issues causing global COGS to jump by as much as 18%, the weighted average method has become more popular. It's now used by an estimated 45% of S Corps trying to maintain stable gross margins.
Nailing down your COGS is critical. From 2019-2024, audits showed that accurate tracking helped cut overreported profits by 15% in nearly 70% of audited firms, saving some businesses over $20,000 in penalties. For businesses operating globally, the choice is often made for them; with over 140 countries following IFRS, LIFO is off the table. You can find more analysis of these trends and how they impact reporting on platforms like NetSuite.
Here's a quick look at how these methods stack up, especially when your costs are rising.
Comparison of Inventory Valuation Methods
| Method | Impact on COGS | Impact on Ending Inventory | Best For |
|---|---|---|---|
| FIFO | Lower | Higher (reflects current costs) | Businesses that need an accurate, up-to-date inventory value, like those in food or tech with perishable or fast-evolving products. |
| LIFO | Higher | Lower (based on older costs) | U.S. businesses looking to minimize their taxable income during periods of inflation. |
| Weighted Average | Moderate | Moderate | Businesses with large volumes of identical products or those who want to smooth out the impact of price changes on their financials. |
Whatever you decide, the most important thing is consistency. Once you pick a method, you generally need to stick with it to ensure your financial statements are comparable year after year. Switching methods isn't something you can do on a whim—it usually requires a solid business reason and approval from the IRS. It's a big decision, and one that's best made with some professional advice.
Common COGS Calculation Mistakes to Avoid
Even the sharpest business owners can trip up when calculating the cost of goods sold. And these aren't just little bookkeeping oopsies—they can seriously warp your financial picture, leading to bad business calls and potential headaches with the IRS.
From my own experience, I can tell you that knowing where the common traps are is the best defense. Most of these mistakes boil down to simple confusion over what belongs in the COGS formula. Get this right from day one, and you'll save yourself a world of trouble later on.
Mixing Up Direct and Indirect Costs
I see this one all the time: treating general operating expenses like they're direct production costs. It’s easy to mistakenly lump things like marketing salaries, sales commissions, or the rent for your main office into your COGS calculation.
The key is to remember that COGS should only include costs directly tied to producing your goods.
- Marketing & Sales: The money you spend on Facebook ads or the commissions you pay your sales team are costs of selling the product, not making it. They belong under operating expenses.
- Admin Salaries: The salary for your office manager or bookkeeper supports the entire business operation, not just the production floor.
When you incorrectly include these indirect costs, you bloat your COGS. This makes your business look less profitable than it really is, which is not the impression you want to give a lender or investor.
Fumbling Freight and Shipping Costs
Shipping costs are a notoriously tricky area. How you classify them depends entirely on whether goods are coming or going. You have to get clear on the difference between freight-in and freight-out.
Freight-in is what you pay to get raw materials or products from a supplier to your warehouse. Think of it as part of the journey to get your inventory ready for sale. This cost is absolutely a part of your inventory and gets factored into the "Purchases" line in your COGS formula.
Freight-out, on the other hand, is the cost to ship finished goods to your customers. This is a selling expense, plain and simple. It’s part of your operating costs and should never be mixed into COGS. Confusing the two is a classic blunder that will overstate your Cost of Goods Sold.
Forgetting About Inventory Shrinkage
What your books say you have in stock and what's actually sitting on your shelves can be two different things. Inventory shrinkage is the all-too-common loss of products from things like theft, damage, or spoilage. If you don't account for it, your ending inventory value will be too high.
An overstated ending inventory leads to an understated COGS. This might make your gross profit look great, but it also means you could be overpaying on your income taxes—a painful and unnecessary cash drain.
There's only one way to catch this: regular physical inventory counts. You have to get in there, count everything by hand, and then adjust your books to match reality. This essential step makes sure your COGS is based on what you actually sold, not what you thought you had.
Inconsistent Inventory Valuation Methods
We've already covered how choosing FIFO, LIFO, or Weighted Average can change your COGS and taxable income. The biggest mistake isn’t which one you pick, but flip-flopping between them.
Switching your valuation method every year just to get a better result is a huge red flag for tax authorities. Consistency is king. It ensures your financial reports are stable and comparable from one period to the next. If you have a legitimate business reason to change methods, you generally have to file Form 3115 with the IRS to get approval. Don't chase short-term tax benefits; pick the method that makes sense for your business and stick with it.
Knowing When to Call in the Pros
Figuring out your COGS is a fantastic skill to have in your back pocket. But, let's be honest, there comes a point in every business's journey where DIY accounting starts to hold you back—or worse, becomes a serious risk.
If you're juggling inventory across multiple warehouses, selling on several different platforms, or simply growing faster than you can keep up, those are huge red flags. It’s probably time to get some professional help. The same goes if you're gearing up for an audit or trying to secure funding. You really don't want to be guessing when that much is on the line.
Moving Past the Basic Formula
This is where a good team of CPAs and enrolled agents becomes invaluable. They do more than just crunch the numbers; they help you build a financial strategy.
Think of it this way. A pro can help you with things like:
- Smart Tax Strategy: They’ll look at your inventory methods and make sure you're set up to legally pay the least amount of tax possible.
- Audit-Proofing Your Books: Keeping everything clean and by the book so an IRS letter doesn't send you into a panic.
- Boosting Your Bottom Line: They can often spot inefficiencies in how you manage inventory, helping you tighten things up and improve your gross profit margin.
Getting COGS right isn't just about paperwork. It's the bedrock of your financial statements. A mistake here can throw off your profitability, lead you to make bad decisions based on bad data, and even land you with some nasty tax penalties.
At the end of the day, hiring an accountant isn't just another expense. It's an investment in your company's stability and future. They make sure your finances are solid today and are built to handle the growth you're working so hard for.
If any of this sounds familiar, it might be time for a chat.
Answering Your Top COGS Questions
As you dig into the details of COGS, you'll naturally run into some common questions, especially around taxes and operations. Getting these nuances right is crucial for keeping your financial records accurate and strategic.
How Does COGS Affect My Business Taxes?
Think of your COGS calculation as a direct lever on your tax bill. When you subtract COGS from your revenue, you're left with your gross profit. This is a foundational number on your tax return; everything else gets subtracted from there to find your final taxable income.
The bottom line is that a higher COGS means a lower gross profit, which in turn leads to a smaller taxable income. This is exactly why your choice of inventory method, like using LIFO during a period of rising prices, can be such a powerful tax-planning tool. It legally adjusts what you owe.
Can I Change My Inventory Valuation Method?
You can, but it’s not something you can do on a whim. The IRS puts a high value on consistency. If you want to switch from FIFO to LIFO, for instance, you'll need a solid business reason that goes beyond just wanting to pay less tax for one year.
To make the switch official, you have to file Form 3115, Application for Change in Accounting Method. It’s a formal process, but it’s there to make sure your financial reporting remains transparent and comparable from one year to the next.
Is Labor Cost Included in COGS?
This is a great question, and the answer is: it depends on the type of labor.
Direct labor is definitely part of COGS. These are the wages you pay to the people physically making your products. If you build custom furniture, the salary you pay your woodworker is direct labor.
On the other hand, indirect labor is not. This includes salaries for your sales manager or administrative staff. They are essential to running the business, but they aren't directly involved in creating the product itself, so their pay is considered an operating expense.
What Is the Difference Between COGS and Operating Expenses?
The distinction is pretty straightforward once you get the hang of it. COGS is about the cost of making your product, while operating expenses (OpEx) are the costs of running your business.
- COGS includes: Raw materials, direct labor, and factory overhead.
- Operating Expenses include: Marketing campaigns, rent for the main office, and administrative salaries.
Keeping these two categories separate is non-negotiable for accurate books. It ensures your gross profit is a true measure of your production efficiency and gives you a much clearer picture of your company's core financial health.
At Allied Tax Advisors, we field these kinds of questions every day. We help business owners make sense of the complexities, ensuring their bookkeeping is clean and their tax strategy is built to last. Let us handle the details so you can get back to growing your business. Find out how we can help at https://alliedtax.com.