
At its core, calculating net income is straightforward: you take your total revenue and subtract all your total expenses. For a business, that means deducting everything from materials and salaries to interest and taxes. For you and me, it's our gross pay minus taxes and other deductions.
This final number isn't just a number—it’s the clearest, most honest measure of financial health.
What Net Income Really Means for You

You'll often hear net income called the "bottom line," and for good reason. It’s what's truly left in the pot after every single cost has been paid. It’s the ultimate reality check on profitability for a business or financial stability for an individual. Think of it as the final, most important chapter in your financial story for any given period.
From a business perspective, this figure is the profit you walk away with after subtracting every conceivable expense from your total sales. This goes way beyond just the cost of goods sold. We're talking about everything: employee salaries, marketing campaigns, rent for your office, interest payments on loans, and of course, corporate taxes.
On a personal level, your net income is simply your take-home pay. It’s the actual cash you have to work with—money you can spend, save, or invest after all deductions are siphoned off your gross salary. These deductions typically include federal and state taxes, retirement contributions like a 401(k), and health insurance premiums.
Why This Calculation Matters So Much
Getting a handle on how to calculate net income is far more than just a bookkeeping chore; it's a fundamental skill for making smarter financial moves. When you have a firm grasp of your net income, you're empowered to accurately assess performance and plan for the future with real confidence.
Knowing this number helps you:
- Gauge True Profitability: It answers the most basic question: Is my business actually making money after all the bills are paid?
- Create Realistic Budgets: Whether you're planning for your household or your company, net income is the only starting point for a budget that works.
- Secure Financing: Banks, lenders, and investors all zoom in on net income. It’s a key metric they use to evaluate financial health and risk before they’ll even consider approving a loan or cutting a check.
- Spot Cost-Saving Opportunities: Breaking down all your expenses forces you to see exactly where your money is going, making it much easier to identify areas where you can trim the fat.
The simple formula, Net Income = Revenue – Expenses, is powerful because it cuts through all the noise. It gives you the unvarnished truth about your financial performance.
In the end, it doesn't matter if you're a small business owner poring over quarterly reports or just trying to manage your monthly household expenses. Your net income is the number that truly counts. It gives you a factual basis for strategic planning, helping you shift from just guessing about your finances to genuinely understanding them. And that clarity is the first real step toward achieving any long-term financial goal.
Gathering the Right Financial Data

Before you can crunch a single number, you have to get your data in order. This is non-negotiable. Trying to calculate net income without accurate financial information is like trying to bake a cake without measuring the ingredients—you'll get a result, but it probably won't be the one you want.
The quality of your final number hinges entirely on the quality of the data you start with. So, let’s talk about where to find it.
For a business, your go-to document is the income statement, which you might also know as the profit and loss (P&L) statement. This report is your roadmap, laying out every figure you’ll need in a clear, organized way. Learning how to properly analyze financial statements is a skill that pays dividends long after you've calculated net income.
To help you get organized, here’s a quick checklist of the data points you'll need and where you can typically find them, whether you're looking at your business or personal finances.
Required Data for Net Income Calculation
| Data Point | Business Source Document | Personal Source Document |
|---|---|---|
| Total Revenue/Income | Income Statement, Sales Ledgers | Pay Stubs, W-2s, 1099s |
| Cost of Goods Sold (COGS) | Income Statement, Inventory Records | N/A |
| Operating Expenses | Income Statement, Expense Reports | Bank Statements, Budgeting Apps |
| Interest Expense | Income Statement, Loan Statements | Loan Statements, Credit Card Bills |
| Taxes | Income Statement, Tax Filings | Pay Stubs, W-2s |
| Other Income/Losses | Income Statement | Investment Statements |
Having this information ready to go makes the calculation itself much more straightforward.
Essential Business Documents and Data
When you're pulling numbers for your business, your goal is precision. You’re looking for specific line items from your accounting records, not just ballpark figures.
If your bookkeeping is a mess, this step can be a real headache. A good system for tracking your numbers makes all the difference. Our guide on how to track business expenses is a great place to start if you need to get organized.
Here's the data you’ll need to hunt down:
- Total Revenue: This is your "top line." It’s every dollar your business earned from sales before a single expense is taken out.
- Cost of Goods Sold (COGS): Think direct costs. This includes the raw materials and labor needed to create the product or service you sell.
- Operating Expenses: This bucket holds everything else it costs to keep the lights on—rent, utilities, salaries for your administrative staff, marketing, and so on.
- Interest Expense: If you have business loans or a line of credit, this is the interest you've paid on that debt.
- Taxes: This is the amount set aside for corporate income taxes at the federal, state, and local levels.
Key Personal Financial Information
Calculating your personal net income follows the same logic, just with different source documents. You’ll start with your total earnings and subtract all the deductions that chip away at it.
Your most powerful tool here is your pay stub. It’s the personal equivalent of a P&L statement, breaking down exactly where your money goes between your gross pay and your take-home pay.
Your pay stub is the personal equivalent of a business's income statement. It provides a clear, itemized list of all the deductions that transform your gross pay into your actual take-home pay.
Look for these specific items on your pay stubs, W-2s, and any investment statements you have:
- Gross Pay: The total salary or wages you earned before anything was taken out.
- Investment Income: Don't forget earnings from other sources, like stock dividends, bank interest, or capital gains.
- Pre-Tax Deductions: This includes contributions to retirement accounts like a 401(k), a health savings account (HSA), or a flexible spending account (FSA).
- Statutory Deductions: These are the mandatory taxes—federal and state income tax, plus Social Security and Medicare (FICA).
- Post-Tax Deductions: These are costs that come out after taxes are calculated, like health insurance premiums or union dues.
Gathering this information methodically is the most important step. It prevents the classic "garbage in, garbage out" problem and ensures the final net income figure you calculate is one you can actually trust.
Calculating Your Business Net Income
Let's get practical and walk through how this all works in the real world. Figuring out net income for a business isn't just about punching numbers into a calculator; it's a process that tells the financial story of your company, showing you exactly where every dollar is going.
To make this tangible, we’ll follow the finances of a small, independent coffee shop we'll call "Morning Brew." By breaking the calculation down into manageable chunks, we can turn a simple formula into a genuinely powerful strategic tool.
From Total Sales to Gross Profit
Our first stop is calculating Gross Profit. Think of this as the money your business makes purely from selling its products, before you even consider rent, salaries, or other overhead. It’s a gut check on your core profitability.
Here’s the breakdown for Morning Brew’s last quarter:
- Total Revenue: They brought in $50,000 from selling coffee, pastries, and a bit of merchandise.
- Cost of Goods Sold (COGS): The direct costs to make and sell those items—coffee beans, milk, flour, sugar, paper cups—came out to $15,000.
To get the gross profit, you just subtract COGS from your total sales:
$50,000 (Revenue) – $15,000 (COGS) = $35,000 (Gross Profit)
That $35,000 looks pretty good, but it's just the starting point. It confirms the products themselves are profitable, but now we have to account for everything else it takes to run the business.
Deducting Operating and Non-Operating Expenses
Next, we start subtracting all the other costs required to keep the lights on and the doors open. This is where we get a clear picture of both the daily operational costs and other financial obligations the business has.
This is where you tally up everything from rent to loan payments.
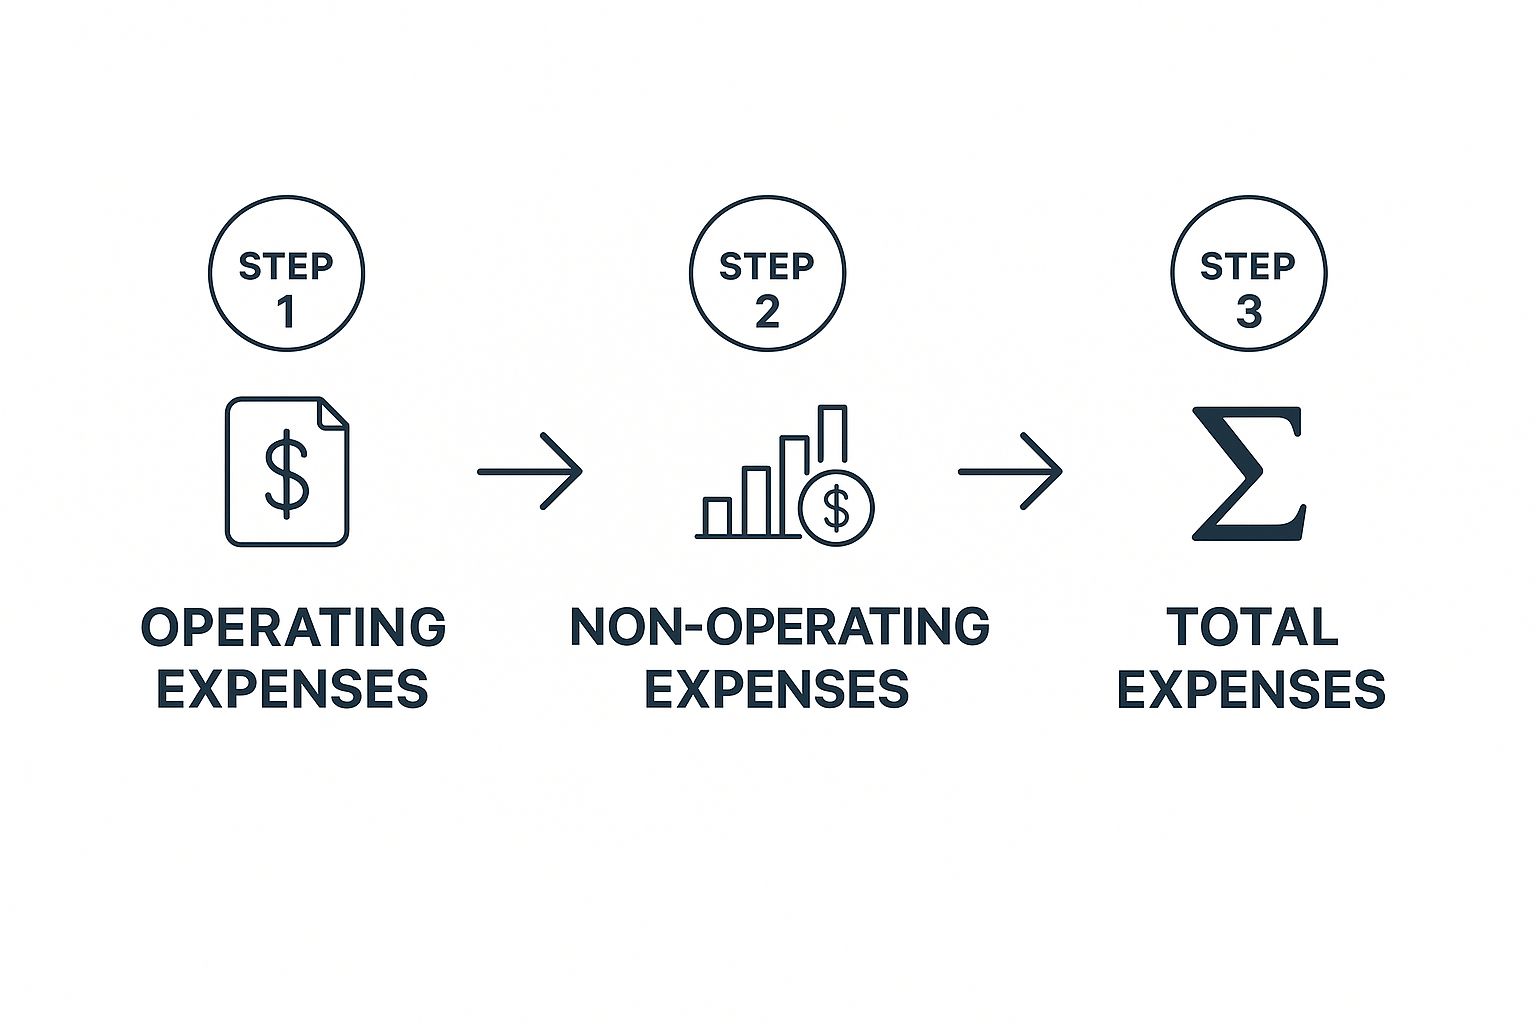
For Morning Brew, the other expenses look like this:
- Operating Expenses: This bucket is for the day-to-day running of the shop. It includes rent for the storefront ($6,000), employee salaries and wages ($12,000), utilities ($1,500), and marketing costs ($1,000). That’s a total of $20,500.
- Interest Expense: The shop has a small business loan, and the interest paid last quarter was $500.
For some businesses, especially in real estate, understanding Net Operating Income (NOI) is a crucial related metric. But for our coffee shop, we'll stick to the main path. Now, we find its Earnings Before Tax (EBT) by subtracting these expenses from the Gross Profit.
$35,000 (Gross Profit) – $20,500 (Operating Expenses) – $500 (Interest) = $14,000 (EBT)
The shop’s Earnings Before Tax (EBT) is $14,000. This is a critical milestone because it shows how profitable the business is from its operations, right before the government takes its share.
The Final Step: Taxes and the Bottom Line
We're almost there. The last piece of the puzzle is to subtract income taxes. This final deduction reveals the true "bottom line"—the profit the owner can actually reinvest, save, or take home.
After all that work, the formula is surprisingly simple: Net Income = Earnings Before Tax (EBT) – Income Tax.
Let's assume Morning Brew's effective tax rate means they owe $3,000 for the quarter.
$14,000 (EBT) – $3,000 (Taxes) = $11,000 (Net Income)
So, Morning Brew’s net income is $11,000. This step-by-step process is also a great illustration of why the https://alliedtax.com/difference-between-cash-basis-and-accrual-basis/ matters so much—it dictates exactly when you record these revenues and expenses, which can really change the picture from one period to the next.
Finding Your Personal Net Income

Now, let's bring this concept home—literally. Calculating your personal net income follows the same logic as it does for a business, but instead of tracking profits, you're figuring out your actual take-home pay. This is the money you truly have to work with for budgeting, saving, and everything else.
Getting a firm handle on this number is the bedrock of any solid financial plan. It lets you build a realistic budget that actually works and set savings goals you can hit without stress. To make this crystal clear, let's walk through a common scenario.
A Real-World Example
Imagine you just landed a new job with a great annual salary: $75,000. That's the big number on the offer letter, but it's not what will show up in your bank account every payday.
First, let's break that down to a monthly figure. Your gross monthly income is $6,250 (that's just $75,000 divided by 12). From there, we have to start subtracting all the things that come out before you see a dime.
Here are the usual suspects you’ll see on a pay stub:
- Federal and State Income Taxes: These are almost always the biggest chunk. The exact amount depends on your income bracket, where you live, and your filing status.
- FICA Taxes: This isn't optional. It’s a mandatory payroll tax that covers Social Security (6.2%) and Medicare (1.45%).
- 401(k) Contributions: If you’re putting money into a retirement plan at work, those pre-tax contributions come out here, which cleverly lowers your taxable income.
- Health Insurance Premiums: Your share of the cost for medical, dental, or vision insurance is also typically deducted straight from your paycheck.
Knowing your net income transforms budgeting from a guessing game into a precise plan. It's the only number that gives you a true picture of your disposable income and financial capacity.
So, let's attach some real numbers to our $6,250 gross monthly salary. A typical set of deductions might look like this:
- Federal Income Tax: $750
- State Income Tax: $300
- FICA (Social Security & Medicare): $478
- 401(k) Contribution (5%): $312
- Health Insurance Premium: $150
If you add all those up, the total monthly deductions come out to $1,990.
Calculating Your True Take-Home Pay
Once you have all the deductions tallied, the final step is simple subtraction. We just take that gross monthly pay and subtract the total deductions to get your net monthly income—your actual take-home pay.
Here's the math for our example:
$6,250 (Gross Monthly Pay) – $1,990 (Total Deductions) = $4,260 (Net Monthly Income)
So, even with a $75,000 salary, the money you can actually spend or save each year is closer to $51,120. This difference is huge, and understanding why is key to managing your finances. It’s also closely related to other important tax figures, like what is adjusted gross income (AGI), which you’ll see on your tax return.
Walking through this exercise demystifies your paycheck and gives you the clarity you need to manage your money with confidence.
Using Net Income to Forecast Your Future
Calculating your net income isn't just about looking in the rearview mirror. Think of it less as a final report card and more as a crystal ball. By digging into your past performance, you can turn a simple income statement into a powerful tool for planning your next move, building a smarter budget, and setting growth targets you can actually hit.
This is how you move from reacting to what’s already happened to proactively shaping what comes next. It’s the difference between guessing and knowing, and it’s how sharp businesses and financially savvy people build a roadmap for the future.
Projecting Future Performance with Ratios
So, how do you actually do this? One of the most straightforward methods is the 'percent of sales' model. The core idea is simple: many of your key expenses will likely stay at a consistent percentage of your revenue as your business scales up or down.
Let's imagine your marketing costs have reliably hovered around 5% of your total sales for the past couple of years. If you're aiming for a 10% jump in sales next year, it's a safe bet that your marketing budget will need a similar boost to make that happen.
This logic extends to other crucial parts of your budget. The percent of sales method often assumes that your Cost of Goods Sold (COGS) will track a fixed percentage of sales. By keeping assumptions like your tax rate constant, you can get a surprisingly accurate estimate of future net income based on projected earnings. If you want to go deeper, Harvard Business School has a great overview of these financial forecasting methods.
Once you understand these historical relationships, you can build a financial model that breathes. It allows you to play out different scenarios and see how a change in one area—like a planned sales push—sends ripples all the way down to your bottom line.
Turning Forecasts into Actionable Plans
With a solid forecast in hand, you can stop building your budget based on last year's numbers. Instead, you can start allocating money and resources with purpose, directly tied to your growth goals and expected costs.
Here’s what that looks like in the real world:
- Set Attainable Growth Targets: If your forecast points to modest net income growth, you know that a massive expansion plan might need more capital or a longer runway.
- Budget with Precision: Does your projection show COGS chewing up too much of your profit? Now you have a reason to get on the phone with suppliers and negotiate better rates before it becomes a problem.
- Secure Financing with Confidence: Walking into a lender's office with a detailed forecast backed by years of data is a game-changer. It shows you've done your homework and makes a much more compelling case for that loan.
This forward-looking mindset is what separates businesses that just get by from those that truly thrive. It's about shifting from merely reporting on the past to strategically planning for the future, giving you the clarity to steer your finances toward lasting success.
Common Questions About Net Income
Once you've crunched the numbers, you might still have some lingering questions about what net income really means in practice. It's one of those terms that seems simple on the surface, but the details matter for making smart financial decisions.
Let's walk through a few of the most common questions I get from clients.
Gross Profit vs Net Income What Is the Real Difference
It’s incredibly common to mix these two up, but they tell you completely different things about your business's health.
Think of Gross Profit as the first big-picture check. It’s simply your total revenue minus the direct costs of what you sell (your Cost of Goods Sold, or COGS). This number answers a fundamental question: "Is there money to be made from my core product or service?"
Net Income, on the other hand, is the final, no-nonsense verdict. It takes your gross profit and then subtracts everything else—rent, marketing, salaries, interest on loans, taxes, you name it. It answers the most important question of all: "After every single bill is paid, is this business actually making money?"
Gross profit tells you if your core business idea works. Net income tells you if your entire company is built to last. You really can't get the full story with just one of them.
What Does a Negative Net Income Mean
When your total expenses for a period add up to more than your total revenue, you'll see a negative net income on your P&L. In accounting terms, this is called a net loss.
Now, seeing a number in parentheses isn't always a cause for panic. A net loss doesn't automatically mean the business is doomed. Many startups, especially in tech or biotech, intentionally run at a loss for years. They're pouring money into R&D or aggressive marketing to grab a foothold in the market, betting on huge profits down the road.
However, if a net loss becomes a recurring theme, it's a serious warning sign. It suggests the business model isn't working as it should. Maybe your prices are too low, your operating costs are out of control, or you're crushed by debt. For any potential investor or lender, a history of net losses is a major red flag signaling high financial risk.
How Do Non-Cash Expenses Like Depreciation Affect Net Income
This is where things can get a little tricky, but it's a crucial concept to grasp. Depreciation is an accounting tool that lets you spread the cost of a big-ticket physical asset—like a delivery truck or a piece of manufacturing equipment—over its expected lifespan. You might pay for it all at once, but you don't expense it all at once.
Instead, a portion of its value is deducted on your income statement each year. We call this a non-cash expense because no actual cash is leaving your account when you record it; the money is already gone.
So, why bother? Because depreciation reduces your company's taxable income. A lower profit on paper means a lower tax bill. By including these non-cash expenses, the net income calculation gives a truer, more standardized picture of profitability, even though it doesn't perfectly match the cash flowing in and out of your bank.
At Allied Tax Advisors, we help individuals and businesses move beyond the numbers to find real clarity and confidence in their financial journey. If you need expert guidance on your taxes or accounting, we’re here to help. Visit us at https://alliedtax.com to learn more.