
At first glance, figuring out how to calculate self employment tax can feel intimidating. But once you break it down, the formula is actually pretty simple: take your net earnings, multiply that by 92.35%, and then multiply the result by 15.3%.
This two-step process covers both the Social Security and Medicare taxes you're responsible for as a freelancer or business owner. Let's walk through exactly how it works.
Understanding the Self Employment Tax Formula

When you work for yourself, you're wearing two hats at tax time: you're both the employee and the employer. That means you're on the hook for both portions of Social Security and Medicare taxes, which are collectively known as FICA taxes.
This combined responsibility adds up to the self-employment tax. The total rate is 15.3%, but here's the key thing to remember: you don't apply it to your entire business profit.
The Initial Adjustment: Why 92.35%?
The very first thing you do is multiply your net earnings from self-employment by 92.35% (or 0.9235). This might seem like a random number, but it’s a crucial adjustment from the IRS.
This step essentially gives you a deduction for the "employer's share" of your Social Security and Medicare taxes. It's designed to level the playing field, making sure you aren't taxed on the half of FICA taxes that a traditional employer would have paid on your behalf.
Let’s say your net earnings for the year were $60,000. You wouldn't calculate the tax on that full amount. Instead, your taxable base would be:
$60,000 x 0.9235 = $55,410
This lower number, $55,410, is what you'll use to figure out your actual self-employment tax bill. It's a small but significant step that directly reduces how much you owe, so don't skip it.
Breaking Down the 15.3% Tax Rate
That 15.3% rate isn't just one big tax; it’s actually two separate taxes combined to fund essential government programs. When you calculate your self-employment tax, you're really paying into two different buckets.
Here is a closer look at what makes up the self-employment tax rate.
Self Employment Tax Rate Breakdown
| Tax Component | Tax Rate | What It Covers |
|---|---|---|
| Social Security | 12.4% | This portion funds retirement, disability, and survivor benefits. It only applies up to a certain income limit each year. |
| Medicare | 2.9% | This funds hospital insurance for seniors and some individuals with disabilities. There is no income limit on this tax. |
| Total Rate | 15.3% | The combined rate applied to 92.35% of your net self-employment earnings. |
Understanding this split is helpful, especially when you consider the income caps. The 12.4% Social Security tax only applies up to an annual income limit, which the government adjusts almost every year. In contrast, the 2.9% Medicare tax applies to all of your net earnings, no matter how high they are.
For a deeper dive, you can find more great information on the components of self-employment tax on hrblock.com.
Key Takeaway: The self-employment tax formula is built to mirror the FICA taxes paid in a traditional job. By first reducing your net earnings by 7.65% (which is what multiplying by 92.35% accomplishes), the system creates a more equitable tax base before applying the full 15.3% rate.
Pinpointing Your Net Earnings From Self-Employment
Before you even think about the self-employment tax formula, there's one number you absolutely have to nail down: your net earnings. This is the bedrock of your tax calculation. It's not your total revenue; it’s what's left over after you've subtracted all your legitimate business expenses.
It’s a classic rookie mistake for freelancers to focus solely on the money coming in. But if you want to lower your tax bill, the real magic happens when you meticulously track every penny going out. We're not just talking about big-ticket items, but all the small, day-to-day costs of keeping your business running.
To get this number right, many self-employed pros turn to reliable bookkeeping services to keep their finances in order. It's a smart way to make sure you don't miss a single deduction you're entitled to.
Moving Beyond The Obvious Deductions
When people start tracking expenses, they usually remember the easy stuff—a new laptop, office supplies, maybe some marketing costs. The real savings, though, are hiding in the details that most entrepreneurs forget. You have to think about all the small, recurring costs that pile up over the year.
Here are some of the most common—and commonly overlooked—deductions:
- Software and Subscriptions: That project management tool, your cloud storage plan, or the industry-specific software you pay for every month? All business expenses.
- Professional Development: Did you attend a conference, take an online course, or buy books to sharpen your skills? Deductible.
- Business-Use Portion of Utilities: You can deduct a percentage of your home internet and phone bills based on how much you rely on them for work.
- Bank Fees: Those monthly service charges on your business bank account? Those count, too.
Every one of these deductions chips away at your net earnings, which directly reduces the amount you’ll owe in self-employment tax. Tracking them isn't just about good habits; it's a core financial strategy.
Expert Tip: Open a separate bank account and get a dedicated credit card just for your business. This is the single best piece of advice I can give. It makes tracking expenses a thousand times easier and gives you a clean paper trail if the IRS ever comes knocking.
If you want to dive deeper into this crucial first step, our complete guide on https://alliedtax.com/how-to-calculate-net-income/ offers a more detailed breakdown. Getting this number right is non-negotiable before you start any tax math. Diligent records are your best friend here—they ensure you only pay tax on your actual profit.
Let's Do the Math: A Real-World Self-Employment Tax Calculation
Okay, theory is one thing, but let's get our hands dirty and see how this works in the real world. Nothing builds confidence like walking through the numbers step-by-step.
Imagine a freelance graphic designer who had a great year and pulled in $80,000 in net earnings. This isn't her gross revenue; it's her profit after she’s already deducted all her business expenses like software, marketing, and home office costs.
First, Find Your Actual Taxable Income
Here’s a crucial step that many people miss: you don't pay self-employment tax on the full $80,000. The IRS knows that as both the "employer" and "employee," you're paying both halves of FICA. So, they let you take a small deduction first.
This is where that 92.35% (or 0.9235) figure comes into play. You multiply your net earnings by this number to find the amount that's actually subject to the tax.
For our designer, it looks like this:
$80,000 (Net Earnings) x 0.9235 = $73,880
So, $73,880 is the magic number. This is the taxable base we'll use for the rest of the calculation and what gets reported on your Schedule SE (Form 1040). That one simple multiplication just lowered her tax bill.
The image below lays out this exact process visually, taking you from your starting profit to your final tax amount.
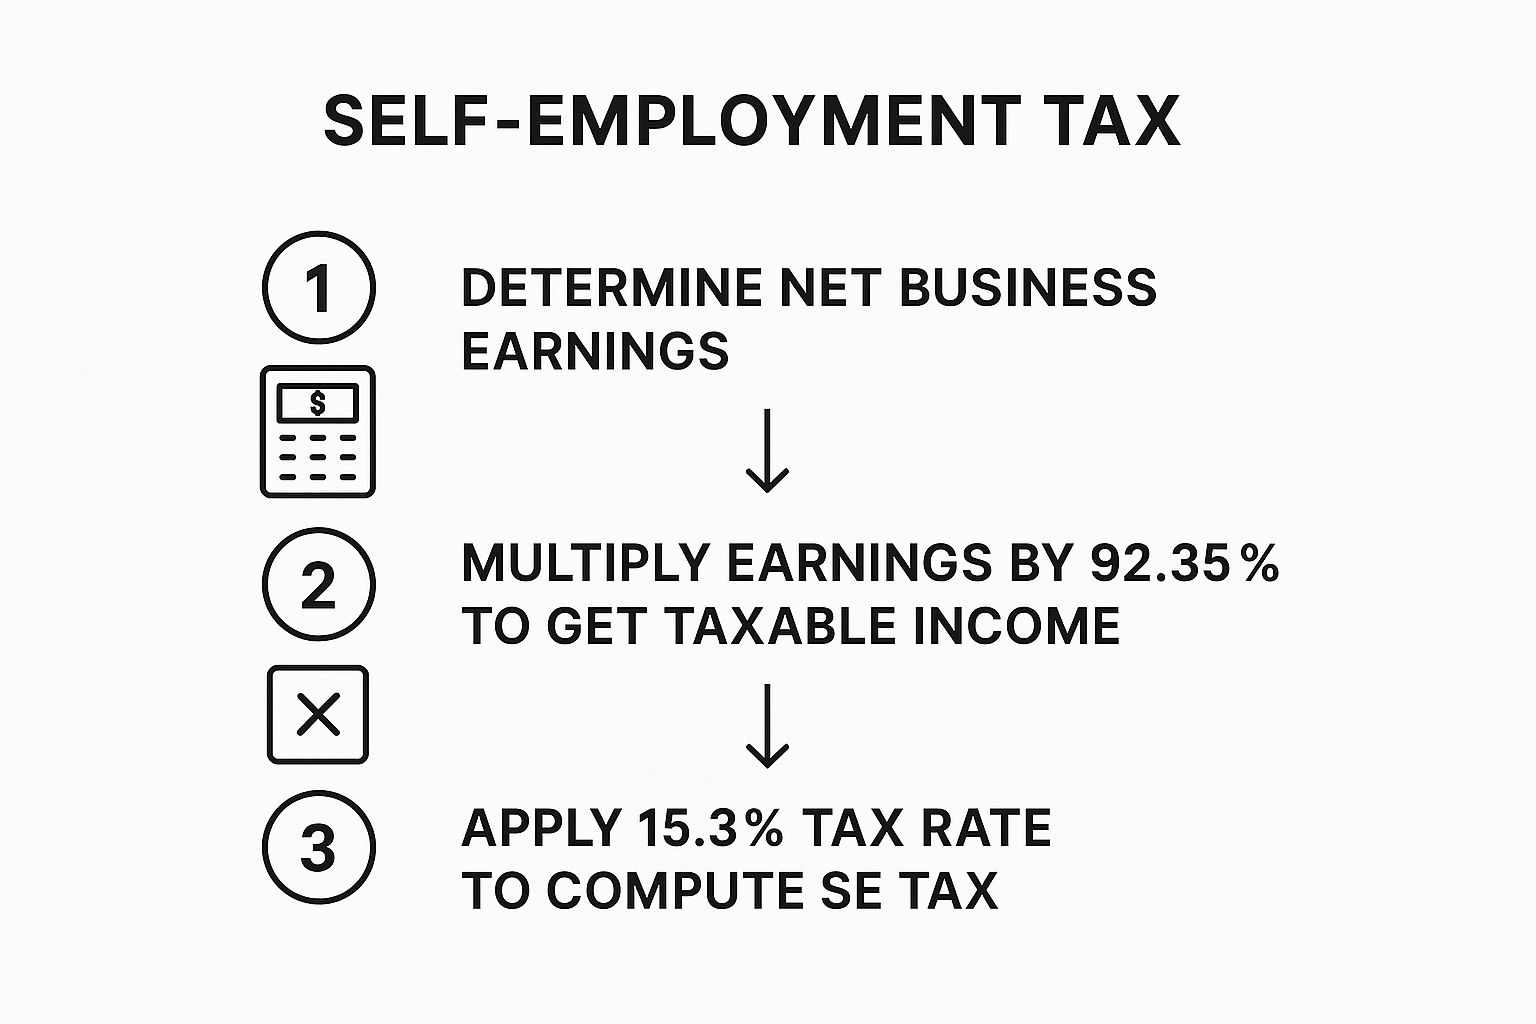
As you can see, it's a logical flow designed to make sure you're not paying tax on more than you have to.
Next, Apply the Social Security and Medicare Rates
With our taxable base of $73,880, we can now figure out the two parts of the self-employment tax: Social Security and Medicare. I always find it's easier to calculate them separately to see exactly where your money is going.
-
Social Security Tax: The rate is 12.4%. For our designer, this comes out to:
$73,880 x 0.124 = $9,161.12 -
Medicare Tax: The rate for this is 2.9%. The math here is:
$73,880 x 0.029 = $2,142.52
Breaking it down like this demystifies the combined 15.3% rate and shows you precisely how much you're contributing to each program—one for retirement and disability benefits, the other for hospital insurance.
A common mistake I see is people applying the 15.3% rate directly to their total profit. Don't do it! You must multiply by 92.35% first. Skipping that simple step means you're calculating your tax on an inflated number and will definitely overpay.
Finally, Tally It All Up
The last step is the easiest. Just add the two tax amounts together to find the total self-employment tax due for the year. This is the final number that goes onto her tax return.
- Total Self-Employment Tax:
- $9,161.12 (Social Security)
- + $2,142.52 (Medicare)
- = $11,303.64 (Total SE Tax Due)
There you have it. On her $80,000 of net freelance income, our graphic designer owes a total of $11,303.64 in self-employment tax. This is her contribution to the Social Security and Medicare systems as a business owner.
What Happens When You're a High Earner?

As your freelance business or consultancy takes off, your income grows—and so does the complexity of your tax situation. That standard 15.3% self-employment tax rate isn't a flat tax that applies to every single dollar you earn, especially once your income starts to climb. Two critical thresholds kick in for high earners, and they can dramatically change your final tax bill.
Getting these rules right is a huge part of learning how to calculate self employment tax accurately. If you miss them, you could be in for a nasty surprise, either by overpaying the IRS or, even worse, underpaying and getting hit with penalties down the road.
Let's break down exactly what changes when your earnings are on the rise.
The Social Security Wage Base Limit
The first major rule you need to know about is the Social Security wage base limit. Think of it as an income cap set by the Social Security Administration every year. Once your net self-employment earnings go past this number, you stop paying the hefty 12.4% Social Security part of the SE tax.
For the 2024 tax year, that magic number is $168,600.
So, any income you earn above $168,600 is completely exempt from the Social Security tax. But—and this is a big but—the 2.9% Medicare tax doesn't have an income limit. You pay that on all of your net earnings, no matter how high they go. For more details on this, you can check out the current self-employment tax thresholds on smartasset.com.
This provides some nice tax relief for high earners, but it means you have to be meticulous with your calculations to get it right.
The Additional Medicare Tax Surtax
It's a classic case of the IRS giving with one hand and taking with the other. Just as one tax component disappears, a new one can pop up. Enter the Additional Medicare Tax, a 0.9% surtax that applies to earnings over certain high-income thresholds.
This extra tax was introduced as part of the Affordable Care Act and is aimed squarely at higher earners. The income level where it kicks in depends on your filing status:
- Married filing jointly: $250,000
- Single or Head of Household: $200,000
- Married filing separately: $125,000
Crucially, this 0.9% is on top of the standard 2.9% Medicare tax you're already paying on all your earnings. It's also worth remembering that high-income situations can trigger other tricky tax rules. For instance, it might be a good idea to understand the Alternative Minimum Tax in our detailed guide to see if that could affect you.
Let's walk through an example: Imagine a consultant who is a single filer and has $220,000 in net self-employment earnings.
- They would pay the 12.4% Social Security tax on the first $168,600.
- They would pay the standard 2.9% Medicare tax on their entire $220,000.
- On top of that, they'd owe the 0.9% Additional Medicare Tax on the $20,000 that exceeds the $200,000 single-filer threshold.
Smart Strategies to Lower Your Tax Bill
Knowing how to calculate your self-employment tax is one thing, but figuring out how to legally and strategically shrink that number is where you really win. It’s not just about tracking expenses; it's about being proactive with financial moves built right into the tax code for savvy entrepreneurs.
One of the smartest moves you can make is to plan for retirement. When you contribute to specific retirement accounts designed for the self-employed, you create an immediate and significant tax deduction.
Maximize Your Retirement Contributions
Putting money into a SEP IRA or a Solo 401(k) isn't just for your future—it pays off right now. These contributions are deducted directly from your income, which pulls double duty by lowering both your income tax and your self-employment tax.
For 2024, you can contribute up to 25% of your net adjusted self-employment income, with a maximum contribution of $69,000. This dual benefit makes it one of the most powerful tax-saving tools you have.
Think about a freelancer who netted $100,000 this year. If they put $20,000 into their SEP IRA, they could save thousands in taxes for the current year, all while building a solid nest egg for the future.
Another major area to find savings is with health-related deductions. If you pay for your own health insurance, you’re in luck. The self-employed health insurance deduction lets you write off 100% of the premiums paid for medical, dental, and even long-term care insurance for you, your spouse, and your dependents.
Key Insight: This isn't your standard medical expense deduction. The self-employed health insurance deduction is an "above-the-line" deduction, meaning it directly reduces your Adjusted Gross Income (AGI). This makes it far more impactful and much easier to claim.
Leverage Powerful Business Deductions
Beyond retirement and health insurance, a few other key deductions can make a huge dent in your tax bill. Understanding how they work is critical for getting an accurate tax number.
-
The Qualified Business Income (QBI) Deduction: This is a big one. It allows many pass-through businesses—like sole proprietorships and LLCs—to deduct up to 20% of their qualified business income. There are some income limits and specific rules depending on your industry, but it’s a deduction you absolutely can't afford to ignore.
-
Deducting Half of Your SE Tax: Here’s a deduction every single self-employed person can take. You get to deduct one-half of what you pay in self-employment taxes from your gross income. This adjustment lowers your AGI, which in turn reduces your overall income tax liability. Your tax software or accountant will calculate this automatically, but it's good to know why that number is being adjusted.
There are dozens of potential write-offs out there. To make sure you haven't missed anything, dive into this comprehensive 1099 tax deductions list and claim every dollar you’re entitled to.
When you combine these strategies, filing taxes stops being a reactive chore and becomes part of a smart, proactive financial plan.
Got More Questions? Let’s Tackle Some Common Scenarios
Once you get the hang of the basic formula, you’ll find it’s not so bad. But freelancing is rarely that simple, and real-life situations often throw a wrench in the works. Let's walk through a few of the questions that pop up most often.
What if I Have a W-2 Job and a Side Hustle?
This is probably one of the most common situations we see. Juggling a day job and freelance work can feel complicated, but when it comes to self-employment tax, it can sometimes work to your advantage.
Here's why: your W-2 employer is already handling Social Security taxes on your salary. The IRS only requires you to pay Social Security tax up to an annual income limit. For 2024, that cap is $168,600.
So, if your salary from your W-2 job is already over that $168,600 threshold, you’ve already maxed out your Social Security contribution for the year. That means you won't owe any more Social Security tax on your freelance income. You’re not completely off the hook, though—you’ll still owe the full 2.9% Medicare tax on every single dollar of your self-employment profit.
Why Do I Have to Pay Taxes Four Times a Year?
Ah, the dreaded quarterly payments. The reason for this comes down to how the U.S. tax system is designed. It's a "pay-as-you-go" system. For W-2 employees, this happens automatically through paycheck withholdings. For us, it means making estimated tax payments using Form 1040-ES.
If you just wait until Tax Day in April to settle up for the entire previous year, the IRS will likely hit you with an underpayment penalty. It's their way of making sure you're paying your share throughout the year, not all at once. Think of it as breaking your big annual tax bill into smaller, more manageable payments.
Mark your calendar for these deadlines:
- April 15 (for income earned Jan 1 – Mar 31)
- June 15 (for income earned Apr 1 – May 31)
- September 15 (for income earned Jun 1 – Aug 31)
- January 15 of the following year (for income earned Sep 1 – Dec 31)
A Quick Tip from Experience: Open a separate, high-yield savings account just for your taxes. Every time a client pays you, immediately move 25-30% of that payment into your tax account. When quarterly deadlines roll around, the money is just sitting there waiting for you. No stress, no scrambling.
What Happens if My Business Loses Money?
It happens. Not every year is a banner year, and sometimes your expenses just end up being higher than your income. If your business has a net loss, the tax implications are actually pretty simple.
No profit means no self-employment tax. If you have zero net earnings from self-employment, you owe zero self-employment tax for that year.
But there’s a silver lining. That loss doesn't just vanish. It becomes a net operating loss (NOL), which you can often carry forward to future years. This allows you to use the loss from a tough year to reduce your taxable profit in a more successful year, which ultimately lowers your tax bill down the road.
Feeling your way through the world of self-employment taxes can be tricky, but you don't have to figure it all out on your own. The experts at Allied Tax Advisors specialize in creating personalized tax and accounting strategies to help you reach your financial goals. Learn more about our services and get your taxes under control today.