
Running payroll for your small business boils down to a few core responsibilities: collecting the right employee tax forms, deciding on a pay schedule, calculating pay and taxes, and then actually paying your people and the government. It’s a recurring cycle of gathering data, running the numbers, and staying compliant. Get this right, and you’ll keep your team happy and the tax authorities off your back.
Getting Started With Small Business Payroll
For most small business owners, tackling payroll for the first time feels like a huge leap. You’re suddenly dealing with a jumble of tax codes, deadlines, and employee paperwork. It’s easy to feel overwhelmed.
The key is to break it all down into smaller, more manageable steps. If you build a solid foundation right from the start, you can avoid some seriously expensive mistakes down the road.
First things first, you’ll need an Employer Identification Number (EIN) from the IRS. This is non-negotiable. Think of it as a Social Security number for your business—it’s how the government tracks your tax reporting for your employees. You absolutely cannot run payroll without one.
The Essential Paperwork for Every Hire
With your EIN in hand, your next job is to get the right paperwork from every single person you hire. This isn’t just bureaucratic box-ticking; it’s a legal must-do that determines exactly how you calculate their take-home pay and tax withholdings.
Make sure you have these forms on file for every employee:
- Form W-4 (Employee’s Withholding Certificate): This is the form where your employee tells you their filing status and number of dependents, which dictates how much federal income tax to hold back from their paycheck.
- Form I-9 (Employment Eligibility Verification): You are legally required to use this form to confirm the identity and legal authorization to work for everyone you hire in the United States.
- State Withholding Forms: Don’t forget about state taxes! Many states have their own version of the W-4, so be sure you’re using the correct form for your location to calculate state income tax accurately.
A classic rookie mistake is misclassifying workers. You have to know the difference between a W-2 employee and a 1099 independent contractor. Getting this wrong can lead to a world of pain, including massive penalties, back taxes, and other legal headaches.
Quick-Start Payroll Setup Checklist
Getting your payroll system up and running involves a few crucial first steps. This table breaks down the essentials to get you started on the right foot.
| Action Item | Why It’s Important | Key Takeaway |
|---|---|---|
| Get an EIN | This is your business’s federal tax ID. You can’t legally pay employees or file payroll taxes without it. | Apply online with the IRS; it’s fast and free. This is your absolute first step. |
| Collect W-4s | This form from each employee determines how much federal income tax to withhold from their wages. | An incorrect or missing W-4 leads to tax errors for both you and the employee. |
| Complete I-9s | Verifies an employee’s identity and legal right to work in the U.S. It’s a mandatory compliance step. | Keep these forms separate from personnel files and be ready for potential audits. |
| Gather State Forms | State and local tax laws vary. You need the right state-specific forms to calculate withholdings correctly. | Check your state’s department of revenue website for required new hire paperwork. |
Following this checklist will ensure you have the fundamental pieces in place before you run your first payroll.
Your Role in the Bigger Economic Picture
When you handle payroll, you’re doing more than just an administrative chore—you’re fulfilling a major economic responsibility. Small businesses are the engine of the U.S. economy, representing 99.7% of all companies with paid staff.
Collectively, these businesses account for 39.4% of the entire private sector payroll, which translates to a mind-boggling $2.9 trillion every year. With numbers that big, it’s no wonder a recent survey found that 31% of small business owners outsource payroll to lighten the administrative burden.
Whether you decide to manage it in-house or get some help, a clear and organized process is what matters most. By taking a structured approach to collecting documents and learning the tax basics, you can handle payroll with confidence. If you’d rather leave it to the experts, exploring dedicated payroll services can ensure you stay compliant and efficient from day one.
Getting Your Paperwork in Order: Employee and Business Info
A smooth payroll run doesn’t just magically happen on payday. The real work begins the moment you hire someone, with a solid system for collecting all the necessary information. I like to think of it as building the foundation for your house—if you use shaky data, the whole structure will eventually have problems.
Getting this part right is more than just good organization; it’s a legal requirement. Small mistakes during onboarding can spiral into major tax headaches and compliance issues down the road. The goal here is to create a bulletproof process from day one.
Essential Paperwork for Every New Hire
Before you can even think about running payroll for a new employee, you need them to fill out a few critical government forms. These documents give you the information needed to calculate their tax withholdings correctly and, just as importantly, verify they’re legally eligible to work.
Here’s the absolute must-have list for every single person you bring on board:
- Form W-4 (Employee’s Withholding Certificate): This is the holy grail of tax withholding. It tells you the employee’s filing status, how many dependents they have, and any other adjustments they need to make. A properly completed W-4 is your key to withholding the right amount of federal income tax.
- Form I-9 (Employment Eligibility Verification): This one is non-negotiable. It confirms your new hire is legally authorized to work in the United States. You, the employer, have to physically review their identification documents and fill out your section of the form within three days of their start date.
- State-Specific Withholding Forms: Don’t forget this one! Many states have their own version of the W-4 for state income taxes. Forgetting to have an employee fill out the correct form for your state is a common, and often costly, mistake.
On top of these official forms, you’ll obviously need their personal details: full legal name, current address, Social Security number, and their bank account info if you’re planning on using direct deposit.
My biggest piece of advice? Create a standardized new hire packet—it can be a physical folder or a digital one. Put every single form in there. This makes the process repeatable and ensures nothing ever gets missed. It turns onboarding from a scramble into a simple, error-free checklist.
W-2 Employee vs. 1099 Contractor: A Critical Distinction
This is one of the most dangerous—and expensive—mistakes I see small business owners make. You absolutely have to get the classification of your workers right. The line between a W-2 employee and a 1099 independent contractor is a big deal to the IRS, and they have very strict rules defining who is who.
If you get this wrong, the consequences can be severe. You could be on the hook for back taxes, hefty fines, and penalties for things like FICA (Social Security and Medicare) and unemployment taxes that you should have been paying all along.
Here’s a quick way to tell the difference:
| Factor | W-2 Employee | 1099 Contractor |
|---|---|---|
| Control | You dictate how, when, and where they do the work. | They control their own methods and schedule to complete the job. |
| Tools | You provide the equipment and supplies they need. | They typically use their own tools and equipment. |
| Payment | They get a regular wage or salary on a set schedule. | They usually invoice you for a project or by the hour. |
| Benefits | They’re eligible for things like health insurance and PTO. | They receive no employee benefits from you. |
Always look at the actual working relationship through this lens. If you have significant control over the worker, they’re almost certainly an employee, and you need to pay them through your payroll system.
A Quick Look at the Small Business Payroll Landscape
It’s easy to think of small businesses as one giant group, but the reality of payroll is much more specific. While a staggering 99.9% of all businesses in the U.S. are technically “small,” the vast majority are what you’d call nonemployer firms—think solo freelancers or single-person LLCs.
In reality, only about 18.1% of small businesses actually have paid employees on their books.
But don’t let that number fool you. Those businesses are an absolute powerhouse, employing nearly 59 million Americans and accounting for 39% of the entire private sector payroll. This just goes to show how vital it is for this smaller group of employers to manage their payroll with precision. You can explore more fascinating small business employment trends on cake.com.
Decoding Payroll Taxes and Staying Compliant
For most business owners, the word “payroll” is practically synonymous with “taxes.” It can feel like the most complex and intimidating part of the whole operation, but it really doesn’t have to be a source of constant stress.
The trick is to know exactly what you’re dealing with. Once you understand what the taxes are, who pays them, and when they’re due, the whole process becomes much less mysterious. Let’s break it all down so you can handle your payroll with confidence.
Federal Payroll Tax Explained
At the federal level, your tax obligations fall into a few key categories. Think of them as required contributions that both you and your team make to fund national programs. Your job as the employer is to calculate these amounts precisely, withhold them from paychecks, and send the money to the government.
Here’s what you’ll be handling on the federal side:
- Federal Income Tax: This is what you withhold directly from an employee’s gross pay. The exact amount depends on the information they provide on their Form W-4, like their filing status and any claimed dependents.
- FICA Taxes (Social Security & Medicare): This one is a team effort. You’ll withhold part of this from your employee’s pay, and then you’ll pay a matching amount out of the company’s pocket. For 2024, the split is 6.2% from each of you for Social Security (on earnings up to $168,600) and 1.45% each for Medicare (with no income cap).
Then there’s one more big one that’s all on you.
- FUTA (Federal Unemployment Tax Act): This tax is paid 100% by the employer—you never deduct this from an employee’s wages. The official FUTA rate is 6.0% on the first $7,000 an employee earns. But here’s the good news: if you pay your state unemployment taxes on time, you can get a credit of up to 5.4%, which brings the effective FUTA rate down to a much more manageable 0.6%.
This distinction between employee-paid and employer-paid taxes is critical. Getting it wrong can lead to underpayment and some serious penalties. Just remember: FICA is split, but FUTA is all you.
State and Local Tax Obligations
Just when you feel like you’ve got a handle on the federal stuff, you have to shift your focus to state—and sometimes local—tax rules. These requirements can vary wildly depending on where your business is located, adding another layer of complexity to small business payroll.
The most common state tax is SUTA (State Unemployment Tax Act). Much like its federal counterpart, FUTA, this is an employer-paid tax that funds benefits for workers who lose their jobs. Every state has its own SUTA tax rate and wage base, so you absolutely must check with your state’s workforce agency to get the correct numbers.
On top of that, most states have their own income tax that you’ll need to withhold from paychecks. While a few states have no income tax (lucky them!), you’ll need employees in most states to fill out a state-specific withholding form. Some cities and counties even pile on with their own local income taxes.
Depositing Taxes and Filing Forms
Calculating taxes is only half the job; paying them on time is the other, equally critical half. The IRS and state agencies are incredibly strict about deposit deadlines. Your schedule will either be monthly or semi-weekly, and it’s determined by your total tax liability during a “lookback period.” If you’re a new employer, you’ll almost always start on a monthly schedule.
Miss a deposit, and you’re looking at stiff penalties. It’s essential to get these dates on your calendar. Beyond just sending in the money, you also have to file regular reports to show what you’ve paid.
These are the core forms you’ll get to know well:
- Form 941 (Employer’s QUARTERLY Federal Tax Return): You’ll file this every three months to report the income taxes, Social Security, and Medicare taxes you’ve withheld and paid.
- Form 940 (Employer’s Annual Federal Unemployment (FUTA) Tax Return): This one is filed just once a year to report your total FUTA tax liability.
- Forms W-2 and W-3: At the end of the year, you’ll give each employee a Form W-2 showing their total earnings and withholdings. You’ll then send copies of all W-2s, along with a summary Form W-3, to the Social Security Administration.
Staying on top of these forms and dates is the foundation of good payroll compliance. It’s also smart to explore various tax-saving tips for business owners to make sure your financial strategy is as efficient as possible while still meeting all your obligations.
Choosing Your Payroll Method: Manual, Software, or Service?
Now that you have your tax IDs and employee information sorted, it’s time for a big decision: how will you actually run payroll? This choice is a major one, hitting your budget, your schedule, and your overall sanity. For most small business owners, it boils down to three main paths: doing it yourself, using dedicated software, or outsourcing to a professional service.
Each approach has its own real-world trade-offs. What works brilliantly for a solopreneur with one part-time assistant could be a complete nightmare for a growing shop with ten employees. Let’s dig into the pros and cons of each to see which one fits your business right now.
To make this easier, here’s a quick comparison of the three main payroll methods.
Comparing Payroll Methods for Small Businesses
| Method | Best For | Pros | Cons |
|---|---|---|---|
| Manual (DIY) | Business owners with 1-2 salaried employees and a very strong grasp of tax rules. | Virtually no direct cost; complete control. | Extremely time-consuming; high risk of costly errors; no support. |
| Payroll Software | Most small to medium-sized businesses looking for a balance of control, automation, and cost. | Automates tax calculations and filings; saves significant time; offers employee self-service. | Monthly subscription fee; requires some setup and management. |
| Full-Service Provider | Businesses that are growing quickly, have complex needs (like multi-state employees), or want to be completely hands-off. | Eliminates payroll tasks entirely; guarantees compliance; provides expert support. | Highest cost of the three options; less direct control over the process. |
As you can see, the “best” method really depends on your specific situation—your budget, your comfort level with taxes, and how much you value your time.
The Do-It-Yourself (Manual) Approach
Going the manual route is the most basic option. You’ll be the one calculating wages, figuring out tax withholdings from IRS tables, and making deductions with a spreadsheet. While the upfront cost is practically zero, the hidden costs—your time and the risk of mistakes—can be staggering.
Honestly, this path is only a good idea if you have one, maybe two, salaried employees and an incredibly simple tax situation. Even then, you’re on the hook for every single calculation, every tax filing, and every deadline. A single typo in a spreadsheet formula can cascade into incorrect paychecks and hefty tax penalties from the IRS.
I always tell clients to think twice before going manual. Unless you genuinely love spreadsheets, have hours to spare, and feel confident navigating tax regulations, the risk just isn’t worth it. That time you spend triple-checking your math is almost always better spent finding your next customer.
Using Payroll Software for Automation
For the vast majority of small businesses, payroll software is the sweet spot. It takes the most difficult and error-prone tasks off your plate—like tax calculations and filings—while leaving you in the driver’s seat. These platforms are built to handle everything from direct deposits to creating and sending year-end W-2s.
When you’re shopping around for software, here are the non-negotiable features to look for:
- Automated Tax Payments & Filings: The system should do more than just calculate federal, state, and local taxes. It needs to automatically pay them and file the required forms for you.
- Direct Deposit: This is a must. It saves you the headache of printing, signing, and handing out paper checks.
- Employee Self-Service: A portal where employees can view their own pay stubs and tax forms will save you from answering the same questions over and over.
- Accounting Integration: Make sure it plays nice with your accounting software, like QuickBooks or Xero. This makes bookkeeping so much smoother.
This graphic gives you a great visual of how a paycheck is broken down, showing where all the money goes between gross pay and what the employee actually takes home.
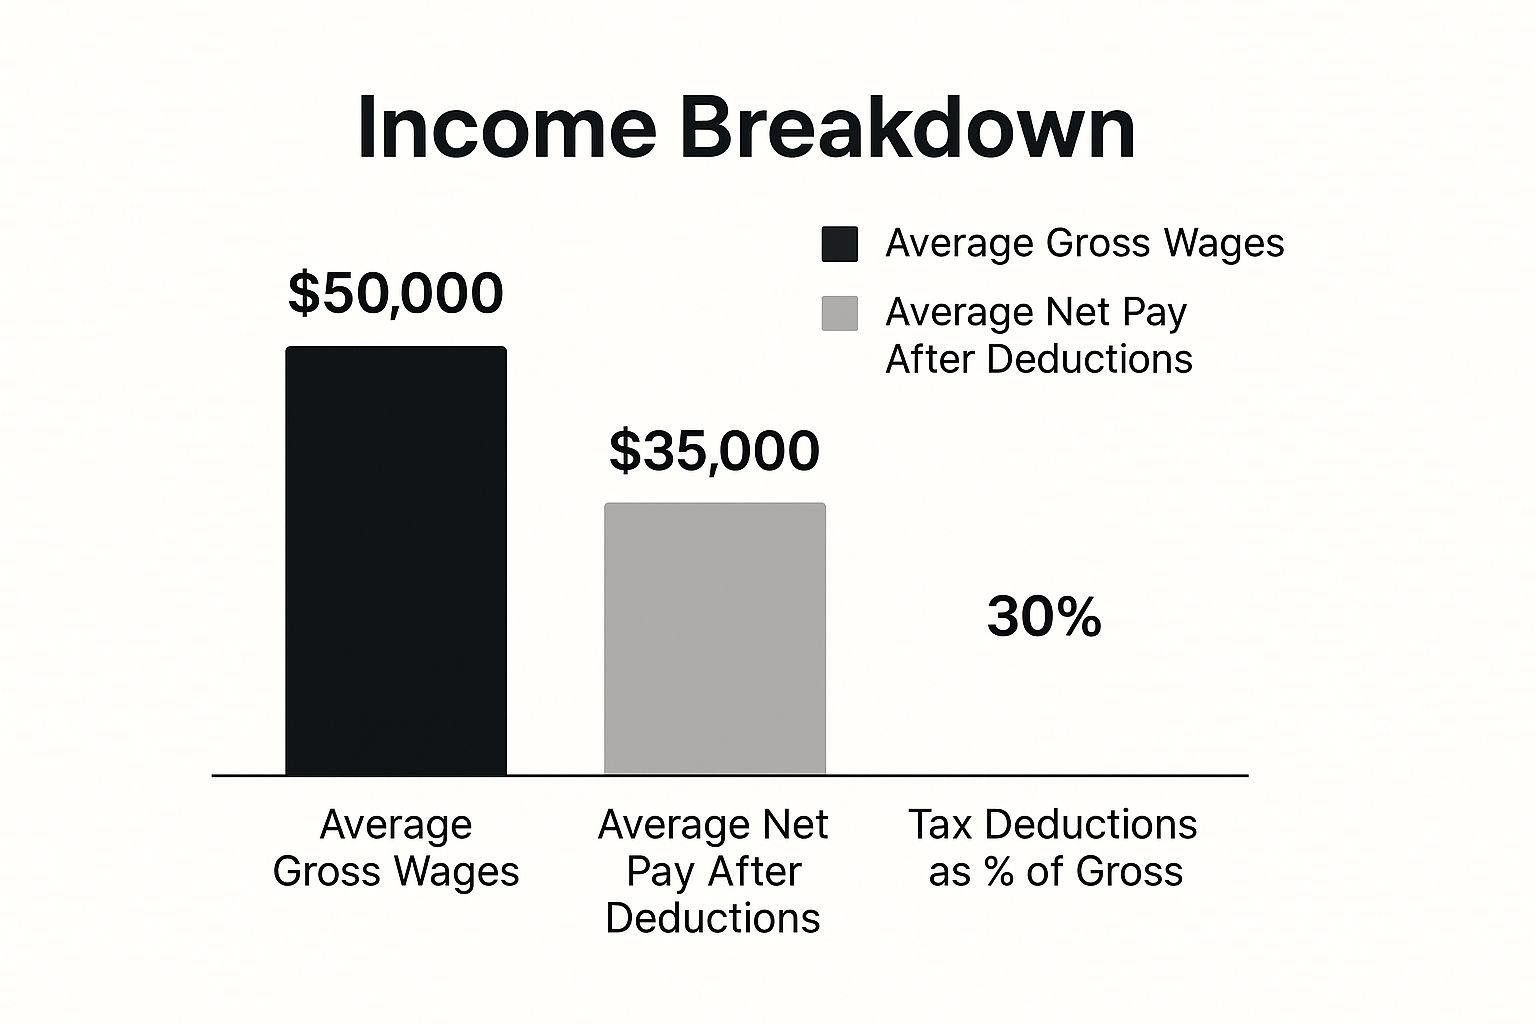
It’s a clear reminder of how federal and state withholdings dramatically impact an employee’s final net pay.
Outsourcing to a Full-Service Provider
Your third option is to hand the entire process over to a full-service payroll provider or an accounting firm. This is the ultimate “set it and forget it” approach. You just provide employee hours and salary details, and they manage absolutely everything else—calculations, direct deposits, tax filings, compliance, and even dealing with tax agencies on your behalf.
This is often the best choice for businesses scaling quickly, those with employees in different states (which creates a tax nightmare), or owners who simply want payroll completely off their plate. While it comes with the highest price tag, it can easily pay for itself by preventing expensive errors and giving you back your most valuable asset: your time.
Payroll is a huge operational cost—companies often spend 15% to 30% of total revenue on it, and the global payroll services market is projected to hit $13.13 billion by 2033. This growth is driven by a desire for efficiency, with 74% of organizations now using or planning to adopt cloud-based payroll systems.
Ultimately, your choice should tie back to your business’s overall financial strategy. For a deeper dive into how payroll fits into the bigger picture, check out our guide on strategic business tax planning.
Running Payroll and Keeping Meticulous Records
Alright, you’ve laid the groundwork. Now it’s time to actually run payroll. This is where all that prep work really starts to pay off, turning what could be a headache into a smooth, repeatable process. The goal here is simple: pay everyone correctly and on time, every single time.
First up is calculating gross pay. For your hourly folks, it’s pretty straightforward math: multiply their hourly rate by the hours they worked. Just don’t forget about overtime. Any non-exempt employee who clocks over 40 hours in a workweek needs to be paid at least 1.5 times their regular rate for those extra hours. It’s a common mistake, so keep an eye on it.
Salaried employees are a bit easier. You just divide their annual salary by how many pay periods you have in a year. For instance, if you have someone making $52,000 a year and you pay bi-weekly (that’s 26 paychecks), their gross pay per check is $2,000. And if you’re giving out bonuses or commissions, make sure to add those into the gross pay calculation for that period.
From Gross Pay to Net Pay
Once you have that gross pay number, you need to start subtracting things to get to their net pay—the actual amount they take home. This is a two-step dance involving pre-tax and post-tax deductions.
You always start with pre-tax deductions. These are items that come out of an employee’s paycheck before you calculate income tax, which is a nice perk for them because it lowers their overall taxable income.
Typical pre-tax deductions you’ll see are:
- Contributions to a traditional 401(k) or similar retirement plan.
- Employee premiums for health, dental, or vision insurance.
- Money set aside for a Health Savings Account (HSA).
After you’ve subtracted those, you’re left with the employee’s taxable wages. Now you can calculate and withhold the necessary taxes: federal income tax, FICA (that’s Social Security and Medicare), and any state or local taxes that apply.
Lastly, you pull out any post-tax deductions. Think of things like Roth 401(k) contributions or court-ordered wage garnishments. What’s left over after all of that? That’s the net pay, the magic number that goes onto their check or into their bank account.
The Art of Meticulous Record-Keeping
Here’s a crucial point: your job isn’t done when the direct deposits land. A huge part of knowing how to do payroll for a small business is keeping immaculate records. This isn’t just about being organized; it’s a legal shield that will save you from a world of hurt if you ever face an audit or an employee dispute.
From my experience, poor record-keeping is one of the most common—and avoidable—payroll pitfalls. Think of it as your business’s financial memory. If an auditor asks for timesheets from three years ago, you need to be able to produce them quickly, not spend a week digging through disorganized files.
The IRS and the Department of Labor are very clear about what you need to keep and for how long. The general rule of thumb is to hold onto all your payroll records for a minimum of four years.
This isn’t just a suggestion—it’s a requirement. Make sure you have these documents securely stored:
- Timesheets or any other records of hours worked.
- Proof you actually paid your people (e.g., canceled checks, direct deposit confirmations).
- Each employee’s W-4 form and any state-specific withholding forms.
- Pay stubs showing the breakdown of gross pay, all deductions, and net pay for every pay period.
- Copies of every payroll tax form you file, like Forms 941 and 940.
- Records related to employee benefits, including contributions and enrollments.
Honestly, a digital, cloud-based system is your best friend here. Set up a logical folder structure for each employee and tax year. This simple habit keeps you compliant and makes it easy to answer any employee questions about their pay history. When you do it right, record-keeping stops being a chore and becomes a serious business asset.
Got a Question? Common Payroll Puzzles for Business Owners
Even when you’ve got your payroll system running like a well-oiled machine, strange situations will pop up. It’s inevitable. Every entrepreneur I’ve ever worked with eventually hits a snag that the standard playbook doesn’t cover. Knowing how to confidently handle these curveballs is just as crucial as getting the routine stuff right.
Let’s dive into some of the most frequent and frankly, most stressful, questions I get from business owners. These are the real-world headaches that need clear, straightforward answers to keep your business compliant and your team paid correctly.
How Do I Handle Payroll for an Employee in Another State?
Hiring remote talent is a fantastic way to grow, but bringing on an employee from another state adds a whole new dimension to your payroll. The moment you hire someone who lives and works across state lines, you’re on the hook to register your business with that state’s tax and labor departments.
Here’s what that usually means for you:
- Withholding state income tax: You’ll need to withhold income tax based on where your employee lives, not where your business is located. This requires getting a state withholding account number in their state.
- Paying SUTA taxes: You’ll also have to pay into that state’s unemployment tax (SUTA) system. The rates and the amount of wages they apply to can be wildly different from what you’re used to.
- Following local labor laws: Pay close attention to the other state’s rules. Things like minimum wage, overtime calculations, and paid leave requirements can vary significantly from your home state.
Dropping the ball on this isn’t an option—the penalties for non-compliance can be steep. This is one area where payroll software with multi-state capabilities isn’t just a nice-to-have; it’s practically a necessity. It can automate the tricky calculations and file the necessary forms for you.
What Is the Correct Way to Fix a Payroll Error?
That sinking feeling when you realize a paycheck was wrong is all too common. Don’t panic. Discovering a mistake after payday is stressful, but it’s almost always fixable. The most important thing is to act fast and be transparent with your employee. Usually, the mistake is an underpayment.
If you’ve underpaid someone, the cleanest fix is to cut them a separate check for the difference right away. You can run what’s called an “off-cycle” payroll to make them whole. This shows good faith and means they aren’t waiting until the next pay period for money they’ve already earned. Just make sure you calculate and withhold the proper taxes on that extra payment.
Overpayments are a bit more delicate. You can’t just claw the money back from their next paycheck without their consent. Many states have laws that protect employee wages from large, sudden deductions. The best approach is to notify the employee in writing, explain what happened, and agree on a reasonable repayment plan, like small deductions over a few pay periods.
Always document everything. Keep a clear paper trail of the error, how you corrected the calculation, and all your communication with the employee. This documentation is your proof that you identified and fixed the issue properly, which is vital for both maintaining trust and legal protection.
How Do I Process a Final Paycheck?
When an employee leaves your company, whether they resigned or were let go, you have a legal obligation to provide their final paycheck promptly. And when I say promptly, I mean it—state laws are incredibly strict about the timing. Some states demand you issue the final check on the employee’s very last day, while others give you until the next scheduled payday.
It is absolutely critical to check your state’s final pay laws to avoid costly penalties.
This last check needs to include all wages they’re owed for their final work period. It also has to include any accrued, unused vacation time if your state law or company policy requires you to pay it out. A quick tip: don’t lump severance pay into this final paycheck. Severance is a separate payment and should be handled with its own agreement.
Make sure you follow all the standard tax withholding rules on this final payment. How you handle an employee’s exit is the last impression you make. Getting it right reinforces your reputation as a fair and professional employer and is a key part of truly mastering how to do payroll for your small business.
Navigating these tricky situations is much easier when you have an expert in your corner. The team at Allied Tax Advisors uses decades of hands-on experience and sophisticated software to manage every payroll detail, from multi-state compliance to final paychecks. To ensure your payroll is always accurate and stress-free, learn more at https://alliedtax.com.