
When you get right down to it, doing payroll for your small business is a four-part dance: gathering the right info, picking a system, crunching the numbers correctly, and hitting your tax deadlines. If you can nail this foundation from day one, you'll save yourself a world of headaches and potential penalties later on.
Setting Up a Bulletproof Payroll Foundation
Before you even think about cutting that first paycheck, you need to get your legal and organizational ducks in a row. This initial setup isn't just a box-ticking exercise; it's the most critical part of the entire process. A tiny mistake here—a mistyped number or a forgotten form—can snowball into some serious tax and compliance problems.
Think of it like building the foundation of a house. If the concrete isn't solid, everything you build on top will be shaky. The goal is to create a system that's secure, compliant, and easy to repeat every time you bring someone new on board.
Securing Your Employer Identification Numbers
Your first official move is to get your business registered with the government. This means getting two key numbers. You literally can't pay employees legally without them.
-
Federal Employer Identification Number (EIN): This is basically a Social Security number for your business. You get it directly from the IRS, and it’s completely free. You'll need it for filing federal taxes and reporting your employees' wages.
-
State Employer Identification Number: On top of the federal number, most states require their own version for state-level taxes, like income tax withholding and unemployment insurance. You’ll need to track this down from your state’s tax agency.
Forgetting to register at the state level is a surprisingly common mistake, and it can quickly lead to penalties for unpaid state unemployment taxes.
Key Takeaway: Guard your EINs just as you would your own Social Security number. They are the core of your business's financial identity and are essential for almost every payroll action you'll take.
Gathering Essential Employee Paperwork
Once your business has its official identifiers, it's time to collect specific forms from every single employee. These documents are non-negotiable; they tell you how to calculate tax withholdings and confirm that your new hire is legally allowed to work in the United States.
It’s absolutely critical to have these forms filled out on or before an employee's first day of work. No exceptions.
-
Form W-4 (Employee's Withholding Certificate): This IRS form is the instruction manual for withholding federal income tax. It tells you how much to take out of each paycheck based on the employee's filing status, dependents, and other adjustments. Every new hire must fill one out.
-
Form I-9 (Employment Eligibility Verification): This federal form verifies a person's identity and their authorization to work in the U.S. As the employer, you are responsible for physically inspecting their documents and keeping the completed I-9 on file.
Keeping these documents safe is not optional. Whether you opt for a locked filing cabinet or a secure digital folder, you're legally required to protect this sensitive information. For businesses looking beyond local hires, a comprehensive global payroll guide can offer some great insights into handling compensation and compliance on a broader scale.
Choosing Your Payroll System: Manual vs. Software
Alright, you've got all your employee and tax paperwork in order. Now comes a big decision: how are you actually going to run payroll? You're basically at a fork in the road. One path is the DIY route with spreadsheets, and the other is investing in dedicated payroll software.
This isn't just about preference; it's a choice that will have a real impact on your time, your accuracy, and—critically—your ability to stay on the right side of the law.
The Gritty Reality of Manual Payroll
At first glance, going manual with a spreadsheet seems like a no-brainer. It's free, right? And you have total control. But from my experience, this path is full of hidden costs and landmines that can easily blow up that initial "free" appeal.
When you do it all yourself, every single calculation is on you. We're talking overtime pay, federal and state tax withholdings, social security, Medicare, and any other unique deductions. One tiny typo in a formula or one misread tax table can lead to a wrong paycheck. That's a surefire way to erode trust with your team.
Even worse, it can lead to an incorrect tax filing. The IRS doesn't mess around with employment tax mistakes—they handed out over $5 billion in penalties for them in a single year. That statistic alone should tell you how risky human error can be.
The burden doesn't stop at calculations. You become the compliance officer, personally responsible for tracking every shift in federal, state, and local tax laws. It's a massive time suck that pulls you away from what you should be doing: running your business.
The Case for Payroll Software
This is exactly why payroll software was invented. Modern platforms are built to take this entire headache off your plate. They automate everything from the gross-to-net pay calculation to withholding the precise amount for every deduction.
Payroll software isn't just a fancy calculator; it's a compliance partner. It automatically stays current on tax regulations, so you don't have to. This drastically cuts your risk of making those costly errors.
These tools handle direct deposits, file your payroll taxes on your behalf, and automatically generate W-2s and 1099s at the end of the year.
The move toward automation is undeniable. The global payroll outsourcing market is expected to grow by $6.15 billion by 2025, largely because businesses are tired of the manual grind. Many platforms also play nicely with your accounting software. For instance, if you're a QuickBooks user, integrating a payroll system can create a seamless financial workflow. You can learn more about getting your books in order with our guide on how to set up QuickBooks.
Sometimes, seeing things side-by-side makes the choice crystal clear.
Comparing Payroll Methods: Manual vs. Software
Here’s a straightforward breakdown of what you’re looking at with each option.
| Feature | Manual Payroll (Spreadsheets) | Payroll Software |
|---|---|---|
| Initial Cost | Free (besides your time) | Monthly subscription fee |
| Accuracy | High risk of human error | Automated, highly accurate |
| Time Investment | Very high (6+ hours per month) | Minimal once set up |
| Compliance | Entirely your responsibility | Automatically updated for you |
| Record-Keeping | Manual file management | Secure, centralized, and accessible |
| Best For | Sole proprietors with no employees | Any business with 1+ employee |
While you might be able to get by with a spreadsheet when you're just paying yourself, everything changes the moment you hire your first employee. The complexity shoots up, and so does the risk.
Honestly, investing in a solid payroll system is one of the smartest moves you can make. It protects your business, gives you back valuable time, and ensures your team gets paid correctly and on schedule, every single time.
Calculating Paychecks with Total Accuracy
Alright, this is where the rubber meets the road. Turning an employee's hours into an accurate paycheck is the core of the entire payroll process. Getting this right is non-negotiable—small mistakes can quickly erode employee trust and land you in hot water with compliance.
The whole process is about getting from gross pay (the total amount earned) to net pay (the take-home amount). Let's break it down.
Gross pay is the starting line. It's everything an employee earns before a single cent is deducted for taxes or benefits. The calculation is pretty straightforward, but it varies based on how you pay your people.
For a salaried employee, it's simple. If you pay someone an annual salary of $52,000 and run payroll weekly, their gross pay for each period is $1,000. Easy.
Hourly employees require a little more math. You just multiply their hourly rate by the hours they worked. An employee who makes $20 per hour and works a standard 40-hour week has a gross pay of $800. But what if they work 45 hours? You’ll need to factor in overtime pay, which is typically 1.5 times their regular rate for those extra 5 hours.
Handling Deductions and Withholdings
Once you've got the gross pay figured out, it's time to subtract all the necessary deductions. The key here is understanding the difference between pre-tax and post-tax deductions, because the order you subtract them in directly impacts how much tax an employee pays.
Pre-tax deductions come out first. They are subtracted from gross pay before income taxes are calculated, which lowers the employee's overall taxable income. Less taxable income means a smaller tax bill.
- Examples: Contributions to a traditional 401(k) retirement plan or premiums for certain health insurance plans.
Post-tax deductions are taken out after all the taxes have been calculated and withheld. These don't offer the same tax-saving benefit.
- Examples: Things like Roth IRA contributions or court-ordered wage garnishments fall into this category.
Beyond these voluntary deductions, you have the mandatory tax withholdings. This is the part that often feels intimidating, but it's just a matter of following the rules. You'll withhold federal and state income taxes based on the employee's W-4 form, along with FICA taxes.
A Quick Look at FICA: This isn't a single tax, but two combined. It includes a 6.2% Social Security tax and a 1.45% Medicare tax. That adds up to a 7.65% deduction from your employee's paycheck—and as the employer, you're required to match that contribution.
Bringing It All Together for Net Pay
After you’ve subtracted pre-tax deductions, calculated and withheld all the necessary taxes, and then taken out any post-tax deductions, you're left with the net pay. This is the actual amount that gets deposited into your employee’s bank account. It’s the number they really care about.
The goal here is 100% accuracy, every single pay period. This also includes things beyond regular wages, like correctly calculating sick pay. Properly understanding statutory sick pay for part-time workers is crucial for keeping everything fair and compliant, and that resource is a great place to get the details straight.
Getting Your Team Paid and Keeping Your Records Straight
After you've run the numbers, it's time for the moment everyone's been waiting for: payday. This is more than just a simple bank transaction; it’s when you follow through on your promise to reward your team for their hard work. How you actually get the money to them matters—for efficiency, security, and morale.
The right payment method really depends on your business and what works for your employees. Each option has its own pros and cons.
- Direct Deposit: This is the gold standard for a reason. It's fast, secure, and convenient for both you and your employees. Funds move electronically from your account to theirs, creating a clean digital paper trail along the way.
- Paper Checks: Some people still prefer a physical check, and that's perfectly fine. Just know that it's a more manual process. You have to print, sign, and distribute them, and there's always the risk of a check getting lost or taking a few extra days to clear.
- Pay Cards: Think of these as reloadable debit cards. You load an employee's net pay onto the card each payday. This is a great alternative for team members who don't have a traditional bank account, giving them a quick and safe way to access their money.
Why Meticulous Record-Keeping Is Non-Negotiable
Once everyone has been paid, you're not quite done. Keeping detailed, accurate records isn't just a "nice to have"—it's a legal requirement. These documents are your proof if a question ever comes up from an employee or a government agency.
This is an area where a lot of small businesses get tripped up. It’s not for lack of trying; it’s just that mistakes happen. In fact, about one in five payroll cycles has some kind of error. Even though small companies pay out a staggering $2.9 trillion in payroll each year, compliance can be a real challenge. For a deeper dive, check out these insightful payroll statistics and insights.
Think of your payroll records as the official financial story of your team. You need to keep them organized, secure, and accessible for as long as the law requires.
A Quick Tip from Experience: As a general rule, the IRS wants you to hold onto employment tax records for at least four years. But don't stop there—some states require you to keep them even longer, so always double-check your local regulations.
Your Payroll Records Checklist
Here’s a breakdown of the essential documents you absolutely need to have on file. Treat this like your payroll command center.
- Pay Stubs: Every employee needs a detailed statement for every single paycheck, showing their gross wages, every deduction, and the final net pay.
- Timesheets: You need ironclad proof of hours worked, especially for your hourly, non-exempt employees. This includes any and all overtime hours.
- Tax Forms: Keep copies of every employee's W-4 form. You'll also need to hang onto all the tax forms you file with the government, like your quarterly Form 941.
- Year-End Filings: Don't forget copies of the W-2s you send to employees and the 1099s you issue to independent contractors. If you're foggy on the contractor deadlines, our guide on when 1099s are due can clear things up.
Staying on top of your records isn't just about avoiding headaches and penalties. It's about building a more professional, buttoned-up, and resilient business.
Navigating Payroll Taxes and Filing Deadlines
Getting your team paid on time is a huge win, but it's really only half the job. The other, and frankly, more daunting half, is getting all the taxes you've withheld over to the right government agencies. This isn't just about cutting a check; it's a non-negotiable part of staying compliant and avoiding some pretty nasty financial penalties down the road.
If you're feeling the pressure, you're not alone. About one-third of small business owners I talk to spend more than six hours a month just wrestling with payroll. This number, pulled from a recent ADP global payroll survey, really drives home why getting the tax part right is so critical—it’s where most of the time and complexity lies.
This visual gives a great high-level view of the entire payroll cycle, from the initial number-crunching to the final record-keeping.
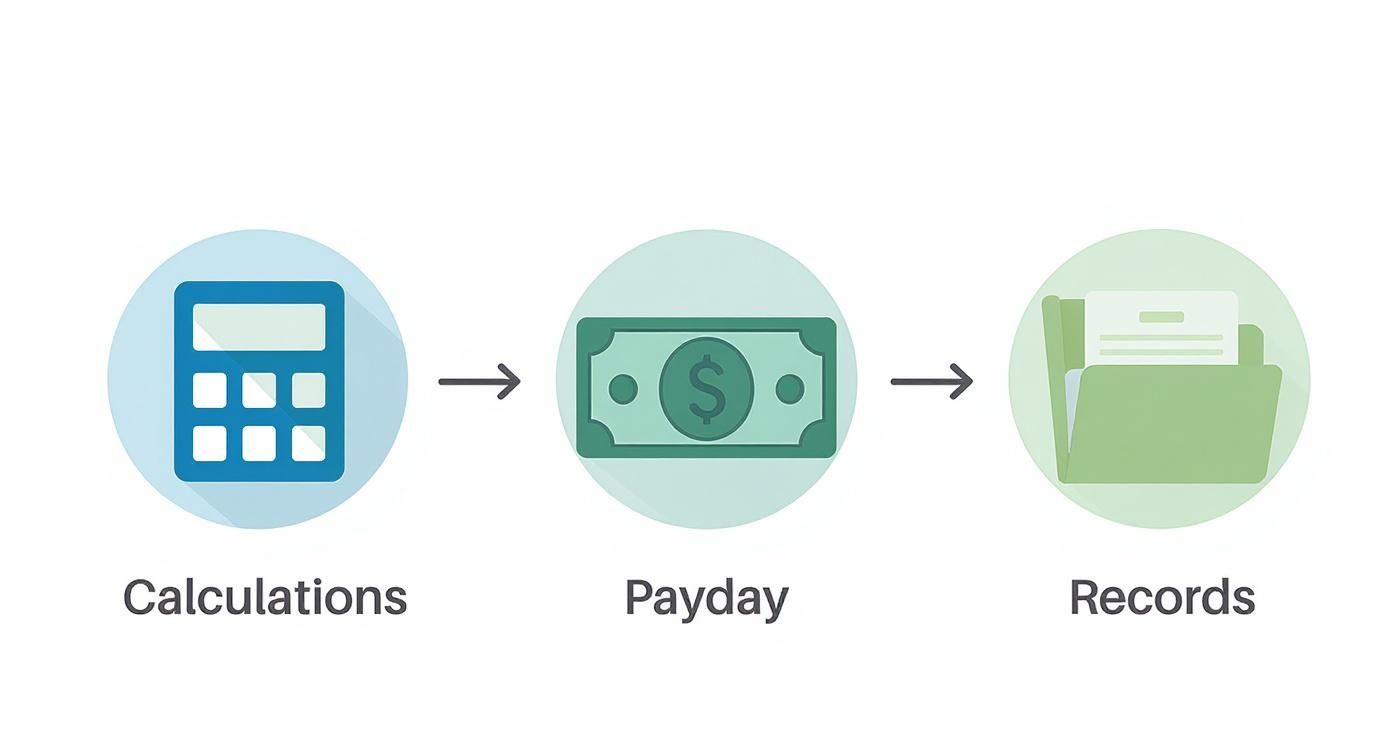
As you can see, it's a continuous loop. Each step directly impacts the next, so accuracy from the start is absolutely key.
Understanding Your Tax Deposit Schedule
First things first: you don't get to choose when you send the government its money. The IRS sets your deposit schedule for federal income and FICA taxes based on your total tax liability during a "lookback period." For most small businesses, this boils down to one of two schedules.
- Monthly Depositor: This is the simpler of the two. You deposit employment taxes on the 15th of the month after you paid your employees. So, for all the paydays you had in May, the tax deposit is due by June 15th. Easy enough.
- Semi-Weekly Depositor: This one can trip people up. The deadlines depend on your payday. If payday falls on a Wednesday, Thursday, or Friday, your deposit is due the following Wednesday. If payday is over the weekend or on a Monday or Tuesday, the deposit is due the following Friday. It takes some getting used to.
I can't stress this enough: missing a deposit deadline is not an option. The IRS doesn't mess around with penalties. They start at 2% for being just 1-5 days late and can jump all the way to 15% if you haven't paid within 10 days of getting that first official notice.
Key Tax Forms and Year-End Reporting
Beyond the regular deposits, you also have to report your payroll activity on specific forms. These filings are how you officially reconcile the taxes you've collected and paid with what the government knows you owe.
Expert Tip: I always tell my clients to put tax deadlines in their calendars with multiple reminders, just like a meeting with their most important customer. Treating these dates with that level of importance is the single best way to avoid the last-minute scramble and the stress that comes with it.
You'll get very familiar with these forms:
- Form 941 (Employer's Quarterly Federal Tax Return): This is your big quarterly report to the IRS. It sums up all the federal income tax, Social Security, and Medicare you withheld, plus your share of FICA. It's due on the last day of the month after a quarter ends—so, April 30, July 31, October 31, and January 31.
- Forms W-2 and W-3: This is the year-end sprint. You have to get a Form W-2 to every single employee by January 31, detailing their total pay and all the taxes withheld for the year. At the same time, you'll bundle copies of every W-2 with a summary form, the W-3, and send it all to the Social Security Administration.
Getting a handle on these tax obligations is truly the foundation of a solid payroll system. If you want to dive deeper into the nuts and bolts of the calculations, our guide on how to calculate payroll taxes is a fantastic resource that breaks it all down step-by-step.
Common Questions About Small Business Payroll
Even after you've got your payroll system running like a well-oiled machine, unique situations will inevitably crop up. Knowing how to handle these one-offs is just as crucial as running your regular payroll. Let's tackle some of the most common questions I hear from small business owners.
How Do I Handle Payroll for a Remote Employee in Another State?
Hiring remotely is a fantastic way to find top-tier talent, but it definitely adds a few wrinkles to your payroll process. The moment you hire an employee in a different state, you have to register your business with that state's tax agency. This isn't optional—it's the very first step.
From there, you'll withhold and pay income taxes based on where the employee lives and works, not where your company is headquartered. You're also on the hook for following that state's specific rules for unemployment insurance (SUI), minimum wage, and overtime. This is one area where a good payroll platform really shines, as it can handle these multi-state calculations automatically and keep you out of trouble.
A Quick Tip from Experience: Start thinking of your business as having a "nexus," or a physical presence, in every state where you have an employee. Adopting this mindset from the beginning helps you frame your compliance duties correctly and avoid surprises down the road.
What Is the Difference Between an Employee and a Contractor?
This is one of the most important distinctions you'll ever make in payroll, and getting it wrong can bring on some serious IRS penalties. The entire thing boils down to one simple concept: control. How much control do you have over the worker and the work they produce?
- Employees (W-2): You dictate what work gets done and how it gets done. You’re responsible for withholding income and FICA taxes from their paychecks and sending them a Form W-2 each year.
- Independent Contractors (1099): They are their own boss. They control how and when they do the work, often using their own tools and operating as a separate business. You don't withhold any taxes from their pay; they handle their own self-employment taxes. If you pay a contractor $600 or more in a single year, you must send them a Form 1099-NEC.
Trying to misclassify a W-2 employee as a 1099 contractor just to save money on payroll taxes is a massive red flag for the IRS. Don't do it.
What Are the Most Common Payroll Mistakes to Avoid?
Most of the costly payroll errors I see boil down to just a handful of issues. If you know what they are, you can actively steer clear of them.
The biggest culprits are misclassifying workers (like we just discussed), missing critical tax filing deadlines, and messing up overtime pay calculations. To stay safe, always use a clear set of criteria to verify worker classification. Set up a payroll calendar or use your software's reminders to stay on top of tax deadlines.
And remember, federal law requires that non-exempt employees be paid 1.5 times their regular hourly rate for any hours worked over 40 in a workweek. A reliable payroll system is truly your best line of defense against these common but avoidable mistakes.
Navigating the world of payroll is a mission-critical task for any business. For personalized support with payroll processing, tax planning, and bookkeeping, the team at Allied Tax Advisors is here to help you every step of the way. Learn more about our business services and get the peace of mind you deserve.