
Dipping into your personal funds to cover a business expense might seem like a quick fix, but it's a habit that can create a massive headache down the road. It's about more than just messy books; properly separating your finances is fundamental to protecting your personal assets and getting a real, honest look at your company's performance.
Think of it as the first, most crucial step toward financial clarity and building a business that lasts.
Why Mingling Expenses Is a Costly Mistake
When your business and personal finances get tangled, you're opening yourself up to a world of trouble that goes far beyond a stressful tax season. If your business is set up as an LLC or a corporation, this practice has a specific, and quite serious, name: commingling funds.
Commingling can lead to a legal problem known as "piercing the corporate veil."
This is when a court decides there's no real separation between you and your business. If that happens, the liability protection your business structure was supposed to provide vanishes. Suddenly, your personal home, car, and savings could be on the line to cover business debts or lawsuits.
Beyond the legal nightmare, mixed-up finances make it impossible to know if your business is actually making money. How can you gauge profitability when your business account is also paying for your weekly grocery run? Financial planning becomes pure guesswork.
A huge part of this is just knowing what your business costs are. For instance, anyone selling on Amazon needs a crystal-clear picture of their expenses. A great place to start is understanding Amazon seller fees.
Keeping clean, separate records isn't just about staying organized—it's a strategic necessity. The IRS is known to look very closely at commingled funds, and it can be a major red flag for an audit. You can find out more about what triggers https://alliedtax.com/irs-tax-audits-what-triggers-an-audit-and-how-to-prepare/.
Drawing a Clear Line in the Sand
The single most effective thing you can do to keep business and personal finances separate is to give them different homes. This isn’t some high-level financial wizardry; it’s about building a simple, sturdy wall between your two financial lives. The first, and most important, brick in that wall is a dedicated business bank account.
One of the foundational first moves every business owner should make is setting up a dedicated business bank account. This one action forces all your revenue into a single, designated place and ensures every business payment flows out from that same source. Having this clean record is a lifesaver for bookkeeping, tax prep, and just getting a quick, honest look at your cash flow.
Picking the Right Financial Tools
When you're shopping for a bank, don't get distracted by a flashy sign-up bonus. Think about the practical features that will actually make your day-to-day operations smoother. Does the account have low (or no) monthly fees? How easily does it sync with your accounting software, like QuickBooks or Xero? In this day and age, a solid mobile banking app is non-negotiable for managing your money on the go.
Once that's sorted, get a business credit card that’s linked to your new account. Using this card exclusively for company purchases is a smart move for two big reasons:
- It builds your business credit history. This is completely separate from your personal credit score and is incredibly important when you need to get a loan or negotiate better terms with vendors down the road.
- It automates your expense tracking. Every time you swipe, the transaction is automatically logged as a business expense. No more digging through personal bank statements trying to remember if that Amazon purchase was for office supplies or a birthday gift.
By funneling all your business income and spending through these dedicated accounts, you're essentially creating a crystal-clear financial diary. That clarity is the bedrock for categorizing transactions and organizing your books, which are the core components of a proper chart of accounts. If you're not familiar with that term, our guide on what a chart of accounts is is a great place to start.
What to Do When Wires Get Crossed
Look, even with the most organized system, mistakes are bound to happen. Maybe you accidentally paid for a software subscription with your personal debit card. The key is to have a clear process for fixing it.
The best way to handle these mix-ups is to create a formal reimbursement policy—even if the only "employee" is you.
Document the expense just as you would for an employee: save the receipt, make a note of what the purchase was for, and then transfer the exact amount from your business account to your personal one. Make sure to label the transfer clearly, like "Reimbursement for Software Subscription." This simple habit keeps your books clean and leaves a clear paper trail.
Finding the Right Tools for Expense Tracking
Once you've set up separate bank accounts, it’s time to retire that old shoebox overflowing with crumpled receipts. Modern tools can handle the heavy lifting of expense tracking, turning a dreaded chore into an almost invisible background task. This simple shift frees you up to focus on what really matters: growing your business.
The "right" system is all about what fits your business's complexity and your personal habits. For some new entrepreneurs, a well-organized spreadsheet is a perfectly good starting point. It’s a zero-cost way to get a basic handle on your cash flow.
But as your business picks up steam, that spreadsheet can quickly become a bottleneck. This is when dedicated accounting software and smart expense-tracking apps really start to pay for themselves.
Choosing Your Expense Tracking System
Think about your daily reality. A freelance photographer zipping between shoots needs something different than a consulting firm juggling multiple retainers.
For that photographer, a nimble mobile app like Expensify is a lifesaver. You can snap a photo of a receipt for a new lens filter or a client lunch right at the table, and the app instantly digitizes and categorizes it. No more lost receipts, no more missed deductions.
On the other hand, the consulting firm would find more value in a robust accounting platform like QuickBooks or Xero. These systems connect directly to your business bank account, automatically importing transactions and making smart suggestions for how to categorize them. They go beyond simple tracking to handle invoicing, payroll, and generating the detailed financial reports you'll need for tax time or loan applications.
We've put together a comprehensive breakdown of the top business expense tracking apps if you want to dive deeper into a full comparison.
My Two Cents: Your tool should match your reality on the ground. A simple system you actually use every day is infinitely better than a powerful, complicated one you ignore.
Comparing Popular Expense Tracking Tools
Choosing the right tool can feel overwhelming. To help, I've put together a quick comparison of the most common methods, from simple spreadsheets to full-featured software. Think about where your business is today and where you want it to be in a year when making your choice.
| Tool/Method | Best For | Key Features | Potential Drawbacks |
|---|---|---|---|
| Spreadsheet | Solopreneurs and freelancers just starting out. | Low/no cost, highly customizable, total control over data. | Manual entry is time-consuming, prone to errors, doesn't scale well. |
| Mobile Apps | Service-based professionals, frequent travelers. | Receipt scanning, GPS mileage tracking, on-the-go categorization. | May have limited reporting features, can be an extra monthly cost. |
| Accounting Software | Growing small businesses, e-commerce stores, consultancies. | Bank integration, invoicing, payroll, detailed reporting. | Steeper learning curve, higher monthly subscription cost. |
Ultimately, any of these can work. The goal is to pick one and commit to it, building a consistent habit of tracking every business dollar.
This becomes especially critical when you're on the road. With business travel projected to hit 1.4 billion international arrivals, getting back to pre-pandemic numbers, the potential for mixing up expenses is huge. Even small mistakes can add up to major headaches and missed deductions. You can see more data on global business travel trends at gbta.org.
This decision tree really boils it all down to a simple, core principle.
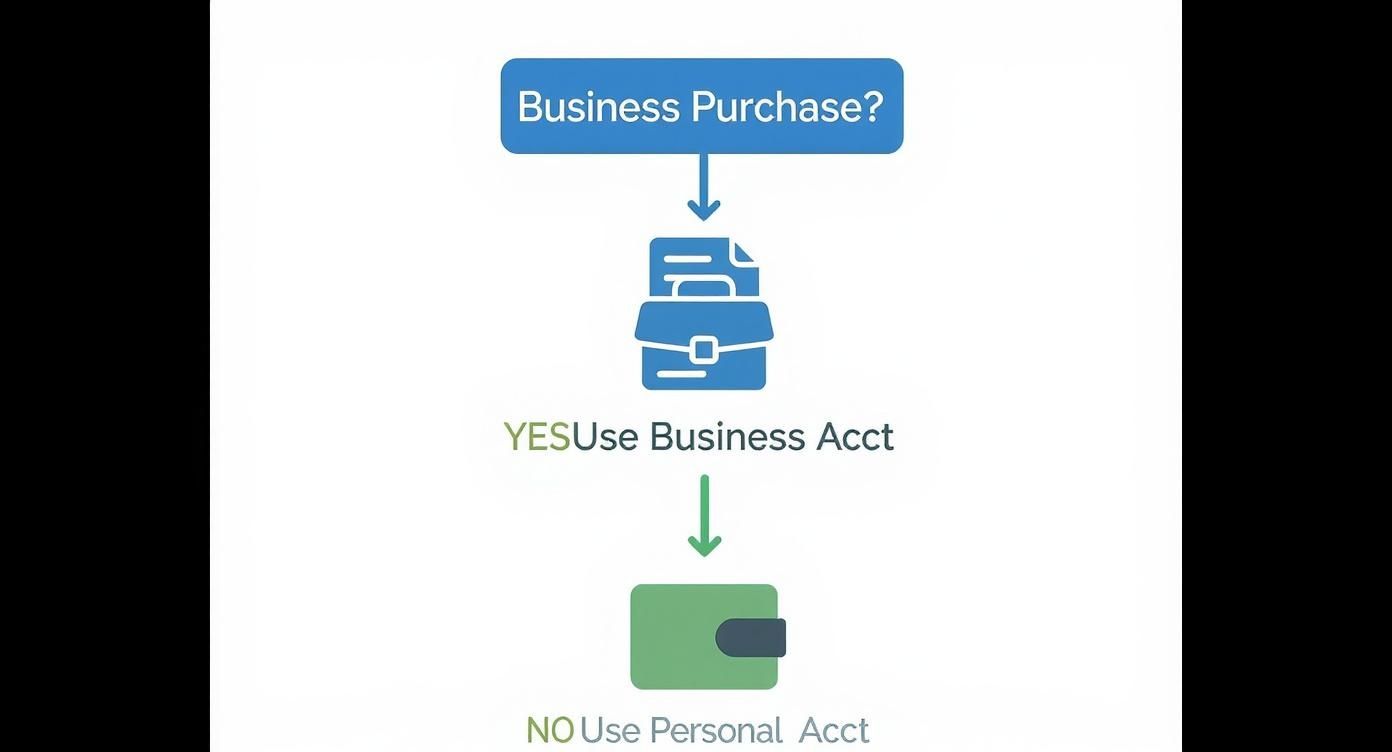
The infographic just reinforces the golden rule: if the purchase is for your business, use your business account. Every single time. That discipline is the foundation of clean, stress-free bookkeeping.
Even when you’ve got a solid system, some expenses will always be tricky. These are the ones that straddle the line between business and personal life, living in a sort of financial gray area. Think about your cell phone, home internet, and personal car—they're classic examples of assets that pull double duty.
It’s tempting to just ignore these or, even worse, try to write off the whole thing. But trying to claim 100% of a mixed-use item as a business expense is one of the fastest ways to get unwanted attention from the IRS. The real goal is to find a logical, fair way to split the cost. You need a defensible method for figuring out the business-use percentage.
How to Calculate Your Business Use Percentage
For those monthly bills like your internet or cell phone, a simple usage-based estimate usually works just fine.
- Internet Service: If you work from home, take an honest look at how you use your internet. Are you spending about 60% of your online time on work-related tasks? Then it's generally reasonable to deduct 60% of your monthly bill. The key is to have a rational basis for your number.
- Cell Phone Bill: You can apply the same thinking to your phone. Look back over a few months of usage. Estimate the percentage of calls, texts, and data that are for business. Just be prepared to explain how you arrived at that percentage if you’re ever asked.
When you get to bigger-ticket items, like your home office or vehicle, the rules get tighter and your record-keeping has to be on point.
The danger in getting this wrong isn't just losing a deduction. It could trigger penalties or even a full-blown audit. A global survey found that 71% of finance leaders say manual expense tracking makes compliance a struggle. This just goes to show how vital a clear, documented system is for keeping yourself out of hot water. You can read more about the challenges of expense management on atlys.com.
Documenting Vehicle and Home Office Costs
When it’s time to deduct your car or home office, "guesstimates" are a no-go. The IRS is very specific about the documentation they expect you to have.
For your vehicle, you generally have two choices: the standard mileage rate or the actual expense method. It doesn't matter which one you pick; you must keep a detailed mileage log. This isn't optional. Your log needs the date, starting and ending odometer readings, total miles, and the business purpose for every single trip. This used to be a pain, but apps like MileIQ can now track this for you automatically.
The home office deduction has its own strict rule: you need a part of your home used regularly and exclusively for business. To calculate the deduction, you figure out the square footage of your office as a percentage of your home's total square footage. You can then apply that percentage to home expenses like rent, utilities, or insurance. As always, detailed and organized records are your best friend here.
Good Habits Are the Secret to Staying Organized
You can have the best tools and the slickest systems, but they’re useless if you don't actually use them. The real secret to keeping your business and personal finances separate is building a few simple, consistent habits. Eventually, they just become second nature.
The biggest mistake I see entrepreneurs make is letting receipts and uncategorized expenses pile up for months. Don't do it. Instead, schedule a recurring "money date" with yourself. Block off just 30 minutes on your calendar every Friday afternoon, or maybe the first day of the month.
During that time, your only job is to review transactions, categorize everything in your software, and make sure your accounts line up. This tiny, regular commitment is what saves you from that massive, stressful cleanup when tax time rolls around.
Build Your Financial Routines
One of the most effective habits you can start today is to digitize receipts on the spot. Seriously, before you even leave the parking lot, use an app to snap a photo of that receipt. It’s a two-second task that eliminates the risk of losing it and makes tracking almost effortless.
Another game-changer is to pay yourself a predictable salary.
By transferring a set amount from your business account to your personal account on a regular schedule—just like a traditional paycheck—you create a clear boundary. This simple act drastically reduces the temptation to dip into business funds for personal needs.
Think of these routines as the foundation of good financial hygiene. They keep your books clean, accurate, and always ready for whatever comes your way—whether it's tax season or an opportunity to apply for a loan.
Got Questions? Let's Clear Up the Gray Areas
Even with the best intentions, things can get murky when you’re trying to keep your finances separate. Let's walk through a couple of the most common scenarios that trip up even seasoned business owners.
What if I Accidentally Use My Personal Card for a Business Purchase?
It happens. You're at a store, grab a pack of printer paper for the office, and realize you used your personal debit card at the checkout. Don't panic, but don't just ignore it either.
The key is to treat this situation like a formal, short-term loan to your business. You need to create a clear paper trail.
Promptly reimburse yourself from the business account for the exact amount of the purchase. Log this in your accounting software not as a purchase, but as a "reimbursement" or "owner contribution repayment." This keeps your books clean and shows that you're correcting the mistake, not just mixing funds.
How Do I Actually Pay Myself?
This is a big one. Just pulling cash out of the business account whenever you need it is one of the fastest ways to get into trouble with commingled funds. You need a structured, predictable way to take money out for personal use.
There are two standard methods for this, depending on your business structure:
-
Paying an Owner's Draw: If you're a sole proprietor or running an LLC, you can take an "owner's draw." This is a straightforward transfer of a set amount of money from your business account to your personal account. It's not a wage, but a distribution of profits.
-
Running a Salary: For those with an S-Corp or C-Corp, you're required to pay yourself a "reasonable salary" as an employee of your own company. This means setting up a proper payroll system, withholding taxes, and paying yourself on a regular schedule just like any other employee.
Both of these methods establish a clean, defensible boundary. They define your pay as a legitimate business transaction rather than a random dip into the company cookie jar. This isn't just about good bookkeeping; it’s a fundamental discipline that reinforces the legal separation protecting your personal assets.
Getting this right isn't just about being organized—it's about building a professional, legally sound business from the ground up. This habit is crucial for your long-term financial health and peace of mind.
At Allied Tax Advisors, we help business owners build strong financial foundations. Our team can guide you through setting up proper bookkeeping, payroll, and tax planning to ensure your finances are always separate and audit-ready. Learn more by visiting our website.