
When you're figuring out the right structure for your small business, the whole LLC vs. S Corp thing can feel unnecessarily confusing. Let's clear it up from the start: an LLC is a legal business structure you set up with your state, while an S Corp is a tax status you ask the IRS for.
Think of it this way: you can have an LLC and then decide to have it taxed like an S Corp. This gives you the legal simplicity of an LLC with the potential tax benefits of an S Corp.
Understanding the Core Distinction
Choosing your business framework is a huge step. It’s not just about filling out forms; this decision directly shapes your tax bill, protects your personal assets, and sets the tone for your administrative workload for years to come. For anyone new to this process, getting a handle on the bigger picture of how to open a small business provides a great foundation before you get lost in the weeds of legal structures.
People often talk about LLCs and S Corps as if you have to pick one or the other, but that's not quite right. They operate on different levels. An LLC (Limited Liability Company) is a business entity you register in your state. Its main job is to put a legal wall between your personal life and your business, shielding your personal assets if the company runs into trouble.
An S Corporation, however, isn't a type of business entity you can form from scratch. It's a special tax classification from the IRS. An eligible business, like an LLC or a C Corporation, can elect to be treated as an S Corp for tax purposes. This changes the rules on how profits are taxed and can be a smart way to lower your self-employment tax burden.
Key Decision Factors at a Glance
As we go through this guide, we'll break down the LLC vs. S Corp decision based on what really matters to a small business owner. The right answer for you depends entirely on your specific goals and financial situation.
| Feature | Limited Liability Company (LLC) | S Corporation (S Corp) Tax Status |
|---|---|---|
| Primary Nature | A state-level legal business structure. | A federal tax classification election. |
| Formation | Simpler state filing (Articles of Organization). | State filing plus an IRS tax election (Form 2553). |
| Taxation | Flexible (taxed as sole prop, partnership, or S/C Corp). | Pass-through taxation with salary and distributions. |
| Ownership | Highly flexible; unlimited members, can be non-citizens. | Strict; max 100 U.S. citizen/resident shareholders. |
The most crucial takeaway is that you don't choose between an LLC and an S Corp in the traditional sense. You first form a legal entity (like an LLC) and then decide if electing S Corp tax treatment is the right financial move.
Comparing the Core Differences at a Glance
Before diving into the nitty-gritty of tax strategy and compliance, it helps to see the LLC vs S Corp for small business differences laid out side-by-side. This quick overview will serve as our foundation for the more detailed analysis ahead.
The table below highlights the fundamental characteristics of each structure. Keep an eye on the distinctions in ownership, management, and especially taxation—these are the areas where your choice will have the biggest impact on your business's future.
Quick Comparison: LLC vs S Corp Key Attributes
| Feature | LLC (Limited Liability Company) | S Corp (S Corporation) |
|---|---|---|
| Formation | Created by filing Articles of Organization with the state. | A tax election filed with the IRS using Form 2553. Requires an underlying legal entity (like an LLC or C Corp) first. |
| Ownership Rules | Highly flexible. Can have unlimited members, including individuals, corporations, other LLCs, and non-U.S. citizens. | Strict limitations. Limited to 100 shareholders who must be U.S. citizens or legal residents. Corporations and partnerships cannot be shareholders. |
| Default Taxation | Pass-through. All profits pass to members' personal tax returns and are subject to self-employment taxes (Social Security and Medicare). | Pass-through. Owner-employees must be paid a "reasonable salary" subject to payroll taxes. Remaining profits are passed through as distributions, which are not subject to self-employment tax. |
| Management | Flexible. Can be managed by its members (member-managed) or by appointed managers (manager-managed) with fewer formal requirements. | More rigid. Requires a formal management structure with a board of directors and corporate officers, even if the owner fills all roles. |
| Profit Distribution | Flexible. Profits can be distributed disproportionately to ownership percentages as defined in the operating agreement. | Rigid. Profits and losses must be distributed strictly according to each shareholder's percentage of stock ownership. |
Understanding the Trade-Offs
That table makes the core trade-off crystal clear. An LLC gives you maximum flexibility and keeps things simple, which is why it's such a popular starting point for new businesses. Its relaxed rules on ownership and profit-sharing let you create custom arrangements that fit unique partnership dynamics.
On the flip side, an S Corp brings more structure and rules to the table. Business owners accept these added complexities for one big reason: a powerful tax advantage. The ability to separate your salary from profit distributions can create substantial savings on self-employment taxes, a key strategic move for profitable companies.
Key Insight: This isn't just about saving money. It's about weighing potential tax benefits against the extra administrative work and ownership limits that an S Corp election demands.
Practical Implications for Your Business
Let’s put this in real-world terms. If you're a solo consultant just getting started, the simplicity of an LLC is a huge win. You get crucial liability protection without the headaches of corporate minutes or running payroll for yourself.
But the calculus changes once your business is consistently netting over $60,000 to $80,000 a year. At that income level, the tax savings from an S Corp election can easily cover the costs of payroll services and more involved accounting. For instance, a business with $120,000 in profit could potentially save thousands in self-employment tax by classifying a portion of that income as a distribution instead of owner's draw.
As we go deeper, keep this comparison in mind. We'll unpack each of these points, helping you match your specific business goals to the structure that truly makes sense for you financially and operationally.
How Your Tax Strategy Impacts Your Bottom Line
This is where the rubber meets the road in the LLC vs S Corp for small business debate. The choice you make has a direct, and often significant, impact on your tax bill. Understanding this is key to keeping more of your hard-earned money.
At first glance, both structures look similar. They both enjoy pass-through taxation, which is a fancy way of saying the business itself doesn't pay income tax. Instead, all the profits and losses are "passed through" to you to report on your personal tax return.
The real difference, however, lies in how the IRS treats those profits, especially when it comes to self-employment taxes. For a standard LLC, every single dollar of profit gets hit with this tax. With an S Corp, you get a strategic way to reduce that burden.
The Self-Employment Tax Dilemma
For most small business owners I talk to, especially those set up as a standard LLC or sole proprietorship, the self-employment tax is one of their biggest headaches. It’s a 15.3% tax that covers both the employer and employee shares of Social Security and Medicare.
As your business grows and becomes more profitable, so does this tax bill. It's a constant drain on your bottom line, and it’s the primary financial pain point that the S Corp election was designed to solve.
When you elect to be taxed as an S Corp, you fundamentally change how the IRS sees your income. You go from being just an "owner" to an "owner-employee." This distinction is the secret sauce for unlocking major tax savings.
The S Corp Advantage: A Tale of Two Incomes
The core tax benefit of an S Corp comes from its unique ability to split your earnings into two different buckets: a reasonable salary and shareholder distributions. A standard LLC simply can't do this.
Here’s how it works:
- Reasonable Salary: As an owner-employee, the S Corp must pay you a "reasonable salary" for the actual work you do. This salary is subject to FICA payroll taxes (the same Social Security and Medicare taxes), just like any regular W-2 employee.
- Shareholder Distributions: Any company profits left over after paying your salary and other expenses can be paid out to you as distributions. Here's the kicker: these distributions are not subject to self-employment or FICA taxes.
This two-part structure means only a portion of your total income gets hit with that 15.3% tax. The rest is only subject to regular income tax. As your business scales, the savings can become substantial. You can take a closer look at this in our guide to https://alliedtax.com/understanding-the-s-corp-tax-rate-a-guide-for-business-owners/.
Key Takeaway: The S Corp strategy isn't about tax evasion. It's about legally reclassifying a portion of your income to minimize your self-employment tax bill. The salary gets taxed for FICA; the distributions do not.
A Practical Example of Tax Savings
Let's run the numbers to see just how powerful this can be. Imagine your business has a net profit of $150,000 for the year.
Scenario 1: Standard LLC Taxation
As a single-member LLC, that entire $150,000 is considered profit and is subject to the full 15.3% self-employment tax.
- Self-Employment Tax: $150,000 x 15.3% = $22,950 (approximately)
Scenario 2: S Corp Taxation
You make the S Corp election and, after some research, determine a reasonable salary for your role is $60,000 a year. The remaining $90,000 is taken as a shareholder distribution.
- Payroll Taxes on Salary: $60,000 x 15.3% = $9,180
- Self-Employment Tax on Distribution: $0
In this side-by-side comparison, the S Corp election saves you $13,770 in taxes for the year. That's real money back in your pocket, and it’s why so many profitable small businesses make the switch.
The Critical Rule of Reasonable Compensation
The entire S Corp tax-saving strategy lives or dies by one critical IRS rule: you must pay yourself a reasonable salary.
You can't game the system by paying yourself a token salary of $10,000 and taking $140,000 in distributions. That’s a massive red flag for the IRS and a quick way to trigger an audit, back taxes, and hefty penalties.
So, what does "reasonable" mean? The IRS is intentionally vague, but the figure should be based on real-world factors like:
- Your specific duties and responsibilities
- Your experience and qualifications
- What similar positions pay in your industry and region
- The company's overall financial health
Getting this number right is non-negotiable. If you pay yourself too little, the IRS can reclassify your distributions as wages and send you a bill for the back taxes. This is an area where working with a pro from Allied Tax Advisors isn't just a good idea—it's essential for staying compliant and sleeping well at night.
Beyond your own business structure, your tax strategy also involves how you classify your team. Properly understanding 1099 employees versus W-2 employees is another critical piece of the compliance puzzle that can significantly impact your bottom line.
Formation and Ongoing Compliance: What's the Real-World Workload?
Beyond the numbers on a tax return, you have to think about the day-to-day reality of running your business. The administrative side of things is where the LLC and S corp really part ways. It's crucial to be honest with yourself about how much time you're willing to spend on paperwork and formal procedures. This isn’t just about the initial setup; it’s about the long-term commitment needed to keep your business legitimate and protected.
The Straightforward Path: Forming an LLC
For many new entrepreneurs, the LLC is the path of least resistance. It's designed to be simple. Generally, you just file a single document with your state—often called the Articles of Organization—and pay a fee. After that, your most important document is your operating agreement, which is your internal playbook for how the business will run.
This operating agreement is critical. It lays out ownership percentages, member duties, and how profits are split. The best part? It's usually an internal document, so you don't have to file it with the state. Ongoing requirements are typically minimal, too, often just an annual report and a small fee.
This no-fuss approach is why the LLC has become the go-to for modern business owners. In fact, LLCs have exploded in popularity, showing 21% average annual growth over the last 30 years, dwarfing the S corp’s 6.8%. This trend makes perfect sense when you consider that 53% of small businesses are now focused on lean operations, as highlighted in guides about choosing a business structure.
The Formalities: Staying Compliant as an S Corp
When you choose to be taxed as an S corp, you’re signing up for a much stricter set of rules. This isn't a "set it and forget it" kind of thing. You're committing to operating like a real corporation, and that comes with a significant amount of administrative work.
Getting started is more involved. First, you have to form a business entity (like an LLC or C corp). Then, you must file Form 2553 with the IRS to officially make the S corp election.
Once that's done, the real compliance work kicks in. You have to follow a rigid set of corporate formalities that a standard LLC owner never has to worry about.
The Big Trade-Off: An S corp can save you a bundle on self-employment taxes, but you're trading that benefit for a serious commitment to corporate governance. If you drop the ball on these duties, you could lose your S corp tax status and even the personal liability protection you thought you had.
To keep your S corp in good standing, you have to:
- Appoint a Board of Directors: Yes, even if it's just you. You need to formally appoint directors to oversee major decisions.
- Adopt Corporate Bylaws: This is your company's official rulebook, detailing everything from shareholder rights to how meetings are conducted.
- Hold Regular Meetings: You are legally required to hold—and document—meetings for both the board of directors and shareholders. Again, this applies even if you're the only one in the room.
- Keep Corporate Minutes: Every major decision from those meetings needs to be formally recorded in minutes and stored safely with your company records.
- Issue Stock: S corp ownership is based on shares of stock, which must be officially issued to all shareholders.
These aren't just suggestions; they are legal requirements. The record-keeping is intense. For an owner already juggling marketing, sales, and operations, this added layer of paperwork can feel like a heavy weight unless you have solid systems or professional help to manage it all.
Planning for Ownership Flexibility and Future Growth
Choosing a business structure isn't just a decision for today; it's about laying the groundwork for where you want to go. When you're weighing an LLC vs. an S Corp for your small business, how each handles ownership and growth is a night-and-day difference. The path you choose now will shape your ability to bring on partners, attract investors, and share profits down the road.
An LLC is practically built for agility. It gives you incredible freedom in how you set up ownership and run the show. This adaptability is a huge reason so many startups and dynamic partnerships go this route right out of the gate.
The Unmatched Flexibility of an LLC
The Limited Liability Company really shines when it comes to its flexible framework, which you can mold to fit just about any business situation. Its structure is deliberately less formal than a traditional corporation, giving owners a much tighter grip on how the company is governed and how money moves.
This flexibility really comes to life in two key areas:
- Who Can Be an Owner: An LLC can have as many owners (called members) as you want. And those members can be pretty much anyone—U.S. citizens, non-U.S. citizens, other corporations, or even other LLCs. This open-door policy is a game-changer if you're thinking about foreign investment or creating complex joint ventures.
- How Profits Are Divided: This is a big one. LLCs allow for what are called "special allocations." It’s a fancy way of saying you can split profits and losses in a way that doesn’t have to mirror ownership percentages. For instance, a partner putting in more "sweat equity" can get a bigger piece of the profit pie, even with a smaller ownership stake. That's a super common and useful setup for new companies.
This built-in adaptability has made LLCs incredibly popular. You get unlimited members, the ability to bring on foreign owners, and flexible profit sharing, all without the corporate formalities of board meetings and rigid stock rules. This makes them a go-to for startups and real estate investors. You can find more insights on the rise of flexible business entities and their tax implications from Berkman Solutions.
For any business with a complex partnership agreement, or for those who see diverse investment sources in their future, the LLC's structural freedom is a massive strategic advantage. It lets you build a company that truly reflects what each partner brings to the table.
The Rigid Framework of an S Corporation
Electing S Corp status, on the other hand, means you're signing up for a much stricter rulebook when it comes to ownership and doling out profits. The IRS lays down these rules, and they're the price of admission for the potential tax savings.
For an S Corp, these rules are black and white:
- Limited Shareholders: You're capped at 100 shareholders. Period. That can become a serious bottleneck for a company that wants to grow by offering equity to a lot of employees or bringing in a wide pool of investors.
- Shareholder Restrictions: Every single shareholder has to be an individual who is a U.S. citizen or resident. This immediately shuts the door on most venture capital firms, institutional investors, and any foreign partners, since corporations and partnerships can't be shareholders.
- One Class of Stock: S Corps are only allowed to issue one class of stock. This is a critical limitation. It means all profits and losses must be distributed strictly based on each shareholder’s ownership percentage. You can't create different tiers of stock with different voting rights or dividend payouts.
That "one class of stock" rule is absolute. If you own 25% of the company, you get exactly 25% of the profit distributions—no ifs, ands, or buts. This can be a major drawback for businesses that want to reward people based on their contributions, not just their initial investment.
Making the Right Call for Your Business
After laying out the tax strategies, compliance hurdles, and ownership rules, the whole LLC vs. S corp for small business debate really boils down to where your business is right now and where you see it going. Forget about finding the single "best" structure. The goal is to pick the one that fits your operational style, profit level, and growth plans at this moment.
And remember, this isn't a forever decision. It's common for businesses to start as a simple LLC and then elect S Corp status later on as profits climb. That's a natural and smart evolution. It's all about matching the structure to your stage.
When an LLC Makes the Most Sense
The Limited Liability Company is the hands-down winner when it comes to flexibility and simplicity. This makes it the go-to choice for a ton of entrepreneurs, especially when they're just starting out. The minimal red tape means you can spend more time building your business and less time on administrative headaches.
An LLC is likely your best bet if you:
- Want to keep things simple. You're looking for liability protection without the hassle of formal board meetings, bylaws, and intense record-keeping.
- Need flexible profit sharing. You have partners and want to split profits in a way that isn't strictly tied to ownership percentage, like rewarding "sweat equity."
- Have a complex ownership team. Your investors or partners include non-U.S. citizens, other corporations, or even other partnerships—none of which are allowed in an S Corp.
- Are still in a low-profit or growth phase. If your business isn't consistently profitable yet, the tax savings from an S Corp probably won't be enough to justify the extra administrative costs.
This chart breaks down the main decision points at a glance.
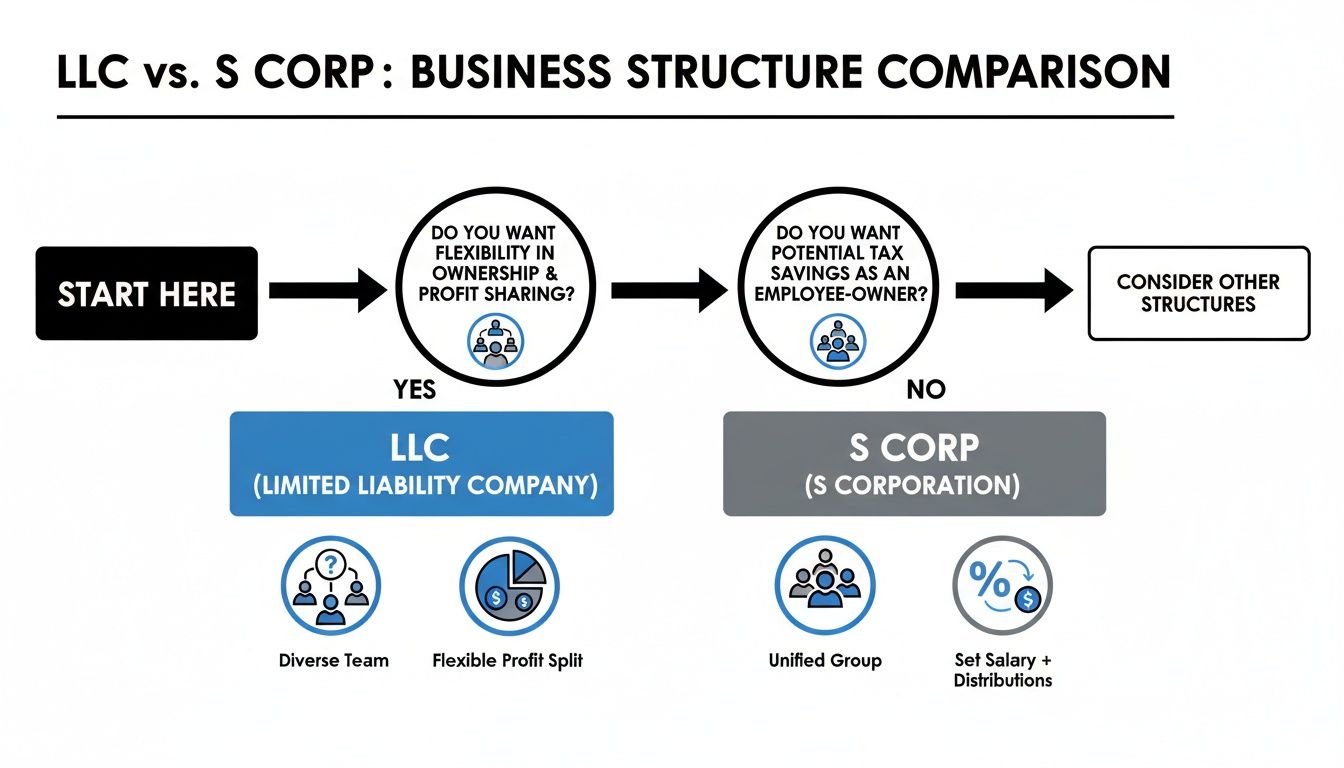
As you can see, LLCs are perfect for businesses that need flexibility in who owns the company and how profits are divided. S Corps, on the other hand, are built for more structured businesses looking to get serious about tax optimization.
When an S Corp is the Smarter Financial Move
Filing for S Corp status is purely a strategic financial play. It definitely adds more complexity to your operations, but it also gives you a powerful tool to slash your self-employment tax bill once your business is making solid, predictable money. This path is for the owner who’s ready to embrace more structure in exchange for real tax savings.
Think of the S Corp election less as a legal change and more as a financial upgrade. It’s a mechanism for keeping more of the money you've worked so hard to earn.
Flipping the switch to an S Corp is a good idea if you:
- Are consistently in the black. Your business is pulling in enough net income (we often see the tipping point around $60,000+) where the self-employment tax savings will be greater than the new costs for payroll and accounting.
- Can pay yourself a reasonable salary. You understand the IRS requires this and are prepared to run payroll and pay yourself a fair wage before taking any tax-advantaged distributions.
- Are ready for corporate formalities. You don't mind holding regular meetings, keeping detailed minutes, and managing payroll to stay compliant.
- Have a straightforward ownership group. Your company has fewer than 100 shareholders, and all of them are U.S. citizens or residents.
Ultimately, the right structure is the one that helps you reach your goals without creating a bunch of unnecessary work. As your business grows and changes, it’s always a good idea to revisit this decision with the team at Allied Tax Advisors to make sure your entity structure is still working for you.
Frequently Asked Questions About LLCs and S Corps
As you get closer to a decision, a few specific questions always seem to pop up. Answering these is often the final step to feeling confident about choosing between an LLC and an S Corp for your small business.
Let’s dig into the common questions I hear from entrepreneurs.
Can I Switch From an LLC to an S Corp Later?
Yes, absolutely. In fact, this is a very common and smart path for growing businesses. You can start as an LLC and, once you’re eligible, simply file Form 2553 with the IRS to be taxed as an S Corporation. You don't even have to change your legal business structure with the state.
This strategy gives you the best of both worlds. You get the simplicity and flexibility of an LLC when you're just starting out. Then, once your business is consistently profitable, you can flip the switch to an S Corp election to start saving on self-employment taxes.
Key Insight: Think of it as an evolution. Starting as an LLC and electing S Corp status later lets your business structure grow with your financial success. It keeps you from taking on extra administrative work before the tax savings make it worthwhile.
What Is a Reasonable Salary for an S Corp?
This is the million-dollar question for S Corp owners. The IRS insists that owner-employees pay themselves a "reasonable salary" before taking any distributions, but they don't give you a magic number. It feels frustratingly vague, but it's the core of S Corp compliance.
The IRS looks at a few key factors to determine if your salary is "reasonable":
- Your Role: What do you actually do day-to-day in the business?
- Your Experience: What skills and background do you bring to the table?
- Market Rates: What would you have to pay someone else to do your job?
- Business Finances: Can the company actually afford to pay that salary?
It's crucial to document how you landed on your salary number in case the IRS ever asks. This is one of those areas where getting professional tax advice isn’t just a good idea—it’s essential for protecting your tax savings.
Are There State-Specific Rules to Consider?
Without a doubt, and ignoring them can be an expensive error. The S Corp is a federal tax election, but your LLC or corporation is a legal entity created under your state's laws. Every state has its own fees, rules, and taxes that can completely change the math.
For instance, some states hit LLCs with a franchise tax, sometimes based on total revenue, not profit. That could make an LLC far more expensive in one state than another. This is why getting advice from someone who understands your local landscape is so important; you need a structure that works on both the federal and state level.
Choosing between an LLC and an S Corp isn't just about today—it's about setting your business up for the future. At Allied Tax Advisors, we live and breathe this stuff. Our team helps small business owners make these critical decisions every day, ensuring their structure is built for tax savings and smooth compliance.
Let us worry about the complex tax rules so you can get back to what you do best: running your business. Learn more about our business services.