
Welcome to QuickBooks! This guide is designed to walk you through the most important first steps—from picking the right plan to getting your company file set up and your bank accounts connected.
Getting this initial setup right is the single most critical part of making QuickBooks work for you. A solid foundation here means accurate financial data from day one, which will save you a world of headaches down the road.
Your First Steps Inside QuickBooks Online
Jumping into new software can feel a bit overwhelming, but QuickBooks Online is designed to make it as painless as possible. Think of this section as your quick-start guide to get you from the sign-up page to a working company file in just a few minutes. We're building the financial home for your business, and a strong foundation makes everything that follows so much easier.
We'll focus on the essential actions you need to take right now. The goal is to get you comfortable with the dashboard, the navigation bar, and that all-important gear icon—your gateway to most of the settings you'll ever need.
Choosing The Right QuickBooks Plan
The very first decision you need to make is which QuickBooks Online plan to go with. This choice really matters because it determines the features you'll have access to. It's all about matching the plan to your specific business needs. A freelance graphic designer working solo has completely different requirements than an LLC with three employees and a growing inventory.
This little decision tree can help you see which plan might be the best fit right out of the gate.
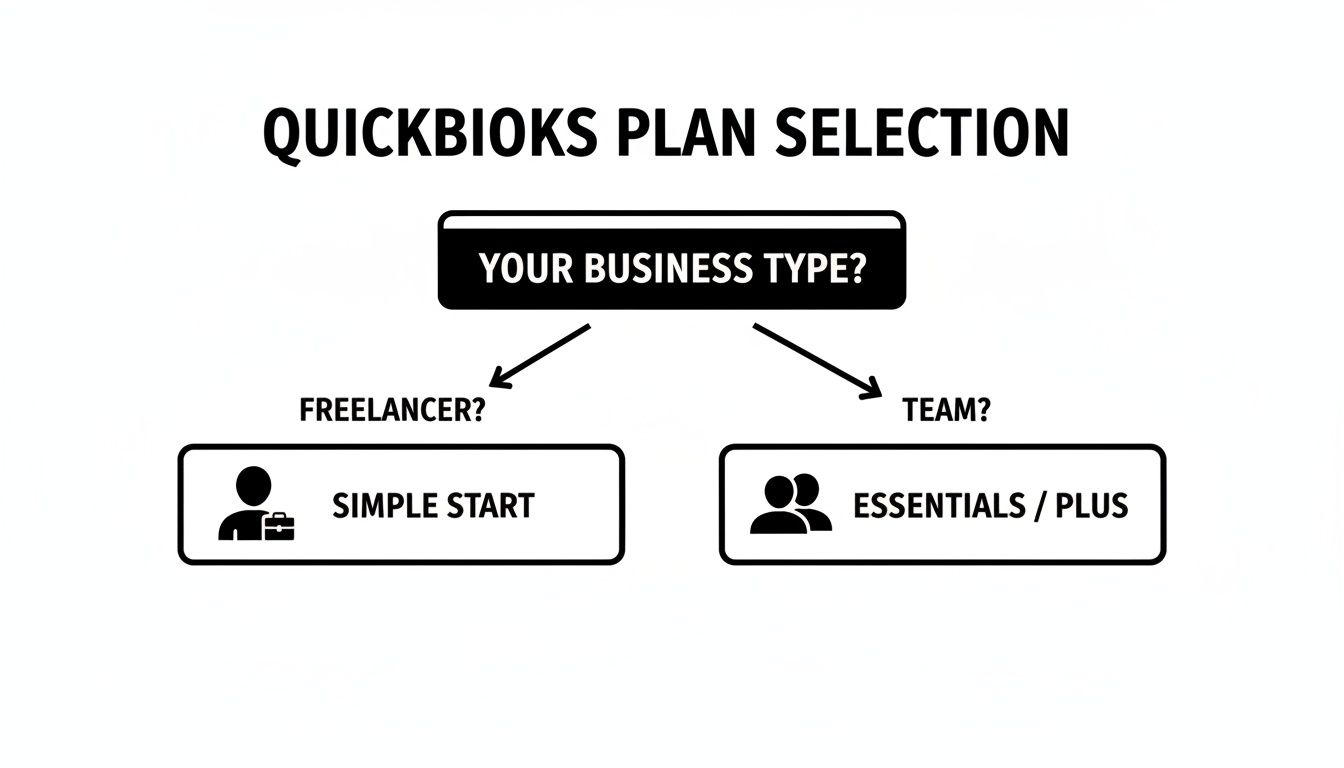
As you can see, freelancers often find that Simple Start has everything they need. But if you have a team, need to track inventory, or manage bills, you'll likely want to look at Essentials or Plus.
Choosing the right QuickBooks plan is crucial. This table compares the core features of the most popular plans for small businesses to help you decide.
QuickBooks Online Plans at a Glance
| Feature | Simple Start | Essentials | Plus |
|---|---|---|---|
| Track Income & Expenses | ✅ | ✅ | ✅ |
| Send Invoices & Estimates | ✅ | ✅ | ✅ |
| Capture & Organize Receipts | ✅ | ✅ | ✅ |
| Manage Users | 1 User | Up to 3 Users | Up to 5 Users |
| Manage & Pay Bills | ❌ | ✅ | ✅ |
| Track Time | ❌ | ✅ | ✅ |
| Track Inventory | ❌ | ❌ | ✅ |
| Track Project Profitability | ❌ | ❌ | ✅ |
The best plan for you depends on your specific needs today, but it’s good to know you can easily upgrade as your business grows.
Setting Up Your Company File
After you've picked a plan, you'll create your company file. This is where you'll plug in the basic details about your business.
Have this information handy:
- Your legal business name and address
- Your Employer Identification Number (EIN) or Social Security Number (if you're a sole proprietor)
- Your business structure (e.g., S Corp, LLC, Sole Proprietorship)
Pro Tip: Getting your business structure right during this setup is a big deal. It tells QuickBooks how to build your initial Chart of Accounts and impacts important tax settings. If you’re even a little unsure, this is the perfect time to check in with your tax pro.
The beauty of QuickBooks is how intuitive this setup is—most beginners can get through it in under 30 minutes. The system guides you through connecting your bank accounts, and once that's done, it can categorize your transactions with up to 95% accuracy using its smart-matching technology. From there, you're just a click away from running your first profit and loss statement.
The final, game-changing step is connecting your business bank and credit card accounts. This is what lets QuickBooks automatically import all your transactions, which saves countless hours of manual data entry and cuts down on human error.
Once your accounts are linked, you'll see your dashboard come to life with real-time financial data. For a more detailed look at this part of the process, check out our complete guide on how to set up QuickBooks.
Building Your Financial Foundation With The Chart Of Accounts
If your company file is the house, then the Chart of Accounts is its architectural blueprint. It’s arguably the most critical piece of your entire bookkeeping system, but the name alone tends to intimidate new users.
Don't let it fool you. At its core, the Chart of Accounts is just an organized list of every category your money can flow into or out of. Every single transaction—from an invoice you send to a coffee you buy for a client—gets tagged to one of these accounts. This simple act of categorizing is what lets QuickBooks generate those incredibly valuable reports, like your Profit & Loss statement.
Getting this foundation right from day one will make every other task in QuickBooks a whole lot smoother and more accurate.
Understanding The Core Account Types
When you first set up your file, QuickBooks gives you a default Chart of Accounts based on the industry you selected. It's a decent starting point, but it's almost never a perfect fit. The real magic happens when you customize it to mirror how your specific business actually works.
To do that, you need to get familiar with the main account types. There are five main buckets you'll be working with:
- Assets: Everything your business owns that has value. This includes the cash in your business checking account, your work truck, or that high-end computer you just bought.
- Liabilities: Everything your business owes to someone else. Think credit card balances, a small business loan, or sales tax you've collected from customers but haven't sent to the state yet.
- Equity: This is the net worth of your business. It's what's left over when you subtract liabilities from assets, including money you’ve personally invested and profits you've kept in the company.
- Income (or Revenue): All the money your business brings in from selling products or services. Getting specific here is key.
- Expenses: All the money your business spends to keep the lights on. This is where you'll track everything from software subscriptions and office rent to advertising costs.
Customizing these accounts is what turns confusing data into clear insights. A freelance graphic designer, for instance, shouldn't just lump all their earnings into one generic "Sales" account. They'd be much better off creating specific income accounts like "Logo Design Services" and "Website Project Income." This small tweak immediately shows them which services are actually driving their revenue.
A well-structured Chart of Accounts is the difference between having raw data and having actionable business intelligence. It allows you to see not just if you made money, but how you made it.
How To Customize Your Chart Of Accounts
Let's make this practical. Imagine you're a real estate investor managing a few rental properties. A generic expense account labeled "Repairs" is far too vague—it won't help you make smart decisions or maximize your tax deductions.
Instead, you'd head into your Chart of Accounts in QuickBooks and add a few new, more specific expense accounts. You could create a main category with sub-accounts nested underneath it, like this:
- Property Maintenance (this is the main, or "parent," account)
- Plumbing Repairs (this is a "sub-account")
- Landscaping Services (another sub-account)
- HVAC Maintenance (and another)
This level of detail is a complete game-changer. Come tax time, you won't be scrolling through a long, messy list of transactions in a single "Repairs" category. You can simply run a report and see your exact spending on plumbing versus landscaping for the year, giving you a crystal-clear picture of your property's true operating costs.
The same logic applies everywhere. A small marketing agency would benefit from breaking down its "Advertising" expense into "Google Ads," "Facebook Ads," and "Content Marketing Tools." The goal is always the same: make your financial story as clear and detailed as you need it to be.
For a deeper dive, our in-depth article on the Chart of Accounts in QuickBooks offers more detailed, step-by-step guidance.
Managing Daily Cash Flow: Invoicing and Expenses
With your Chart of Accounts set up, it’s time to dive into the day-to-day workhorse functions of QuickBooks. This is where you'll likely spend most of your time, and it really comes down to two things: getting money in (invoicing) and tracking money out (expenses).
Getting a solid handle on these two workflows is the secret to a healthy cash flow and knowing, at any given moment, where your business stands financially. Let's start with the fun part—getting paid.
Creating And Sending Professional Invoices
Think of your invoice as more than just a bill; it's a piece of your brand. A clean, professional invoice that’s easy to pay shows clients you’re serious. QuickBooks is fantastic for this, letting you finally ditch those clunky Word documents or generic templates for good.
First things first, you need to add your customers into the system. It's simple: just head to Sales > Customers from the main menu and click New customer. Take a minute to fill in their details accurately—name, company, email, and address. Getting this right now saves you from having to look up and re-enter their info every single time you need to send a bill.
Once your customer is in the system, creating an invoice is a breeze.
- Go to + New > Invoice.
- Pick the customer from the dropdown menu.
- Add the products or services you provided, along with quantities and rates.
- You can even add your company logo and pick a template to match your branding.
Here’s a glimpse of what the invoicing and cash flow dashboard can look like. It’s designed to give you a quick visual on your income and expenses so you know what's going on at a glance.
This dashboard gives you a clear, real-time snapshot of your financial health, helping you make smarter decisions without digging through spreadsheets.
Pro Tip: Turn on QuickBooks Payments immediately. This feature lets your clients pay you directly online with a credit card or bank transfer. We've seen it time and again—invoices with a "Pay Now" button get paid, on average, twice as fast as those that require a check in the mail.
Tracking and Categorizing Business Expenses
While invoicing is all about getting money in, tracking expenses is about understanding where it all goes. This isn't just about bookkeeping; it's about seeing your true profitability and making sure you claim every single tax deduction you're entitled to. It’s time to throw out that shoebox of crumpled receipts.
The magic really happens in the Bank Feed, which you connected during the initial setup. QuickBooks automatically pulls in every transaction from your linked business bank and credit card accounts. You'll find them waiting for you in the Banking tab. Your job is simply to review each one and tell QuickBooks where it belongs by assigning it to the right expense account from your Chart of Accounts.
This might sound a little tedious, but it’s an incredibly powerful habit. For example, when a charge from "Staples" pops up, you'll categorize it as Office Supplies. A payment to "Google" would likely be Advertising.
To make life even easier, you can create Bank Rules. Let's say you have a recurring monthly software subscription. You can set up a rule that tells QuickBooks to automatically categorize any transaction from that vendor as Software & Subscriptions. This one feature alone can save you hours of manual work every month.
What about those one-off cash purchases or times you had to use a personal card? You can add them manually, or even better, use the QuickBooks mobile app to snap a photo of the receipt. The app reads the key details and creates a transaction for you. To make sure you have solid documentation for every transaction, it helps to use well-designed sample business receipt templates.
This disciplined approach to expense tracking is a game-changer for new business owners. In fact, Intuit's 2025 data shows 88% of beginners who follow the tutorials master expense tracking and bank reconciliation within their first week. This slashes their manual entry errors by an incredible 72% compared to using spreadsheets.
Our firm has seen this firsthand. We’ve helped over 300 clients get their sales-tax management dialed in with QuickBooks, which cut their filing time by 65% and helped them avoid 90% of common penalties. You can learn more about these powerful QuickBooks findings from Intuit's own research.
Keeping Your Books Accurate With Bank Reconciliation
The phrase "bank reconciliation" might sound like high-level accounting jargon, but it's actually one of the most powerful and straightforward habits you can build as a new QuickBooks user. Think of it as simply checking your work.
You're comparing the transactions you’ve logged in QuickBooks against your official bank and credit card statements to ensure everything lines up perfectly. This isn’t a task to skip; it's the single most important monthly routine for guaranteeing your financial data is 100% accurate. It’s your safety net for catching everything from simple data-entry typos to duplicate charges or even fraud.
Why Reconciliation Is A Non-Negotiable Task
Honestly, without regular reconciliation, you can't truly trust the numbers your business is running on. Performing a monthly bank reconciliation gives you total confidence that every dollar is accounted for, which is critical for accurate tax filing and making sound business decisions.
Here's exactly what this monthly check-up does for you:
- Catches Bank Errors: Yes, banks make mistakes. Reconciliation helps you spot an incorrect charge or a missing deposit before it becomes a real headache.
- Identifies Missing Transactions: Did you forget to log that cash purchase for office supplies or an automatic software subscription? This process immediately brings those gaps to light.
- Prevents Fraud: Noticing a small, unfamiliar charge during reconciliation could be the first warning sign of fraudulent activity on your account, allowing you to shut it down fast.
- Ensures Accurate Reporting: When your accounts are reconciled, you know your Profit & Loss and Balance Sheet reports are built on solid, verified numbers.
Thankfully, modern software has made this process incredibly efficient. I’ve seen real estate investors take their reconciliation time from 10 hours a month down to just two by diligently tracking expenses. Global adoption for solopreneurs saw a 35% growth in 2025, driven largely by mobile apps that let you snap receipts on the go—a feature now used by 3.5 million people monthly. For a deeper dive, you can see how different industries are using these tools to save time in this video.
How To Complete Your First Reconciliation
Getting started is easier than you think. All you need is your bank or credit card statement for the month you want to reconcile.
In QuickBooks, head over to the Accounting tab and click Reconcile. First, you'll choose the correct account. Then, you’ll enter the ending balance and ending date exactly as they appear on your bank statement. This step is crucial—even a one-cent difference will keep your books from balancing.
Once you start, QuickBooks presents two lists side-by-side: one with all the transactions from your bank, and the other with everything you've entered into QuickBooks. Your job is to go down the list and check off each item that appears on both. As you do, you’ll see a "difference" counter at the top of the screen get smaller and smaller.
The goal is to get that difference to exactly $0.00. A zero difference is your proof that every single transaction on your bank statement has a matching entry in QuickBooks. Your books are officially balanced for that month.
But what happens if the numbers don't match? Don't panic. It happens to everyone, especially when you're just starting out. The problem is almost always one of these three things:
- A transaction was entered in QuickBooks with the wrong dollar amount.
- A transaction is on the bank statement but was never recorded in QuickBooks.
- A transaction was accidentally entered twice in QuickBooks.
Carefully review your statement against the unchecked items in QuickBooks to hunt down the discrepancy. Once you find and fix it, that difference will vanish. For more advanced troubleshooting, our complete guide on bank account reconciliation walks through more complex scenarios.
Turning Your Numbers Into a Real-World Business Strategy
Let's be honest: you probably didn't get into business because you love bookkeeping. You're here to build something. But all that work we've done setting up your books—the invoicing, the expense tracking—it all leads to this. This is where the numbers stop being just numbers and start telling you the story of your business.
QuickBooks reports are where your data entry pays off. They transform raw data into a clear picture of your company's health and performance. It can feel a little intimidating at first with all the options, so we're going to cut through the noise and focus on the three reports that matter most for any new business owner. Get a handle on these, and you'll have what you need to make smarter decisions.
The Profit & Loss: Are You Actually Making Money?
The first report you should get comfortable with is the Profit & Loss (P&L), which you might also hear called an Income Statement. It has one simple, powerful job: to tell you if you were profitable over a certain period. It answers that crucial question, "Did we make or lose money last month?"
The P&L works with a basic formula:
Income – Expenses = Net Income (Profit)
When you run this report in QuickBooks, you'll see all your income streams listed at the top, with all your expenses subtracted just below. The number at the very bottom is your net profit or loss for that period.
For example, a freelance photographer’s P&L might show $5,000 from wedding shoots and $2,000 from portrait sessions, giving them a total income of $7,000. Below that, they'd see expenses like $500 for software and $1,000 for advertising. The final line would show a net profit of $5,500 for the month. It’s that straightforward.
Think of your Profit & Loss as a performance review for your business. It tells you the story of your operations over time, showing you exactly where your money came from and where it went.
The Balance Sheet: What’s Your Business Worth Today?
If the P&L is a video of your business over time, the Balance Sheet is a snapshot. It gives you a clear picture of your company's financial health on a single day, telling you its net worth at that exact moment.
The entire report is built on one core accounting equation:
Assets = Liabilities + Equity
Put simply, this means everything your company owns (Assets) has to equal what it owes (Liabilities) plus the owner's stake in the company (Equity).
- Assets: This includes things like the cash in your bank accounts, your equipment, and any outstanding invoices owed to you.
- Liabilities: This covers things like credit card balances, business loans, and bills you haven't paid yet.
- Equity: This is the money you've personally invested, plus any profits the business has kept over time.
A healthy balance sheet shows that your assets are growing without your liabilities getting out of control. This is the report a bank will always ask for if you apply for a loan because it’s the ultimate proof of your company's stability.
The A/R Aging Report: Who Owes You Money?
While the P&L and Balance Sheet provide a high-level view, the Accounts Receivable (A/R) Aging report is all about your day-to-day cash flow. It's designed to answer one critical question: "Who owes me money, and how late are they on their payments?"
This report is incredibly practical. It lists all of your unpaid invoices and sorts them into columns based on how long they’ve been sitting there. You'll see categories like:
- Current: Invoices that haven't hit their due date yet.
- 1-30 Days Past Due: Recently late. Time for a gentle nudge.
- 31-60 Days Past Due: This is starting to become a problem.
- 61-90+ Days Past Due: These require your immediate attention.
I tell all my clients to get in the habit of running this report every single week. If you see a big invoice creeping into that "31-60 Days" column, you know it's time to stop sending polite emails and pick up the phone. This one report is your command center for managing cash flow, and it's the key to making sure small payment delays don't snowball into a serious cash crunch.
Common Questions We Hear from QuickBooks Beginners
As you start to navigate QuickBooks, you're bound to have some questions. That's completely normal. Getting a handle on these common queries right from the start will give you the confidence to use the software to its full potential.
Let's dive into some of the questions we get asked all the time.
Can I Use QuickBooks For My Personal Finances?
This one comes up a lot. While you technically could, QuickBooks is really built from the ground up for business accounting. It's packed with features for invoicing, tracking sales tax, and managing inventory—things that just don't apply to a typical household budget.
If you’re managing something complex, like a portfolio of rental properties, it might work. But for everyday personal finance, you’ll be much happier with a dedicated budgeting app that’s designed for that purpose.
What’s The Difference Between Online And Desktop?
Choosing between QuickBooks Online and Desktop is one of the first big decisions you'll make. QuickBooks Online is a cloud-based subscription service. You can access it from anywhere, on any device, which is a huge plus. It’s always up-to-date, and it makes collaborating with your bookkeeper or accountant seamless.
QuickBooks Desktop is the classic, installable software you buy outright and run on one computer. While it's still a powerful tool, QuickBooks Online is the modern standard for most businesses today. That flexibility and real-time access are why we focus on the Online version in this guide.
Choosing the right version isn't about which one is "better" but which one fits your business. For most people starting out, the convenience and automatic updates of QuickBooks Online make it the clear winner.
How Often Should I Be Updating My Books?
When it comes to bookkeeping, consistency is everything. To stay on top of things and avoid a mountain of work later, I always tell clients to log in at least once a week. Once you get into a groove, you can categorize all your new bank transactions in just 15-30 minutes.
Here's a simple rhythm to follow:
- Weekly: Reconcile your bank feed. This is your most important recurring task.
- As Needed: Send invoices as soon as the work is done. Don't wait.
- Monthly: Do a full bank and credit card reconciliation. This is non-negotiable for accurate financial reporting.
This simple routine ensures your financial data is always current, which means you can pull an accurate report whenever you need one. No more year-end panic.
I'm Using QuickBooks, So Do I Still Need An Accountant?
Yes, absolutely. This is probably the most critical question of all. Think of QuickBooks as a powerful tool for organizing all your financial data—but it's just that, a tool. It can't replace the strategic insight of a professional.
An accountant doesn't just do data entry; they interpret the data your QuickBooks file provides to offer high-level advice. They help with things like:
- Strategic Tax Planning: Actively finding ways to legally reduce your tax burden.
- Compliance Assurance: Making sure you're squared away with all federal, state, and local tax laws.
- Financial Advisory: Translating your reports into actionable insights to help you make smarter business decisions.
While this guide will get you running your own books, many business owners eventually see the real-world benefits of outsourcing accounting services. QuickBooks helps you prepare the ingredients perfectly; your accountant is the expert chef who creates the winning strategy.
Getting your books in order with QuickBooks is a fantastic first step toward financial clarity. But professional guidance is what turns that data into real growth. At Allied Tax Advisors, we take your well-managed QuickBooks file and use it to build tax strategies that help your business thrive. Contact us today to see how we can help.