
Real estate investing is as much about managing your tax obligations as it is about finding the right properties. The U.S. tax code, while complex, contains a robust suite of incentives specifically designed for property investors. Effectively leveraging these provisions is not just a year-end task; it's a core component of a profitable investment philosophy. The right real estate investment tax strategies can dramatically enhance your cash flow, accelerate equity growth, and reduce your overall tax burden, turning what would be a liability into a powerful tool for wealth creation.
This guide is designed to be a definitive resource, moving beyond surface-level advice to provide a detailed roundup of eight of the most impactful strategies available to investors today. We will dissect powerful techniques used by seasoned professionals to build and protect their portfolios. You will learn how to:
- Defer capital gains taxes, potentially indefinitely, using a 1031 Exchange.
- Maximize annual deductions through accelerated depreciation and cost segregation studies.
- Potentially offset your active income with rental losses by qualifying for Real Estate Professional Status (REPS).
- Explore tax-advantaged growth in designated Opportunity Zones.
Each section is structured to provide actionable insights, practical examples, and clear implementation steps. Whether you are scaling an extensive portfolio, managing your first rental, or exploring specialized approaches like the Short-Term Rental Loophole, this article will equip you with the knowledge to make more informed, tax-efficient decisions. Let’s dive into the strategies that can help you keep more of your returns and build a more resilient financial future.
1. Master the 1031 Exchange (Like-Kind Exchange) to Defer Taxes Indefinitely
Topping the list of powerful real estate investment tax strategies is the 1031 exchange, often called a "like-kind" exchange. Named after Section 1031 of the Internal Revenue Code, this provision allows investors to sell a business or investment property and reinvest the entire proceeds into a new, similar property, deferring all capital gains taxes. It's the cornerstone strategy for investors focused on scaling their portfolios, as it allows wealth to compound without the significant drag of a tax bill after each sale.
By deferring taxes, you keep your equity working for you, enabling you to acquire larger, more valuable, or better-performing assets. This could mean exchanging a single-family rental for a multi-unit apartment building, or trading an aging commercial space for a portfolio of newer properties. The key is that both the property you sell and the one you acquire must be held for productive use in a trade or business, or for investment.
The 1031 Exchange Timeline
The process is governed by strict, non-negotiable deadlines. Failure to meet these timelines will disqualify the exchange and trigger a taxable event. The following infographic breaks down the critical 45-day and 180-day rules that every investor must follow.
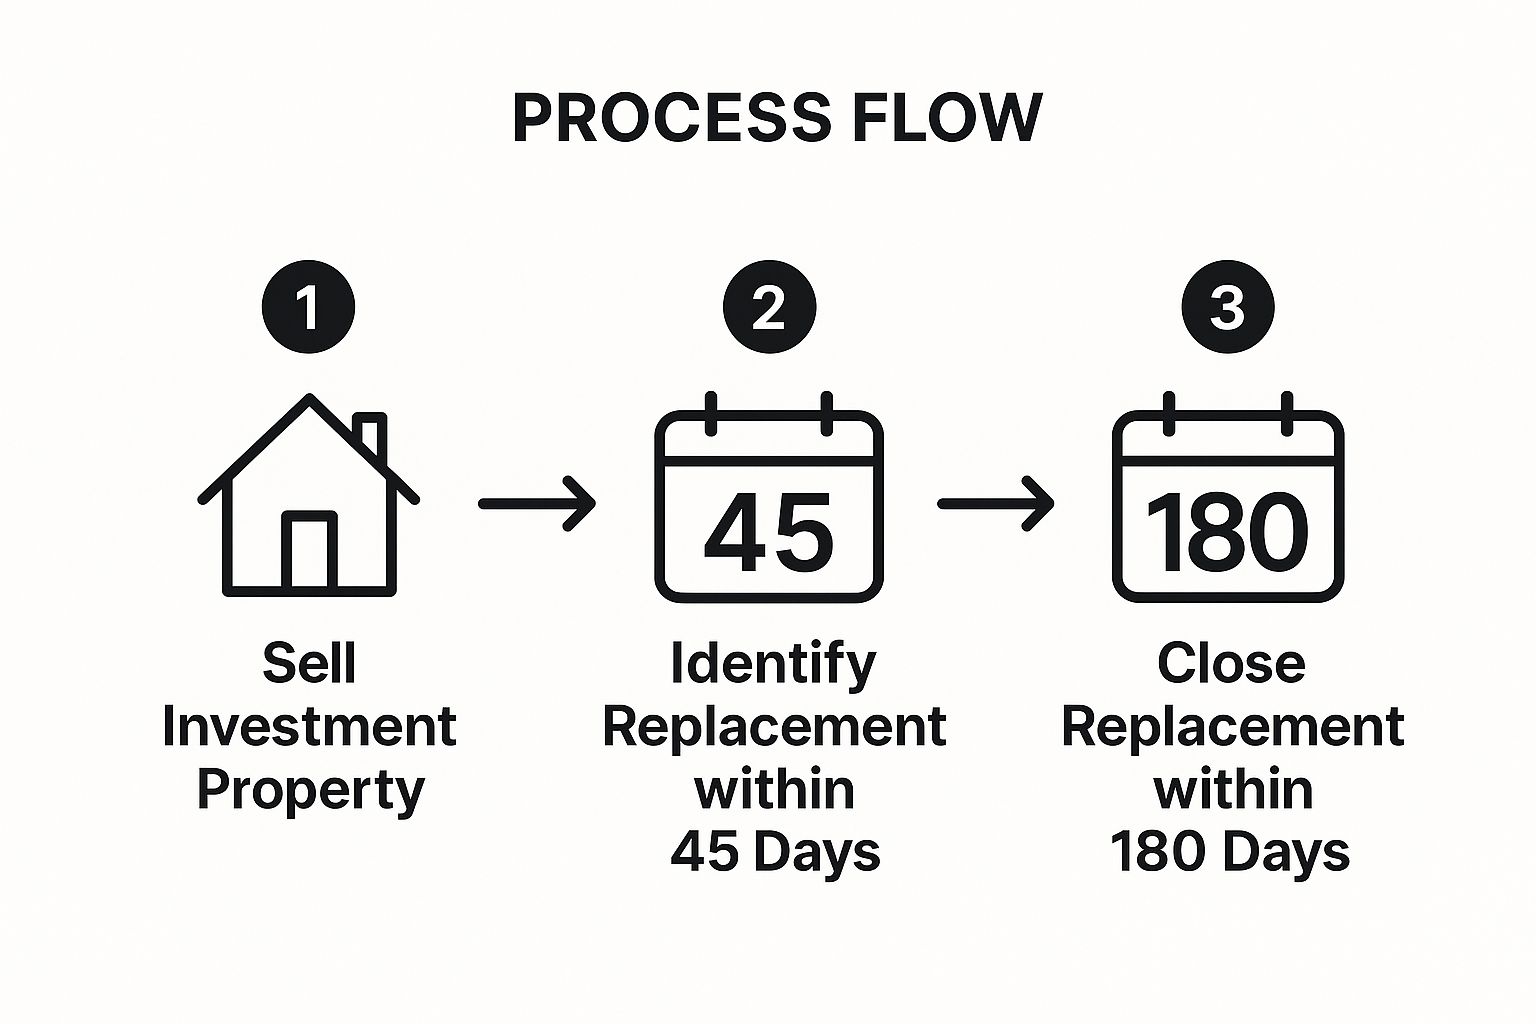
This process flow highlights that the clock starts the moment your original property sale closes, making upfront planning absolutely essential for a successful exchange.
Key Implementation Tips
To execute a 1031 exchange successfully, meticulous planning and adherence to rules are non-negotiable.
- Engage a Qualified Intermediary (QI): You cannot touch the sale proceeds. A QI must be engaged before your sale closes to hold the funds in escrow and facilitate the transaction.
- Identify Backup Properties: The 45-day identification window is short. Always identify at least one or two backup properties in case your primary choice falls through.
- Understand Debt and Equity: To fully defer taxes, you must acquire a replacement property of equal or greater value and replace any debt that was paid off on the relinquished property.
- Consider a DST: A Delaware Statutory Trust (DST) can be a useful backup option to ensure you meet your identification and closing deadlines, as it allows for fractional ownership in institutional-grade real estate.
Navigating these complexities requires expert guidance. You can learn more about the detailed rules and find out if a 1031 exchange is right for your portfolio by exploring what is a 1031 exchange with Allied Tax Advisors. Consulting with a tax professional and a QI early in the process is the best way to ensure compliance and maximize your tax deferral benefits.
2. Maximize Returns with Depreciation Deductions
One of the most valuable real estate investment tax strategies is depreciation. This powerful, non-cash deduction allows investors to write off the purchase price of an investment property over its IRS-determined useful life. It essentially lets you deduct the cost of the building (not the land, which doesn't depreciate) as an expense, creating a "phantom loss" that can significantly reduce your taxable income, even if the property generates positive cash flow.
Residential rental properties are depreciated over 27.5 years, while commercial properties have a 39-year lifespan. For example, if you purchase a rental home for $275,000 and the building's value is appraised at $225,000, you can deduct $8,182 annually ($225,000 ÷ 27.5). This deduction can turn a profitable investment into a tax loss on paper, directly lowering your tax bill without affecting your actual cash in hand.
This powerful mechanism allows you to shelter rental income and potentially other income streams, preserving more of your investment returns for future growth.
Key Implementation Tips
Properly implementing depreciation requires careful documentation and strategic planning to maximize its benefits and avoid common pitfalls.
- Properly Allocate Purchase Price: The initial purchase price must be allocated between the land and the building. Use a professional appraisal or the local property tax assessor's valuation to establish a defensible basis for the building.
- Consider a Cost Segregation Study: This engineering-based study identifies components of your property (like carpeting, fixtures, or landscaping) that can be depreciated over a much shorter period (5, 7, or 15 years) instead of 27.5 or 39 years. This accelerates your deductions, providing greater tax savings upfront.
- Plan for Depreciation Recapture: When you sell the property, the IRS "recaptures" the depreciation you claimed by taxing it at a rate of up to 25%. A 1031 exchange is a key strategy to defer this tax.
- Track Improvements Separately: Keep detailed records of all capital improvements, such as a new roof or HVAC system. These are depreciated separately based on their own useful lives, creating additional deductions.
Understanding the full scope of depreciation and other write-offs is crucial. You can explore a comprehensive list of tax deductions for real estate investors to ensure you are not leaving any money on the table. Consulting with a tax professional can help you optimize this strategy for your specific portfolio.
3. Implement a Cost Segregation Study to Accelerate Depreciation
Another highly effective real estate investment tax strategy is the cost segregation study. This is an engineering-based analysis that identifies and reclassifies a commercial or residential rental property's components into shorter depreciation periods. Instead of depreciating the entire building over 27.5 or 39 years, this study separates personal property and land improvements, which can be depreciated over much faster 5, 7, or 15-year schedules.
This accelerated depreciation creates substantial paper losses in the early years of property ownership, which can significantly reduce your taxable income and boost your immediate cash flow. For instance, a cost segregation study on a $2 million apartment building could identify $600,000 in assets eligible for accelerated depreciation, such as carpeting, specialized lighting, and cabinetry. This can generate massive first-year deductions, especially when combined with bonus depreciation rules.
The Power of Component Reclassification
The core principle of cost segregation is breaking down a property into its constituent parts to maximize tax savings. An engineering team meticulously evaluates everything from electrical wiring and plumbing to landscaping and parking lots, moving them from the long-term real property category to shorter-lived asset classes. This front-loads your depreciation deductions, freeing up capital that can be reinvested into your portfolio.
For example, a medical office owner might reclassify specialized HVAC systems and built-in equipment from a 39-year to a 5-year depreciation schedule, unlocking immediate tax benefits. The same applies to hotel owners who can accelerate depreciation on furniture, fixtures, and equipment (FF&E), which often constitute a large portion of the purchase price.
Key Implementation Tips
To leverage a cost segregation study effectively, precision and strategic timing are crucial.
- Act Early: The greatest benefit is realized when a study is performed in the first year of acquiring a property or completing construction.
- Use Specialists: Engage a reputable engineering firm that specializes in cost segregation and understands the IRS Audit Techniques Guide to ensure compliance.
- Combine with Bonus Depreciation: Pair the study with current bonus depreciation rules to potentially write off 100% of the cost of eligible components in the first year.
- File Form 3115 for Catch-Up: If you've owned a property for years, you can still benefit. File IRS Form 3115, "Application for Change in Accounting Method," to claim the missed depreciation from prior years without amending old tax returns.
This strategy is one of the most powerful tools for enhancing after-tax returns. Beyond the intricacies of cost segregation, savvy real estate investors also look to maximize business deductions through strategies like exploring equipment leasing tax benefits, including Section 179 deductions. To fully understand how this can impact your specific assets, you can explore the key benefits of a cost segregation study with Allied Tax Advisors. Consulting with tax professionals who can coordinate with engineering experts is the best path to maximizing your depreciation deductions.
4. Attain Real Estate Professional Status (REPS) to Unlock Unlimited Deductions
For high-income earners and active investors, achieving Real Estate Professional Status (REPS) is one of the most powerful real estate investment tax strategies available. This IRS designation, outlined in IRC Section 469, allows qualifying individuals to reclassify their rental property losses from "passive" to "non-passive." This critical distinction means you can deduct an unlimited amount of rental losses against your active income, such as W-2 wages, business profits, and other ordinary income streams.
Without REPS, rental losses are typically capped at $25,000 and phased out for higher earners, making them far less impactful. By qualifying as a real estate professional, you can use substantial paper losses generated from depreciation (especially when accelerated with a cost segregation study) to dramatically reduce your overall taxable income. For example, an investor who qualifies for REPS could use $150,000 in rental property losses to directly offset their spouse's $200,000 salary, leading to massive tax savings.
Qualifying for REPS and Implementation
Meeting the strict IRS requirements for REPS is challenging and requires meticulous documentation. To qualify, you must satisfy two primary tests during the tax year: the 750-hour test and the more-than-50% test. This means you must spend over 750 hours and more than half of your total working hours on real property trades or businesses.
Key Implementation Tips
Successfully claiming REPS requires diligent record-keeping and a proactive approach to managing your real estate activities.
- Track Your Hours Meticulously: Keep a contemporaneous log of all real estate-related activities. Use a calendar, spreadsheet, or time-tracking app to document every hour spent on management, research, property visits, and tenant communications.
- Meet Material Participation Rules: Qualifying for REPS is only half the battle. You must also "materially participate" in your rental activities. Consider making a "grouping election" to combine all your rental properties into a single activity to make this requirement easier to meet.
- Strategize as a Couple: Often, the most effective strategy is for one spouse to focus on meeting the REPS requirements while the other maintains their W-2 job. This allows the couple to use the real estate losses to offset the other spouse's high income.
- Combine with Cost Segregation: The true power of REPS is unleashed when paired with a cost segregation study. This combination can generate significant paper losses through accelerated depreciation, creating substantial deductions to offset your active income.
Given the complexity and high audit risk associated with this status, consulting with a specialized real estate CPA is essential. Professionals like those at The Real Estate CPA can provide guidance on documentation, material participation, and overall strategy to ensure you qualify and can defend your position if challenged by the IRS.
5. Utilize Opportunity Zone Investing for Powerful Tax Incentives
A modern and potent tool among real estate investment tax strategies is investing in Opportunity Zones. Established by the Tax Cuts and Jobs Act of 2017, this program incentivizes long-term investments in economically distressed communities designated as Qualified Opportunity Zones (OZs). By reinvesting capital gains into a Qualified Opportunity Fund (QOF), which then invests in these zones, investors can access a powerful trifecta of tax benefits designed to spur economic growth while rewarding patient capital.
This strategy is particularly attractive for investors with significant capital gains from the sale of any asset, not just real estate. For instance, a tech executive who sells appreciated stock can roll that gain into a QOF focused on multifamily development, deferring the initial tax liability and positioning themselves for future tax-free growth. The goal is to channel private investment into areas that need it most, creating a win-win for communities and investors alike.
The three primary tax benefits are what make this program so compelling. First, you can defer paying taxes on your original capital gain until as late as December 31, 2026. Second, if you held the investment long enough before the program's deadlines, a step-up in basis could reduce that deferred gain. The most significant benefit is that if you hold the QOF investment for at least 10 years, any capital gains from the appreciation of that investment are permanently eliminated and become 100% tax-free.
Key Implementation Tips
Successfully leveraging Opportunity Zones requires careful planning and a long-term perspective. Adherence to strict rules is critical to securing the tax advantages.
- Mind the 180-Day Window: The clock starts on the date of your capital gain event. You have 180 days to invest the proceeds into a Qualified Opportunity Fund.
- Verify Economic Viability: Not all Opportunity Zones are created equal. Thoroughly research the underlying economic fundamentals of a zone to ensure your investment has strong growth potential beyond just the tax benefits.
- Understand 'Substantial Improvement': QOFs acquiring existing properties must substantially improve them, generally meaning the fund must invest at least as much in improvements as it paid for the building. This often favors ground-up construction or major renovation projects.
- Partner with Experienced Sponsors: Consider investing through established QOF sponsors with a proven track record in real estate development and navigating OZ regulations.
- Plan for a 10-Year Hold: The most significant benefit, the tax-free growth of your OZ investment, only materializes after holding the investment for a minimum of 10 years.
To navigate the complexities of this powerful program, consulting with a tax professional specializing in real estate is essential. They can help you align a capital gains event with a suitable QOF investment and ensure you meet all IRS compliance requirements, such as filing Form 8996 and Form 8997.
6. Self-Directed IRA Real Estate Investing
Another powerful, though often overlooked, real estate investment tax strategy involves using a Self-Directed IRA (SDIRA). Unlike traditional IRAs that are typically limited to stocks, bonds, and mutual funds, an SDIRA gives you the freedom to invest your retirement funds directly into alternative assets like real estate. This allows you to combine the tax-advantaged growth of an IRA with the tangible wealth-building potential of property ownership.
With an SDIRA, your retirement account legally owns the investment property. All income, such as rental payments, flows directly back into the IRA, and all expenses, like maintenance and property taxes, are paid from it. The primary benefit is the tax treatment: in a Traditional SDIRA, profits grow tax-deferred, while in a Roth SDIRA, qualified withdrawals of all profits are entirely tax-free. This strategy transforms your real estate ventures into a tax-efficient retirement-building machine.
Leveraging Retirement Funds for Real Estate
The SDIRA framework opens up diverse investment opportunities that would otherwise be funded with post-tax dollars. Imagine using your Roth IRA to purchase a rental property; after years of collecting rent and appreciation, you could sell it and withdraw the entire proceeds in retirement without paying a dime in taxes. Similarly, a Traditional SDIRA could be used to invest in a high-yield tax lien or act as a private lender, with all interest income compounding on a tax-deferred basis.
For self-employed individuals, a Solo 401(k) offers even greater flexibility, with higher contribution limits and the potential to take out a loan against your account balance, a feature not available with IRAs. These specialized accounts are a cornerstone for savvy investors aiming to maximize long-term, tax-advantaged growth.
Key Implementation Tips
Successfully investing in real estate with an SDIRA requires strict adherence to IRS rules to avoid severe penalties.
- Choose the Right Custodian: Work with a custodian that specializes in self-directed accounts and has extensive experience with real estate transactions. Companies like Equity Trust Company and IRA Financial Group are well-versed in this area.
- Understand Prohibited Transactions: You and other "disqualified persons" (like your spouse, children, or parents) cannot personally benefit from the IRA-owned property. This means you cannot live in it, perform maintenance on it, or personally use its income.
- Maintain Sufficient IRA Liquidity: Your SDIRA must have enough cash reserves to cover all property-related expenses, including taxes, insurance, repairs, and vacancies.
- Keep Meticulous Records: All transactions must be kept strictly separate from your personal finances. Every dollar of income and expense must flow through the SDIRA account.
- Beware of UBIT: If you use a non-recourse loan to finance an SDIRA property, a portion of the income may be subject to Unrelated Business Income Tax (UBIT), which can be complex to navigate.
7. Exploit the Short-Term Rental (STR) Tax Loophole
One of the most powerful and modern real estate investment tax strategies is the Short-Term Rental (STR) loophole. This strategy allows investors to bypass the typical passive activity loss limitations that govern most rental properties. By doing so, investors can use paper losses from their STRs, often generated through depreciation, to offset their active income from a W-2 job or business.
The key to this strategy lies in meeting two specific IRS criteria: the average guest stay in your property must be 7 days or less, and you, the owner, must provide "substantial services" comparable to those offered by a hotel. When these conditions are met, the rental activity is reclassified from passive to non-passive, unlocking the ability to deduct losses against other active income streams without needing to qualify for Real Estate Professional Status (REPS).
Understanding the Mechanics
Unlike traditional long-term rentals where losses are typically suspended, the STR loophole recharacterizes the activity. This makes it an incredibly effective tool for high-income earners looking to dramatically reduce their tax liability. For example, an investor could purchase a beach condo, ensure average stays are under 7 days, provide concierge and cleaning services, and then use a cost segregation study to accelerate depreciation. The resulting six-figure paper loss can then directly reduce their taxable W-2 or business income.
Key Implementation Tips
Proper execution and documentation are critical to successfully and legally utilizing the STR loophole.
- Document Average Stay: Meticulously track and calculate the average length of stay for all guests throughout the year to ensure it remains 7 days or less.
- Provide Substantial Services: Go beyond standard landlord duties. Offer services like regular cleaning, concierge services, guest assistance, or providing meals and amenities that enhance the guest experience.
- Achieve Material Participation: You must "materially participate" in the activity. The clearest path is to document over 500 hours of personal involvement in managing the property, handling bookings, and providing services.
- Combine with Cost Segregation: To maximize the tax benefit, pair this strategy with a cost segregation study and bonus depreciation. This front-loads your depreciation deductions into the first year, creating a massive paper loss to offset income.
This is an advanced strategy that requires careful planning and flawless record-keeping. To ensure you meet all the necessary requirements and properly defend your position in the event of an audit, consulting with a CPA specializing in short-term rental taxation is highly recommended.
8. Utilize the Primary Residence Exclusion (Section 121) for Tax-Free Gains
One of the most accessible and powerful real estate investment tax strategies is baked directly into the tax code for homeowners. Section 121 allows individuals to exclude up to $250,000 (or $500,000 for married couples filing jointly) of capital gains from the sale of their primary residence. This provision transforms a personal home into a potent wealth-building tool, enabling savvy investors to generate significant tax-free profits.
This strategy is particularly effective for those engaged in "house hacking" or "live-in flips." By purchasing a property, living in it as their main home while making improvements, and then selling it after the minimum time requirement, investors can pocket the appreciation without a tax bill. The core requirement is that you must have owned and used the home as your principal residence for at least two of the five years leading up to the sale. This two-year period does not need to be continuous.
Qualifying for the Full Exclusion
To leverage this benefit, you must meet the ownership and use tests. For example, a married couple could buy a fixer-upper for $400,000, invest $50,000 in renovations, and live in it for two years. If they sell it for $950,000, their entire $500,000 gain is excluded from capital gains tax. This allows them to roll that entire tax-free profit into their next investment, dramatically accelerating portfolio growth.
While the two-year rule is central, there are exceptions. Understanding the full scope of these rules is key, especially the implications of selling a house before 2 years, which may qualify you for a partial exclusion under specific circumstances like a job change or health issues.
Key Implementation Tips
Proper planning and documentation are essential to successfully claim the Section 121 exclusion.
- Document Your Primary Residence: Maintain clear records proving the property was your main home. This includes utility bills, voter registration, and updating your address on your driver's license.
- Track Your Basis: Keep meticulous records of all capital improvements made to the property. These costs increase your adjusted basis, which in turn reduces your calculated capital gain when you sell.
- Time Your Sale: Plan your sale to occur only after you have met the two-year ownership and use requirements to maximize your tax-free gains.
- Convert Rentals Strategically: You can convert a rental property into your primary residence to qualify. However, be aware that any depreciation you claimed during the rental period will be "recaptured" and taxed upon sale.
Real Estate Tax Strategy Comparison
| Strategy | Implementation Complexity 🔄 | Resource Requirements ⚡ | Expected Outcomes 📊 | Ideal Use Cases 💡 | Key Advantages ⭐ |
|---|---|---|---|---|---|
| 1031 Exchange (Like-Kind) | High: Strict timelines, qualified intermediary required | Moderate: Requires professional facilitation | Tax deferral of capital gains indefinitely; portfolio upgrading without taxes | Investors selling investment real estate wanting tax deferral and portfolio flexibility | Defers taxes indefinitely; preserves capital; allows diversification/consolidation |
| Depreciation Deductions | Low to Moderate: Ongoing recordkeeping, tax reporting | Low: Automatic with rental properties | Reduces taxable income via non-cash deductions; lowers tax burden while holding property | Rental property owners seeking regular income tax reduction | Reduces taxable income without cash outflow; offsets rental income |
| Cost Segregation Study | High: Engineering study and complex tax return | Moderate to High: Study costs $5k-$15k+ | Accelerated depreciation deductions for large upfront tax savings | Owners of expensive or newly acquired properties looking to maximize early tax benefits | Significant upfront deductions; improves early cash flow; catch-up depreciation |
| Real Estate Professional Status | High: Requires 750+ hours annually and strict documentation | High: Significant time commitment | Unlimited deduction of rental losses against ordinary income | High-income earners actively managing real estate activities | Unrestricted rental loss deductions; enables aggressive tax planning |
| Opportunity Zone Investing | Moderate to High: Compliance, timing, reporting | Moderate: Capital gain reinvestment required | Deferral, partial reduction, and potential exclusion of capital gains | Investors with capital gains seeking long-term tax-advantaged investments in distressed areas | Defers and reduces taxes; permanent gain exclusion after 10 years |
| Self-Directed IRA Investing | High: Strict prohibited transaction rules, custodian required | Moderate to High: Custodian fees, cash reserves | Tax-deferred or tax-free real estate growth inside retirement account | Investors wanting retirement funds invested directly in real estate | Tax-advantaged growth; diversification beyond stocks; control over investments |
| Short-Term Rental Tax Loophole | High: Must meet short-term rental, service, and participation rules | Moderate to High: Intensive management | Rental losses can offset active income without REPS | Owners of short-term/vacation rentals providing substantial services | Converts passive activity losses to non-passive; offsets ordinary income |
| Primary Residence Exclusion | Low: Simple documentation and ownership/use tests | Low: Personal use required | Excludes up to $250k/$500k capital gains tax on home sale | Homeowners selling primary residence every 2+ years | Large tax-free gains; repeatable every 2 years; simple to claim |
Putting It All Together: Building Your Tax-Smart Investment Blueprint
Navigating the intricate landscape of real estate tax law can feel overwhelming, but mastering its rules unlocks unparalleled financial advantages. The powerful strategies we've explored, from deferring capital gains with a 1031 Exchange to accelerating write-offs via a Cost Segregation Study, are not just isolated tactics. They are interconnected components of a comprehensive wealth-building machine.
Think of each strategy as a specialized tool. Depreciation is your foundational workhorse, consistently reducing your taxable income year after year. Achieving Real Estate Professional Status (REPS) or leveraging the Short-Term Rental (STR) Loophole are your power tools, enabling you to offset active income with passive losses. Meanwhile, Opportunity Zones and Self-Directed IRAs are strategic levers for long-term, tax-advantaged growth.
The ultimate goal is to move beyond viewing taxes as a simple year-end obligation. Instead, you must learn to see them as a dynamic framework of incentives designed to encourage specific economic activities, including providing housing and developing communities. By aligning your investment activities with these incentives, you transform a financial liability into a strategic asset.
From Theory to Action: Your Next Steps
The difference between a good investor and a great one often lies in implementation. Reading about these strategies is the first step, but applying them correctly is what generates real returns. The most successful investors understand that the IRS values precision and documentation above all else. A misstep in a 1031 exchange timeline or an improperly substantiated claim for REPS can unravel years of careful planning.
Here are your actionable next steps to integrate these concepts:
- Audit Your Portfolio: Review your current holdings. Which properties are prime candidates for a cost segregation study? Are you approaching the threshold for long-term capital gains, making a 1031 exchange a timely consideration?
- Track Your Time Meticulously: If you are pursuing REPS or the STR loophole, begin logging your hours now. Use a spreadsheet or a dedicated app to document every material participation activity, from tenant screening to property maintenance.
- Consult with Professionals Before You Act: The most costly mistakes happen when investors act first and seek advice later. Before you sell a property, make a major capital improvement, or change its use, consult with a tax professional who specializes in real estate.
The True Value of Strategic Tax Planning
Mastering these real estate investment tax strategies is about more than just saving money on your annual tax bill. It's about fundamentally altering your financial trajectory. The capital you save through strategic depreciation is capital you can reinvest into another down payment. The gains you defer with a 1031 exchange allow your portfolio to scale exponentially without the drag of taxation.
This proactive approach to tax planning creates a powerful compounding effect. It increases your cash flow, protects your equity, and accelerates the timeline to achieving your financial goals. By building a tax-smart blueprint, you are not just managing expenses; you are actively engineering a more resilient, profitable, and enduring real estate empire. The path to sophisticated investing begins with a commitment to tax intelligence.
Don't navigate this complex terrain alone. The experts at Allied Tax Advisors specialize in crafting bespoke tax plans for real estate investors just like you, ensuring you maximize every available deduction and credit while maintaining full compliance. Schedule a consultation with our team at Allied Tax Advisors today to start building your personalized, tax-efficient investment future.