
Welcome to your essential guide on turning rental expenses into powerful tax savings. If you’re a landlord, getting a handle on tax deductions is one of the most important things you can do for your bottom line. It’s the key to maximizing your property’s profitability.
At its core, a rental property tax deduction is simply an expense you incur while managing your property. The IRS allows you to subtract these costs from the rental income you collect, which lowers the amount of income you ultimately pay taxes on. This guide will walk you through everything, from the most common write-offs to more advanced strategies that can save you a bundle.

Turning Expenses Into Tax Savings
It helps to think of your rental property less like a passive asset and more like a small business. And just like any business, it has operating costs. The great news is that the IRS lets you deduct the “ordinary and necessary” expenses that come with running it. This doesn’t mean you get a dollar-for-dollar refund. Instead, it shrinks your taxable profit, which in turn lowers your overall tax bill.
Mastering this concept is a cornerstone of any smart real estate investment strategy. When you diligently track and claim every legitimate deduction, you ensure you’re not paying a penny more in tax than you legally have to. It’s all about keeping more of your hard-earned money in your pocket, where you can reinvest it or use it to grow your portfolio.
The Big Picture on Deductions
Before we jump into a long list of specific write-offs, it’s really important to understand the two main flavors of expenses you’ll run into as a landlord. First, you have the day-to-day costs of keeping the property in good shape and rented out—things like routine repairs or paying the water bill. These are generally deducted in full in the same year you pay for them.
The second category is for major upgrades that add significant value or extend the life of your property, which the IRS calls capital improvements. Think of a new roof or a full kitchen remodel. These are handled quite differently through a powerful tax tool called depreciation. Our comprehensive https://alliedtax.com/ultimate-guide-to-taxes-on-investment-property/ offers more detail on these foundational principles.
The core idea is simple: every legitimate dollar you spend to earn rental income can potentially reduce your tax liability. The secret is knowing what qualifies and how to document it properly.
To give you a clear starting point, let’s break down the most common and impactful deductions available to rental property owners.
Top Rental Property Tax Deductions at a Glance
Here’s a quick overview of the key expense categories you’ll want to track meticulously throughout the year. Think of this as your cheat sheet. We’ll dive much deeper into each of these in the sections that follow.
| Deduction Category | What It Covers | Typical Example |
|---|---|---|
| Mortgage Interest | Interest paid on the loan used to buy the property. | The interest portion of your monthly mortgage payment. |
| Property Taxes | State and local taxes assessed on your property. | Your annual property tax bill from the county. |
| Insurance | Premiums for policies protecting your property. | Landlord liability, fire, and flood insurance. |
| Repairs & Maintenance | Costs to keep the property in good working condition. | Fixing a leaky pipe or replacing a broken window. |
| Depreciation | A non-cash deduction for the property’s wear and tear. | Deducting the value of the building over 27.5 years. |
| Operating Expenses | Day-to-day costs to manage the rental. | Utilities, landscaping, advertising, and HOA fees. |
This table covers the heavy hitters, but the list of potential deductions doesn’t stop here. Diligent record-keeping is your best friend when it comes to maximizing these benefits at tax time.
Mastering the Core Landlord Deductions
To really get a handle on lowering your taxable rental income, you have to know the foundational deductions inside and out. These are the regular, unavoidable costs of simply owning and running a rental property. Think of them as the “big four” pillars of your deduction strategy: mortgage interest, property taxes, insurance, and the everyday operating expenses.
Let’s dig into each one to build a solid base for your tax planning.
These core deductions are the bedrock of your tax savings because they’re almost always your biggest and most predictable expenses. Getting these right isn’t just a good idea—it’s essential for filing an accurate tax return.
Mortgage Interest: Your Most Significant Write-Off
For the vast majority of landlords, the interest you pay on your mortgage is the single largest deduction you can claim. The key here is to remember you can only deduct the interest portion of your payment, not the part that goes toward the principal and builds your equity.
Your lender makes this pretty easy for you. Every year, they’ll send a Form 1098, Mortgage Interest Statement, which clearly spells out the exact amount of interest you paid. If you happened to use some of the loan money for personal reasons, you can only deduct the interest that corresponds to the rental property itself.
Key Insight: A common rookie mistake is to confuse the total mortgage payment with the deductible interest. Only the number on your Form 1098 counts as a direct deduction against your rental income.
Property and Other Taxes
The state and local taxes you pay on the property are another huge expense you can fully deduct. This is mainly the property tax bill from your county or city, but it can also include other non-federal taxes you pay as part of running your rental business.
Here’s a crucial point that trips people up: the $10,000 SALT cap. While this cap limits what you can deduct for state and local taxes on your personal return (Schedule A), it does not apply to your rental business reported on Schedule E. That’s great news, as it means you can deduct every penny of your rental’s property taxes without limitation.
Protecting Your Investment with Insurance
The premiums for any insurance policy on your rental property are 100% deductible. The IRS views these as ordinary and necessary costs of doing business because they protect your valuable asset from all sorts of potential disasters.
Common types of deductible insurance include:
- Landlord Insurance: This is your primary policy, covering property damage, liability, and even lost rental income.
- Fire and Theft Policies: Covers the physical structure and any of your assets inside.
- Flood Insurance: Often a separate policy, and fully deductible if you have it.
- Liability Insurance: Protects your personal finances from lawsuits if someone is injured on the property.
Make sure to keep good records of every premium payment. They add up quickly and can make a real dent in your tax bill.
Tracking Day-to-Day Operating Expenses
Beyond those big three, a whole host of smaller, day-to-day costs are needed to keep your property in good shape and occupied. These are called operating expenses, and every single one is a valuable tax deduction.
This broad category covers a lot of ground:
- Utilities: Any water, sewer, trash, or gas bills you pay for the property.
- HOA Fees: Condo or homeowners’ association fees are fully deductible.
- Landscaping and Maintenance: Costs for lawn care, snow removal, and general upkeep.
- Management Fees: If you hire a property management company, their fee is a direct business expense.
The tax code is set up this way for a reason—to encourage real estate investment by allowing landlords to offset their income with the real costs of running the business. If you want to dive deeper, you can always review the rental real estate tips from the IRS for more official guidance.
Unlocking Your Largest Deduction With Depreciation
Of all the tax write-offs available to landlords, one is more powerful—and more misunderstood—than all the others combined. I’m talking about depreciation. It’s your single largest deduction, yet it’s a “non-cash” expense, meaning you get a massive tax break without spending a dime in the current year.
Think of it this way: your rental property is like a new work truck. The moment you drive it off the lot, it starts aging. Even if you aren’t actively spending money on repairs, the engine is working, the tires are wearing down, and its value is slowly decreasing. The IRS lets you write off this gradual wear and tear, giving you a substantial tax deduction that reflects the property’s declining lifespan.
This is a game-changer for real estate investors. By claiming depreciation, you lower your net rental income on paper, which directly slashes your tax bill. Getting a handle on how to calculate and claim it is one of the most fundamental skills you can develop.
Calculating Your Depreciation Deduction
The IRS has a very specific formula for this. For any residential rental property, you get to depreciate the value of the building—but not the land, since land doesn’t wear out—over a set period of 27.5 years. It’s a straightforward, systematic way to get a predictable deduction every single year.
First things first, you need to figure out your property’s cost basis. This isn’t just the price you paid; it also includes other costs you incurred to get the property ready for service.
Your cost basis usually includes:
- The purchase price you agreed to.
- Settlement fees and closing costs that you can’t deduct elsewhere, like legal fees, recording fees, and title insurance.
- The cost of surveys and abstract fees.
Once you have that total number, you have to do one more crucial step: separate the value of the land from the value of the building itself. You can only depreciate the structure. A good way to find this split is by looking at your property tax assessment or getting a formal appraisal. From there, you just divide the building’s value by 27.5 to find your annual write-off.
Let’s walk through an example:
- You buy a rental house for $350,000.
- Closing costs add another $10,000, bringing your total basis to $360,000.
- Your tax assessment says the land is worth $90,000.
- That leaves a depreciable basis for the building of $360,000 – $90,000 = $270,000.
- Your annual depreciation deduction is $270,000 / 27.5 years = ~$9,818 per year.
This powerful deduction can easily turn a property that’s making positive cash flow into a loss on paper, effectively shielding that income from taxes. If you want to dive deeper into the nuts and bolts, you can explore the specifics of rental property depreciation in our detailed guide.
The Other Side of the Coin: Depreciation Recapture
While depreciation is an incredible tool during the years you own the property, there’s a catch when you decide to sell. It’s called depreciation recapture, and if you’re not prepared for it, you could be in for a nasty tax surprise.
Think of it as the IRS saying, “We let you take those deductions to lower your taxes every year. Now that you’re selling and cashing out, it’s time to pay some of that back.”
Here’s how it works. Every dollar of depreciation you claim lowers your property’s cost basis. When you sell, your profit (capital gain) is the sale price minus this new, lower basis. The government then “recaptures” the depreciation you took by taxing that portion of the gain at a special rate—up to a maximum of 25%. This is typically higher than the long-term capital gains rates, so it’s something you need to plan for.
This is why experienced investors view depreciation as a tax deferral strategy. The tax code allows you to write off a residential property over 27.5 years, which is an annual deduction of about 3.636%. You get to postpone paying taxes for years, but the bill eventually comes due at the sale. That’s when all the depreciation you’ve claimed over the years is taxed, up to that 25% cap.
Distinguishing Repairs from Capital Improvements
Is fixing a leaky faucet the same as installing a brand-new roof in the eyes of the IRS? Not even close. This distinction is one of the most critical—and commonly misunderstood—areas of rental property taxes, and getting it wrong can be a costly mistake.
Getting this right is fundamental to your bookkeeping and overall tax strategy. The IRS treats these two types of expenses in completely different ways, directly impacting how much tax you pay each year. When you classify each expense correctly, you not only maximize your legitimate deductions but also avoid the kind of red flags that can trigger a painful audit.
Defining Repairs: An Immediate Deduction
The IRS views a repair as any expense that simply keeps your property in good working order. Think of these as routine maintenance. They don’t really add to the property’s value or extend its life in a meaningful way; they just put things back the way they were.
Because repairs are considered “ordinary and necessary” business expenses, you get to deduct their full cost in the same year you pay for them. This gives you an immediate financial benefit by lowering your taxable rental income right away.
Here are a few classic examples of deductible repairs:
- Fixing a leak under the kitchen sink
- Replacing a single broken windowpane
- Repainting a room after a tenant moves out
- Repairing a broken appliance, like a dishwasher
- Mending a small patch of damaged drywall
These jobs just maintain the property, making sure it stays safe and functional for your tenants. They don’t fundamentally change its character or boost its market value.
Understanding Capital Improvements: A Long-Term Benefit
A capital improvement, on the other hand, is a much bigger deal. This is an expense that adds significant value to your property, substantially prolongs its useful life, or adapts it for a new use. The IRS sees these not as simple fixes, but as long-term investments in your asset.
Because of this, you can’t just write off the entire cost in one go. Instead, you have to capitalize the expense. This means you recover the cost gradually over time through a process called depreciation, spreading the tax deduction out over the asset’s “useful life.”
The infographic below shows how depreciation schedules differ for residential and commercial properties, which is a core concept when dealing with capital improvements.
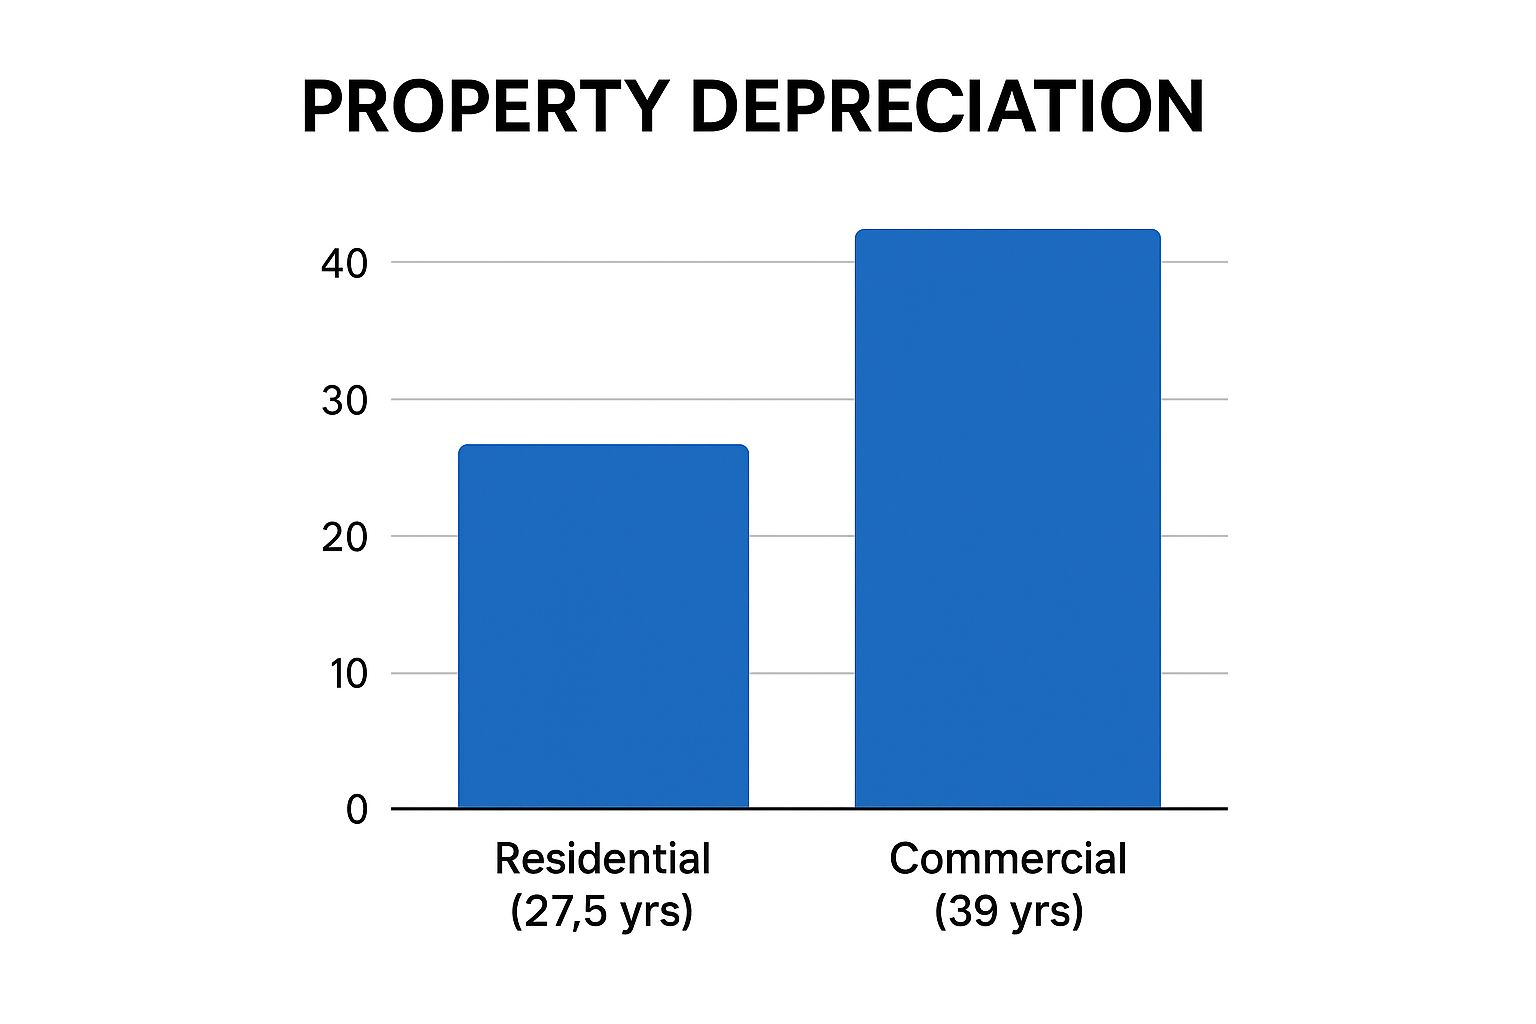
As you can see, residential rental properties are depreciated over 27.5 years. Commercial properties get a longer, 39-year schedule. This difference shows how the IRS assigns distinct useful lifespans to different types of real estate assets.
Repairs vs. Improvements: Which Is Which?
The line between a repair and an improvement can sometimes feel a bit blurry. The best way to tell them apart is to ask yourself one simple question: “Did this expense restore something, or did it upgrade it?” A brand-new roof is a clear improvement because it extends the life of the entire building. Patching a few shingles on that same roof? That’s just a repair.
To make it even clearer, here’s a quick comparison table to help you sort your expenses.
| Expense Type | Definition | Tax Treatment | Example |
|---|---|---|---|
| Repair | Maintains the property’s current condition; a fix. | Deduct immediately in the current tax year. | Fixing a running toilet. |
| Improvement | Adds value, prolongs life, or adapts the property. | Capitalize and depreciate over many years. | A complete bathroom remodel. |
The context of the expense really matters. One small job might be a repair on its own, but if it’s part of a much larger project, the IRS will likely view the whole thing as one big capital improvement.
Key Takeaway: If you replace a single faulty light fixture, that’s a repair. But if you replace all the light fixtures as part of a complete kitchen remodel, the cost of the fixtures gets bundled into the overall improvement project and must be depreciated.
Uncovering the Tax Deductions Most Landlords Miss
Every landlord knows to write off the big-ticket items like mortgage interest and property taxes. But what about the smaller, less obvious expenses? This is where savvy investors really pull ahead, because those “small” deductions can add up to thousands of dollars in savings each year.
Are you tracking every single trip you make to your property? The fees you paid your accountant? These are all legitimate business expenses. Think of it this way: every dollar you can legally deduct is a dollar that stays in your pocket. Let’s dig into the hidden gems of the tax code that can seriously boost your returns.
Mastering these often-overlooked write-offs is what separates a good investment from a great one.
Writing Off Travel to Your Property
If you jump in your car to collect rent, deal with a repair, or show the unit to a potential tenant, that’s a business trip. The IRS recognizes this and allows you to deduct those transportation costs. You have two ways to do this.
The first is the actual expenses method, where you track every penny spent on gas, oil changes, repairs, and even a portion of your car’s depreciation. It’s thorough but requires meticulous bookkeeping. The easier path for most is the standard mileage rate. For 2024, this rate is a straightforward 67 cents per mile. Just multiply the business miles you drove by that rate, and you’ve got your deduction.
A word of caution: You can’t just estimate your mileage. The IRS requires a detailed log showing the date, mileage, and purpose of each trip. This isn’t optional—it’s your proof if you’re ever audited.
Deducting Professional and Legal Fees
Did you pay a lawyer to look over your lease agreement? Or an accountant to handle your Schedule E? Good news—those fees are 100% deductible business expenses.
This bucket of deductions can include a surprising number of things:
- Tax Preparation and Advice: Any fees you pay a CPA or tax professional for help specifically related to your rental business.
- Legal Services: The cost of an eviction, contract review, or even setting up an LLC to hold your properties.
- Property Management Software: Those monthly or annual subscriptions to keep your business organized are also a write-off.
These costs are considered “ordinary and necessary” for running your rental business, so make sure you track them. To see how these fees fit into your overall tax situation, check out our complete guide to the tax on rental income.
Claiming the Home Office Deduction
If you have a dedicated space in your home that you use exclusively and regularly to manage your rental properties, you might be able to claim the home office deduction. This lets you deduct a percentage of your home’s expenses, such as mortgage interest, insurance, utilities, and repairs.
Key Rule: The key word here is “exclusively.” This can’t be a corner of the family room where you also watch TV. It has to be a space—a spare room, a desk area—used solely for your rental business activities.
There are two ways to calculate it. The regular method involves complex calculations based on actual expenses. The much simpler option allows you to deduct $5 per square foot of your home office, up to a maximum of 300 square feet. That’s a potential deduction of up to $1,500.
Unlocking the Qualified Business Income (QBI) Deduction
Here’s one of the most powerful—and most frequently missed—deductions available to landlords. The Qualified Business Income (QBI) deduction, created by the Tax Cuts and Jobs Act of 2017, can be a game-changer.
If you qualify, you can deduct up to 20% of your net rental income right off the top. It’s not just a deduction against your rental income; it lowers your overall taxable income. For example, if you have $20,000 in net rental income, the QBI deduction could slash your taxable income by $4,000. It’s a huge benefit that you shouldn’t leave on the table.
Your Blueprint for Tax Time Success
Knowing which deductions you can take is one thing. Actually getting them is another. Winning at tax time isn’t about finding some secret loophole; it’s about having a solid system in place long before you ever sit down to file. Let’s walk through a practical blueprint to make tax season less stressful, keep you compliant, and ensure you’re always ready if the IRS comes knocking.
The absolute cornerstone of a strong tax strategy is clean record-keeping. The single best thing you can do right now? Open a dedicated bank account and credit card just for your rental property. Seriously. This one move takes your bookkeeping from a shoebox full of crumpled receipts to a simple, organized system. All your income goes in, and all your expenses go out, all in one place.
The Essential Record-Keeping Checklist
Think of your records as your shield. You’re building your defense case for every single deduction you claim, just in case you ever need it. Keeping everything organized and easy to find is non-negotiable.
Here’s what your core documentation file should contain:
- Receipts and Invoices: Save everything. Whether it’s a digital receipt for a new water heater or a paper invoice from your plumber, it’s proof of an expense.
- Bank and Credit Card Statements: These are your monthly summaries, providing a backup and a high-level view of your spending.
- Lease Agreements: These documents are crucial. They prove your property was actively a rental and spell out the income you expected to collect.
- Legal Documents: This file should hold your property’s closing papers, insurance policies, and any mortgage or loan paperwork.
- Mileage Logs: If you’re deducting car expenses, a detailed log is a must. Note the date, mileage, and the specific business reason for every single trip.
Navigating Key Tax Forms
With your records in order, it’s time to translate that information onto the right tax forms. It might look a little intimidating at first, but it’s a logical process. For most landlords, it comes down to two main forms: Schedule E and Form 4562.
Schedule E (Form 1040), Supplemental Income and Loss, is ground zero for your rental finances. This is where you’ll list all your rental income and then line by line, categorize your expenses—everything from property taxes and insurance to repairs and management fees.
For what is often your largest deduction, depreciation, you’ll need another form. Form 4562, Depreciation and Amortization, is where the magic happens for this powerful write-off. You’ll use this to formally calculate and claim the depreciation for the rental building itself and any major improvements you’ve made.
Why Partnering With a Tax Pro Is a Smart Move
Sure, you can go it alone, but the tax code is a beast, and it’s always changing. Working with a tax professional who knows real estate inside and out isn’t just another expense—it’s an investment in your bottom line.
They live and breathe this stuff. A good pro can help you navigate the tricky line between a repair and a capital improvement, ensure you’re taking full advantage of things like the QBI deduction, and help you plan for the future to minimize the bite of depreciation recapture. More than anything, they provide peace of mind and are your best defense against costly mistakes and missed deductions.
Frequently Asked Questions
Even with a comprehensive guide, real-world landlording always throws a few curveballs. Let’s tackle some of the most common questions that pop up when you’re navigating the ins and outs of rental property taxes.
Can I Still Deduct Expenses if My Rental Is Vacant?
Absolutely. This is a huge relief for landlords dealing with tenant turnover. You can, and should, continue to deduct the ordinary and necessary expenses of keeping your property in rental-ready shape even when it’s empty.
Think of it this way: the business of being a landlord doesn’t stop just because a tenant moves out. You’re still paying for things like:
- Utilities (gas, electric, water)
- Property insurance
- Property taxes
- Advertising to find your next great tenant
- Lawn care and routine maintenance
The crucial detail for the IRS is that the property must still be available for rent. You have to be actively trying to fill the vacancy. If you decide to take it off the market for a few months for your personal use, those expenses are no longer deductible for that period.
How Do I Handle Deductions for a Partial-Year Rental?
This comes up a lot, especially with vacation homes or when you first convert a primary residence into a rental. The rule is simple: you have to divide your expenses between personal use and rental use. You can only deduct the expenses that correspond to the time the property was genuinely a rental.
The most straightforward way to do this is by counting the days. For example, say your property was rented for 200 days and you used it personally for 30 days. You’d need to prorate your annual expenses (like insurance or property taxes) to reflect that rental period. The same goes for depreciation—it only applies to the portion of the year it was a rental asset.
Important Note: Getting this allocation right is non-negotiable. The IRS pays close attention to properties with mixed-use, so keeping detailed, bulletproof records of rental vs. personal days is your best defense against any issues.
What Are the Limits on Deducting Rental Losses?
It’s not uncommon for a rental property, especially in the early years, to show a loss on paper after all deductions are tallied. However, the IRS has specific “passive activity loss” rules that can limit how much of that loss you can actually use.
Generally, you can only deduct passive losses (like from a rental) against passive income (like from another rental). But there’s a major exception for small-scale landlords.
The Special Allowance for Rental Real Estate Activities might let you deduct up to $25,000 in rental losses directly against your non-passive income, like your regular job salary. To qualify, you need to “actively participate” in managing your rental (which most small landlords do) and have a modified adjusted gross income (MAGI) under $100,000. The allowance starts to phase out after that and disappears completely once your MAGI hits $150,000.
Navigating the complexities of rental property taxation can feel overwhelming. The dedicated team at Allied Tax Advisors has decades of experience helping real estate investors maximize their deductions and ensure compliance. Let us help you build a sound financial strategy.