
Selling a rental property means more than handing over the keys and cashing the check. The IRS treats that sale as a taxable event, and you’ll face two main charges: capital gains tax on the increase in value and depreciation recapture on the deductions you’ve claimed. Understanding how each is calculated can help you manage—and potentially reduce—your final tax bill.
These aren’t just industry buzzwords. They reflect real dollars heading to the government when you close the deal, and each follows its own set of rules. Nail down these calculations, and you’ll avoid unwelcome surprises come tax time.
Your Guide To Rental Property Sale Taxes
When you dispose of a rental property, the IRS expects its share of the proceeds. But your taxable profit isn’t just the sale price minus what you paid upfront.
You also have to factor in any improvements you’ve made and the depreciation deductions you’ve taken over the years. These adjustments shape your adjusted cost basis, the true starting point for determining your gain.
Mapping Out Your Tax Journey
Think of your tax liability as a two-part equation. One captures the property’s appreciation, and the other recovers the depreciation you’ve already enjoyed. Each part is taxed differently, so tackling them separately is key.
- Adjusted Cost Basis: Your original purchase price, plus improvements, minus depreciation.
- Capital Gains: The profit above your adjusted basis, taxed at long- or short-term rates depending on how long you held the property.
- Depreciation Recapture: The portion of gain attributed to past depreciation, taxed up to 25%.
- Tax Deferral Strategies: Techniques like a 1031 exchange or installment sale that postpone or spread out your tax liability.
By the end of this guide, you’ll know that your taxable gain equals the sale price minus your adjusted cost basis—an ever-shifting number that underpins every tax calculation that follows.
Key Tax Concepts At A Glance
Below is a snapshot of the core tax events triggered when selling a rental property, what each entails, and their typical federal tax rates.
| Tax Concept | What It Is | Typical Federal Tax Rate |
|---|---|---|
| Capital Gains | Tax on your net profit when sale price exceeds adjusted basis | 0%–20% |
| Depreciation Recapture | Tax on the portion of gain representing past depreciation deductions | 25% |
| Net Investment Income Tax | 3.8% surtax on investment income above certain income thresholds | 3.8% |
With these figures in hand, you can better estimate your potential tax bill and choose strategies that align with your financial goals. Clarity here paves the way for smarter decisions and smoother closings.
Calculating Your Property's Adjusted Cost Basis
Before you can figure out the tax hit from selling your rental property, you need to know your starting point. And no, it’s not just what you paid for the place. The IRS looks at a specific number called the adjusted cost basis—this is the real foundation for calculating your taxable gain.
Many investors make the common mistake of thinking their profit is simply the sale price minus the original purchase price. That's a shortcut to a nasty tax surprise. The real math is a bit more involved because it has to reflect everything you’ve put into—and gotten out of—the property over the years.
Adjusted Cost Basis = (Purchase Price + Capital Improvements) – Accumulated Depreciation
This single number represents your total investment in the property from a tax perspective. Getting it right is absolutely critical. Every other tax calculation, from capital gains to depreciation recapture, hinges on an accurate basis.
What Are Capital Improvements vs. Repairs?
A huge part of this calculation is knowing the difference between a capital improvement and a simple repair. You spend money on both, but the IRS treats them in completely different ways.
- Capital Improvements: These are the big-ticket items that genuinely add value to your property, extend its useful life, or adapt it for a new purpose. Think about a full kitchen remodel, adding a deck, or replacing the entire roof. These costs get added to your basis.
- Repairs: These are the everyday maintenance costs that just keep the property in good running order without adding significant long-term value. Fixing a leaky pipe, patching drywall, or repainting a single room all fall into this category. You deduct these as rental expenses in the year you pay for them; they don't affect your basis.
For example, spending $8,000 to replace the entire HVAC system is a capital improvement. But paying a technician $300 for an annual service call is a repair.
How Depreciation Affects Your Basis
Depreciation is one of the best tax perks of owning rental property, letting you write off a piece of the property's value each year. But there’s a catch when you sell. Every dollar of depreciation you've ever claimed (or even could have claimed) reduces your cost basis.
Think of it this way: your basis starts high when you buy the property and gets chipped away little by little with each year's depreciation deduction. A lower basis creates a bigger gap between it and your sale price, which ultimately means a larger taxable gain.
Let's walk through a quick example to see it in action.
Example Calculation:
- Original Purchase Price: You bought a rental home for $300,000.
- Add Capital Improvements: Over a decade, you invested $50,000 in a new kitchen and updated bathrooms.
- Subtract Accumulated Depreciation: During that time, you claimed a total of $80,000 in depreciation deductions on your tax returns.
Now, let's plug those numbers into the formula:
($300,000 + $50,000) – $80,000 = $270,000 Adjusted Cost Basis
That $270,000 figure—not your original $300,000 purchase price—is the number you'll subtract from your sale price to find your total gain. For a deeper dive into this, you can learn more about how to figure capital gains in our detailed guide. Mastering this first step is essential for predicting what you'll owe.
So, How Are Your Profits Taxed?
Once you've nailed down your adjusted cost basis, you can figure out your total profit. But here's where it gets interesting—the IRS doesn't treat that profit as one big chunk. Instead, it gets split into different buckets, each with its own tax rate.
The biggest piece of the pie is usually your capital gain. This is the pure profit you made, the actual increase in your property's market value over time.
Think of it this way: your capital gain is your total profit (Sale Price – Adjusted Cost Basis) minus all the depreciation you've claimed along the way. We'll dig into that depreciation part in a moment, but for now, just know that the tax rate on your gain boils down to one simple question: how long did you own the place?
That holding period is the dividing line between two very different tax scenarios.
Short-Term vs. Long-Term Capital Gains
Patience is more than a virtue in real estate; it's a tax-saving strategy. Holding onto your rental property for more than a year is your ticket to much friendlier tax rates.
-
Short-Term Capital Gains: If you sell a property one year or less after you bought it, the IRS considers it a short-term gain. This profit gets taxed at your ordinary income rate—the same rate you pay on your salary. With federal rates climbing from 10% all the way to 37%, letting a big profit from a quick flip get taxed this way can be a painful mistake. For a deeper dive into how your regular rental income is taxed, you can find some great insights on landlordstudio.com.
-
Long-Term Capital Gains: This is the goal. Own the property for more than one year, and your profit qualifies for the much lower long-term capital gains rates. In 2024, these rates are 0%, 15%, or 20%, depending on your income. We're talking about a difference that can easily save you tens of thousands of dollars.
The bottom line is simple: Hold your property for at least a year and a day. It's one of the most powerful and straightforward ways to keep more of your money when you sell.
Don't Forget the Net Investment Income Tax
Just when you think you have it all figured out, there's another layer. Higher-income investors might get hit with an extra 3.8% tax called the Net Investment Income Tax (NIIT). This surtax applies to various forms of investment income, and yes, that includes the capital gain from selling your rental.
You'll need to watch out for the NIIT if your modified adjusted gross income (MAGI) is over a certain amount:
| Filing Status | Income Threshold |
|---|---|
| Single or Head of Household | Over $200,000 |
| Married Filing Jointly | Over $250,000 |
| Married Filing Separately | Over $125,000 |
If you cross that line, the 3.8% tax applies to either your net investment income or the amount your income exceeds the threshold—whichever is less. For a high-earner, this can turn a 20% long-term capital gains rate into a 23.8% rate. It's a critical piece of the puzzle to factor into your planning.
Let’s walk through a quick example to see it all in action.
Example Sale Calculation:
Let's say you sell your rental for $500,000. You've owned it for 10 years, your adjusted cost basis is $270,000, and you've claimed $80,000 in depreciation over that time.
-
Calculate Total Gain: $500,000 (Sale Price) – $270,000 (Adjusted Basis) = $230,000
-
Isolate the Depreciation: Pull out the $80,000 you've depreciated. This gets taxed separately (more on that next!).
-
Find Your Capital Gain: $230,000 (Total Gain) – $80,000 (Depreciation) = $150,000
Because you owned the property for a decade, that $150,000 is a long-term capital gain. It gets taxed at those favorable rates (say, 15%), not the punishingly high rate you pay on your regular income.
The Hidden Tax of Depreciation Recapture
When you sell a rental property, everyone talks about capital gains. But there's another tax—a hidden one, for many—that often comes as a nasty surprise. It's called depreciation recapture, and it's the IRS’s way of clawing back the tax benefits you've been taking for years.
Think of it this way: every year you owned the property, you got to claim a depreciation deduction. This lowered your taxable income, essentially acting like a small, interest-free loan from the government. When you sell, the IRS wants that money back.
This infographic gives a great overview of the different taxes you might be on the hook for, including short-term and long-term gains, plus the Net Investment Income Tax.
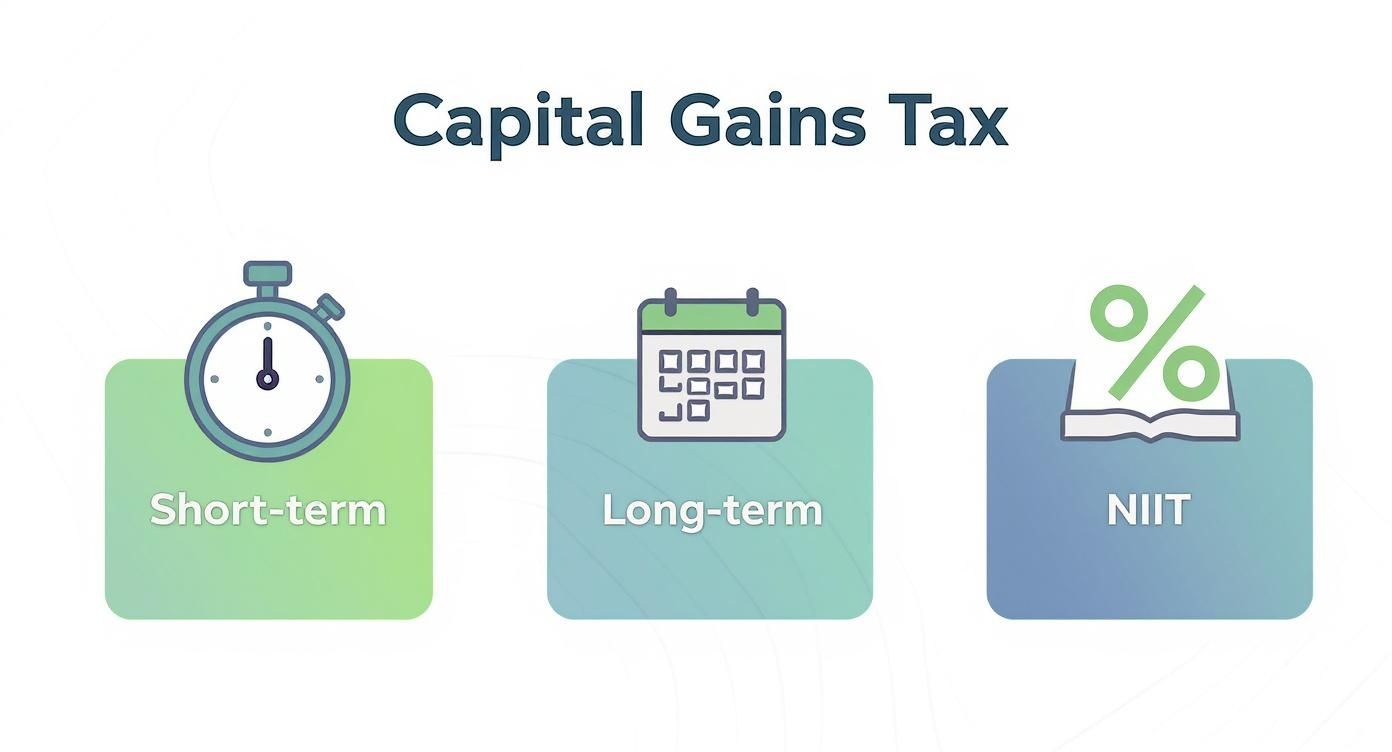
As you can see, how long you hold the property and your income level are the key factors that decide which tax rates apply when you cash out.
How Depreciation Recapture Is Calculated and Taxed
The math behind it is simple. Your depreciation recapture is just the sum of all the depreciation you've claimed—or should have claimed—while you owned the property. The real kicker is how this part of your profit is taxed. It doesn't get the friendly long-term capital gains rates of 0%, 15%, or 20%.
Instead, the IRS taxes recaptured depreciation at your ordinary income tax rate, with a ceiling of 25%. For most investors, that means paying a much steeper tax on that portion of the profit.
The logic is simple but strict: the IRS considers those depreciation deductions a benefit you’ve already received. When you sell, they make sure that benefit gets taxed so you don't get to double-dip on tax breaks.
Depreciation itself is a huge perk for real estate investors. In the U.S., you get to depreciate a residential rental property over 27.5 years. That means you can deduct about 3.64% of the building's value from your rental income each year. On a property with a $275,000 building value, that’s a $10,000 annual deduction.
Getting a handle on local regulations, like the San Diego rental property depreciation rules, is crucial for understanding how this all plays out when you sell.
Splitting Your Profit Into Two Tax Buckets
To really get how this works, you need to mentally divide your total gain into two different buckets, each with its own tax rate. Let's go back to our running example to see this in action.
Property Sale Example Revisited:
- Total Gain: $230,000
- Total Depreciation Claimed: $80,000
Here’s how the IRS carves up that $230,000 profit:
- Depreciation Recapture Bucket: The first $80,000 of your gain (the amount you depreciated) goes in this bucket. It gets taxed at your ordinary income rate, up to that 25% maximum.
- Capital Gains Bucket: The rest of the profit—in this case, $150,000 ($230,000 gain – $80,000 depreciation)—is a pure long-term capital gain. This is the portion that gets the lower 0%, 15%, or 20% tax rates.
This "two-bucket" system is precisely why meticulous record-keeping is non-negotiable. If you mess up your accumulated depreciation figure, you're setting yourself up for a costly tax bill. For a deeper dive, check out our full guide on https://alliedtax.com/rental-property-depreciation-recapture/. Keeping these two gains separate is the only way to ensure you're paying the right amount of tax on your hard-earned profit.
How To Defer Or Reduce Your Tax Bill
Knowing what taxes you owe is one thing; knowing how to legally sidestep or minimize them is where the real strategy comes in. Facing a huge tax bill after selling a rental property can feel like a punch to the gut. But with the right planning, you can keep your hard-earned capital working for you.
For real estate investors, the most powerful tool in the tax-deferral toolbox is the 1031 'like-kind' exchange. Don't think of it as a sale. Think of it as a swap. Instead of selling your property, taking the cash, and paying the tax, you roll the entire proceeds from the sale directly into a new investment property.
This powerful move lets you kick the can down the road on both capital gains tax and depreciation recapture. The tax bill doesn’t just vanish—it gets deferred and carried over to the new property, letting your investment portfolio grow without being chipped away by taxes every time you make a move.
The Mechanics Of A 1031 Exchange
A 1031 exchange isn't a handshake deal; it’s a formal process with strict IRS rules and timelines you have to follow to the letter. If you miss a deadline or a step, the whole thing can be disqualified, and you’ll be hit with the full tax bill immediately.
The process hinges on a "qualified intermediary" (QI), a third party who holds the sale proceeds for you. This is crucial: you can't touch the money yourself. The moment you close on the sale of your property, two clocks start ticking.
Key Timelines You Cannot Miss:
- The 45-Day Identification Period: From the day you sell, you have exactly 45 calendar days to officially identify potential replacement properties. This must be done in writing and delivered to your QI.
- The 180-Day Closing Window: You must close on one or more of those identified properties within 180 calendar days of the original sale.
These deadlines are absolute and include weekends and holidays. To pull off a successful exchange, you also have to follow specific rules about the value of the replacement property and any debt involved. Getting familiar with all the 1031 exchange real estate rules is non-negotiable before you even think about listing your property.
A 1031 exchange is a strategic tool for investors focused on long-term portfolio growth. It allows you to continuously upgrade your real estate holdings without having your capital eroded by taxes after each transaction.
Exploring Installment Sales
What if a 1031 exchange doesn't make sense for your situation? Another great strategy is the installment sale. This is perfect if you’re offering seller financing, where the buyer pays you for the property in chunks over several years.
Because you aren't getting all the cash upfront, the IRS doesn't expect you to pay all the tax upfront, either. You simply report a portion of your gain each year as you receive the payments.
This can be a fantastic way to manage your tax hit. By spreading the income over multiple years, you can often avoid getting bumped into a higher tax bracket and may even lower your exposure to the Net Investment Income Tax.
When it comes to deferring taxes on a property sale, both 1031 exchanges and installment sales are excellent options, but they serve different goals.
Tax Deferral Strategy Comparison
| Strategy | How It Works | Key Requirements | Best For |
|---|---|---|---|
| 1031 Exchange | You "swap" one investment property for another of "like-kind," rolling the proceeds over directly without touching the funds. | Strict 45-day identification and 180-day closing deadlines; must use a Qualified Intermediary. | Investors who want to stay in the real estate market and continuously grow their portfolio without tax interruptions. |
| Installment Sale | You receive payments from the buyer over multiple years and report a portion of the gain each year as payments are received. | The sale must involve at least one payment received after the tax year of the sale. | Sellers who want to exit a property, generate steady income, and spread their tax liability over time. |
Ultimately, the right choice depends on whether your goal is to reinvest immediately or to cash out gradually.
Beyond these foundational strategies, there are always other creative and effective strategies to slash your real estate capital gains tax. The key, as always, is planning ahead.
Reporting the Sale of Your Property to the IRS
Knowing what you owe in taxes is one thing; making sure the IRS sees it the same way is another. When you sell a rental, you can't just report the profit on a single line. The gain gets split up, with different pieces flowing to different forms that distinguish between business property and investment gains.
Think of your tax return as the final chapter in your property's story. Every number, from what you paid for it years ago to the closing costs on the sale, needs to be accounted for. Good record-keeping isn't just a chore—it's your best defense against overpaying or triggering an audit.
The Key IRS Forms You'll Need
When it's time to file, two main forms will do the heavy lifting. Each one is designed to handle a specific slice of the profit, and using them correctly is non-negotiable.
-
IRS Form 4797, Sales of Business Property: This is your starting point. Since a rental is considered a business asset, you'll report the sale here first. This form is specifically where you'll calculate the gain tied to depreciation recapture.
-
Schedule D, Capital Gains and Losses: After Form 4797 does its job, the rest of the profit—the pure capital gain—gets passed over to Schedule D. This is where it joins any other capital gains or losses you might have from stocks or other investments.
This two-step process is how the IRS makes sure each part of your gain is taxed at the right rate. The ordinary income from recapture is handled on Form 4797, and the capital gain is finalized on Schedule D.
You can think of Form 4797 as a sorting station. It first pulls out the business part of the gain (depreciation recapture) and then sends the remaining investment profit over to Schedule D for final processing.
A Step-by-Step Reporting Flow
Wading through tax forms can feel overwhelming, but there’s a clear logic to it. You’re essentially just walking the IRS through your math, showing them exactly how you arrived at your final numbers.
Here’s how the information generally flows on your tax return:
- Gather Your Documents: Before you touch a single form, get your paperwork in order. You’ll need the closing statements from both the purchase and the sale, detailed records of every capital improvement, and a summary of all the depreciation you've claimed over the years.
- Tackle Form 4797: You'll start here. Part III of the form is where you'll detail the sale price, your adjusted basis, and the depreciation you took. This is where the magic happens for calculating the amount subject to the 25% recapture tax.
- Carry it Over to Schedule D: Any profit left over after accounting for depreciation recapture is your capital gain (assuming you held the property for more than one year). This figure moves from Form 4797 directly onto Schedule D, where it will be taxed at the more favorable capital gains rates.
Following this structured process is the key to accurately reporting the tax implications of selling rental property. It ensures both your depreciation recapture and your capital gains are handled by the book, keeping your return clean and compliant.
Common Questions About Selling a Rental Property
Even when you feel like you have a handle on the rules, selling a rental property always seems to surface new, specific questions. Let's walk through some of the most common situations investors ask about to clear up any lingering confusion.
Can I Avoid Taxes by Converting My Rental to a Primary Residence?
Yes, this is a popular strategy, but it requires some real planning to pull off correctly. The goal here is to qualify for the Section 121 exclusion, which lets you shield up to $250,000 in gains ($500,000 for married couples) from taxes. To do this, you have to pass the IRS's "ownership and use tests"—basically, you must have lived in the home as your main residence for at least two of the five years right before you sell.
But here’s the critical catch: this doesn't get you out of paying all the taxes. You still have to pay the 25% depreciation recapture tax on any depreciation you took (or were allowed to take) after May 6, 1997.
Think of it as a hybrid benefit. You get to tap into the powerful primary home exclusion, but you can't escape the taxman coming back for the depreciation you claimed along the way. It’s a great tool, just not a magic wand.
What Happens If I Sell My Rental Property at a Loss?
Taking a loss on a property is never the goal, but it can provide a silver lining on your tax return. When you sell for less than your adjusted cost basis, you generate a capital loss. This loss is actually a valuable asset.
You can use it to wipe out capital gains from other investments, like profits from selling stocks or another property. If your losses are greater than your gains for the year, you can then use up to $3,000 of that excess loss to reduce your ordinary income (like your job salary). Any loss left over after that? It gets carried forward to future years to offset future gains.
Do I Have to Recapture Depreciation If I Never Claimed It?
This is a mistake that trips up so many investors, and it can be a painful one. The answer is a hard yes. The IRS doesn't care whether you actually took the depreciation deduction each year; they only care that you were supposed to.
The rule is that you must recapture depreciation that was "allowed or allowable." This means that when you sell, your property's basis is reduced by the amount of depreciation you were entitled to claim, even if you never did. So, you miss out on the annual tax deductions and still have to pay the recapture tax when you sell. It’s the worst of both worlds.
Navigating the complexities of real estate taxation requires expert guidance. At Allied Tax Advisors, we specialize in helping property investors plan for sales, minimize their tax burden, and stay compliant. Learn how our dedicated team can support your financial journey at https://alliedtax.com.