
Navigating the complexities of the U.S. tax code can feel overwhelming, but a thoughtful approach can significantly reduce your annual tax liability and accelerate your wealth-building journey. Effective tax planning is not about finding obscure loopholes; it's a proactive, year-round discipline of making strategic financial decisions to optimize your tax outcomes. This guide moves beyond the basics, offering a detailed roundup of eight powerful tax planning strategies for individuals that you can implement throughout the year, not just during tax season.
This article provides a comprehensive look at actionable methods to lower your taxable income and maximize your financial potential. We will explore how to make the most of your retirement accounts, leverage investment techniques like tax-loss harvesting, and capitalize on the unique benefits of Health Savings Accounts (HSAs). You will learn how to strategically manage your tax bracket, make your charitable giving more impactful, and optimize education savings.
These strategies are designed to help you keep more of your hard-earned money. Whether you're managing a diverse investment portfolio, preparing for your post-career years, or saving for a child's education, understanding these concepts is the first step toward greater financial control. While this guide covers a broad range of tactics applicable today, it is also wise to plan for your future obligations. To dive deeper into minimizing your tax burden throughout your post-career years, consider exploring expert strategies to reduce taxes in retirement. Let's explore the methods you can implement to build a more tax-efficient future.
1. Retirement Account Maximization
One of the most powerful tax planning strategies for individuals is maximizing contributions to tax-advantaged retirement accounts. This approach allows you to simultaneously build long-term wealth and reduce your current-year tax bill. By contributing to accounts like a 401(k), 403(b), or a traditional IRA, you lower your adjusted gross income (AGI), which can directly decrease the amount of tax you owe.
The core principle is simple: every dollar you contribute to a traditional retirement account is a dollar you don't have to pay taxes on today. This tax-deferred growth means your investments compound more rapidly over time. For a deeper dive into how strategic retirement planning aligns with overall financial goals, consider exploring additional comprehensive retirement planning guidance.
How It Works in Practice
Let’s consider an example. A 35-year-old software developer earning $80,000 annually decides to maximize their 401(k) contribution. They contribute the full $23,000 allowed for 2024. Their employer also provides a 50% match on the first 4% of their salary, adding another $1,600 to their account. By contributing the maximum, they effectively reduce their taxable income from $80,000 down to $57,000, saving thousands in federal and state taxes for that year while adding $24,600 to their retirement savings.
Actionable Tips for Maximization
To make the most of this strategy, focus on these key actions:
- Prioritize the Employer Match: Always contribute enough to your 401(k) or 403(b) to receive the full employer match. This is essentially free money and offers an immediate, guaranteed return on your investment.
- Automate Your Contributions: Set up automatic payroll deductions to ensure you consistently contribute throughout the year. This removes the temptation to skip contributions and makes saving effortless.
- "Pay Yourself First" with Raises: Whenever you get a salary increase, immediately allocate a portion of that raise to your retirement contributions. This allows you to increase your savings rate without feeling a pinch in your take-home pay.
For a clear overview, here are the key contribution limits for 2024.
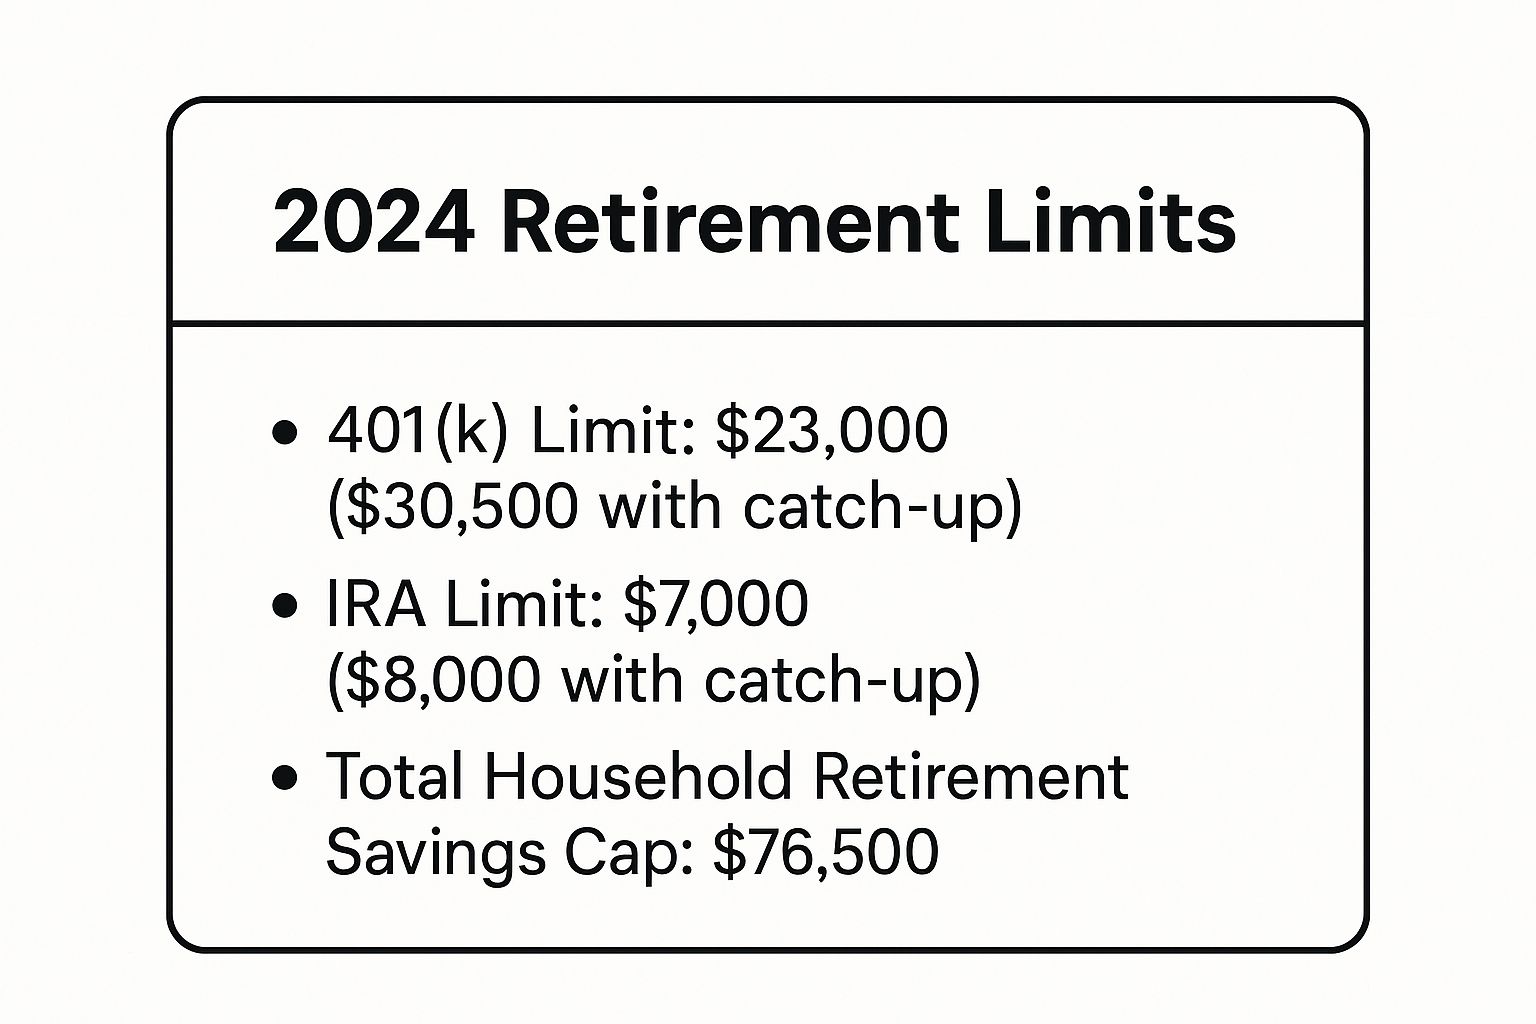
Understanding these limits is the first step toward creating a robust retirement savings plan that significantly reduces your tax liability. As you build your savings, you’ll also need a plan for your post-work years; you can learn more about minimizing taxes in retirement here.
2. Tax-Loss Harvesting
Tax-loss harvesting is a sophisticated tax planning strategy for individuals with investment portfolios. It involves intentionally selling investments at a loss to offset capital gains you’ve realized from selling other assets at a profit. This technique allows you to minimize your tax liability on investment gains and, in some cases, even reduce your ordinary taxable income, all while maintaining your long-term investment strategy.
The core principle is to turn market downturns into tax-saving opportunities. By strategically realizing losses, you can reduce the tax drag on your portfolio's growth, allowing your investments to compound more effectively over time. This approach is particularly powerful in volatile markets where price fluctuations create frequent opportunities to harvest losses.

How It Works in Practice
Imagine an investor holds two stocks. Stock A was purchased for $10,000 and is now worth $15,000, creating a $5,000 unrealized gain. Stock B was purchased for $10,000 but has dropped to $7,000, resulting in a $3,000 unrealized loss. The investor wants to sell Stock A to rebalance their portfolio but is concerned about the capital gains tax on the $5,000 profit.
By using tax-loss harvesting, the investor sells both Stock A and Stock B. The $3,000 loss from Stock B directly offsets the gain from Stock A, reducing the taxable gain to just $2,000 ($5,000 gain – $3,000 loss). This significantly lowers their tax bill for the year. To maintain market exposure, they could then reinvest the proceeds from Stock B into a similar, but not "substantially identical," asset to avoid the wash-sale rule.
Actionable Tips for Implementation
To effectively use this strategy, consider these key actions:
- Avoid the Wash-Sale Rule: Do not purchase the same or a "substantially identical" security within 30 days before or after selling it for a loss. Doing so will disallow the loss for tax purposes.
- Review Your Portfolio Regularly: Don't wait until the end of the year. Conduct quarterly reviews to identify potential losses you can harvest, especially during periods of market volatility.
- Prioritize Short-Term Losses: Use short-term capital losses to offset short-term capital gains first, as these gains are taxed at higher ordinary income rates.
- Keep Meticulous Records: Track your cost basis, sale proceeds, and any harvested losses that are carried forward to future tax years.
This strategy has also become popular in the volatile world of digital assets; you can explore more on how this applies to digital currencies with this guide to crypto tax-loss harvesting.
3. Health Savings Account (HSA) Triple Tax Advantage
The Health Savings Account (HSA) is one of the most powerful tax planning strategies for individuals, offering a unique triple tax advantage. Contributions are tax-deductible, the funds grow tax-free, and withdrawals for qualified medical expenses are also tax-free. This trifecta makes it an exceptional tool for both managing healthcare costs and building long-term wealth.
An HSA is available to individuals with a high-deductible health plan (HDHP). It allows you to set aside pre-tax money to cover deductibles, copayments, and other health-related costs your insurance doesn't cover. Because of its powerful tax benefits, many financial experts view it as a secondary retirement vehicle. To fully leverage the triple tax advantage of HSAs, ensure you're aware of the latest HSA contribution limits to maximize your annual savings.
How It Works in Practice
Imagine a young, healthy professional who maximizes their HSA contribution each year. Instead of using the funds for minor medical expenses, they pay out-of-pocket and invest their HSA balance in a diversified portfolio of mutual funds. Over decades, the account grows significantly due to tax-free compounding. In retirement, they can use this large, tax-free fund to cover healthcare costs or reimburse themselves for all the medical expenses they paid out-of-pocket over the years, as long as they kept the receipts.
Actionable Tips for Maximization
To get the most out of your HSA, consider these strategic actions:
- Contribute Through Payroll: If available, make your HSA contributions via payroll deduction. This not only reduces your income tax but also allows you to avoid FICA taxes (Social Security and Medicare) on the contributed amount, adding an extra layer of savings.
- Pay Out-of-Pocket and Invest: If your cash flow allows, pay for current medical expenses with post-tax dollars and let your HSA funds grow. You are essentially creating a tax-free investment account.
- Keep Meticulous Records: Save all receipts for qualified medical expenses you pay out-of-pocket. There is no time limit for reimbursing yourself from your HSA, so you can let the money grow for years and take a tax-free withdrawal when needed.
- Treat It as a Retirement Account: After age 65, you can withdraw funds from an HSA for any reason without penalty. Withdrawals for non-medical expenses are taxed as ordinary income, just like a traditional 401(k) or IRA, making it a flexible retirement savings tool.
4. Strategic Tax Bracket Management
A more advanced tax planning strategy for individuals involves actively managing which tax brackets your income falls into each year. The goal is to smooth out income and deductions over time to avoid being pushed into higher tax brackets in high-income years and to take full advantage of lower brackets in low-income years. This proactive approach allows you to minimize your lifetime tax liability, not just your bill for the current year.
The core principle is timing. By strategically accelerating or deferring income and deductions, you can control your taxable income. This ensures you aren't paying a higher marginal rate than necessary on any portion of your earnings. Understanding how your income relates to federal and state tax thresholds is crucial; you can learn more about managing California tax brackets here.
How It Works in Practice
Consider a retiree who has significant funds in a traditional IRA but has not yet started collecting Social Security benefits. In these "gap years" of low income, they can execute a Roth conversion, moving a portion of their traditional IRA funds into a Roth IRA. They will pay income tax on the converted amount now, but likely at a much lower rate (e.g., the 12% or 22% bracket) than they would in retirement when Social Security and other income could push them into a higher bracket.
Actionable Tips for Management
To implement this strategy effectively, focus on these key actions:
- Project Income Annually: Don't just look at the current year. Create multi-year income projections to identify opportunities for shifting income or deductions between years.
- Bunch Your Itemized Deductions: If your itemized deductions are close to the standard deduction amount, consider "bunching" them. For example, make two years' worth of charitable contributions in a single year to exceed the standard deduction, then take the standard deduction the following year.
- Time Capital Gains and Losses: If you have a high-income year, consider selling investments at a loss to offset other gains and up to $3,000 of ordinary income. Conversely, in a low-income year, you might sell appreciated assets to realize long-term capital gains at a 0% or 15% rate.
- Coordinate with Life Events: Plan major financial moves, like exercising stock options or selling a business, in conjunction with years where you might have lower income or larger offsetting deductions to manage the tax impact.
5. Charitable Giving Tax Strategies
Strategic charitable giving allows you to support causes you care about while also unlocking significant tax benefits. This approach goes beyond simply writing a check; it involves using tax-efficient methods like donating appreciated assets or bunching contributions to maximize your deductions. For high-earners, this is one of the most effective tax planning strategies for individuals to reduce taxable income and avoid capital gains taxes.
The fundamental goal is to make your generosity work harder for both your chosen charity and your financial well-being. By thoughtfully planning your donations, you can often give more than you thought possible while simultaneously lowering what you owe to the IRS. For those interested in structured giving, organizations like Fidelity Charitable offer powerful tools to streamline this process.
How It Works in Practice
Imagine a high-income professional who wants to donate $50,000 to their alma mater. They hold stock originally purchased for $10,000 that is now worth $50,000. If they sold the stock, they would owe capital gains tax on the $40,000 gain. Instead, they donate the stock directly to the university. This allows them to claim the full $50,000 as a charitable deduction and completely avoid paying any capital gains tax on the appreciation.
Another common scenario involves a retiree over age 70½ who must take a Required Minimum Distribution (RMD) from their IRA. By using a Qualified Charitable Distribution (QCD), they can direct up to $105,000 (for 2024) from their IRA to a qualified charity. This amount counts toward their RMD but is excluded from their AGI, potentially keeping them in a lower tax bracket and reducing their Medicare premiums.
Actionable Tips for Maximization
To make the most of your charitable giving, focus on these key actions:
- Donate Appreciated Assets: Instead of cash, consider donating stocks, mutual funds, or other assets you have held for more than one year. You can deduct the full fair market value and avoid paying capital gains tax.
- Bunch Your Donations: If your total itemized deductions are close to the standard deduction, consider "bunching" multiple years of charitable contributions into a single year. This allows you to exceed the standard deduction threshold and itemize, then take the standard deduction in the following years.
- Use a Donor-Advised Fund (DAF): A DAF allows you to make a large, tax-deductible contribution in a high-income year and then recommend grants to your favorite charities over time. This provides both immediate tax savings and flexibility.
- Keep Meticulous Records: Always obtain and keep receipts or written acknowledgments from the charity for any contribution of $250 or more. For non-cash donations, detailed records of the item's value are essential.
6. 529 Education Savings Plan Optimization
Optimizing a 529 education savings plan is a forward-thinking tax planning strategy that extends beyond just saving for college. These state-sponsored plans allow your investments to grow tax-deferred and be withdrawn completely tax-free when used for qualified education expenses. This dual tax advantage makes them a powerful tool for reducing your future financial burden and, in many cases, your current state tax liability.
The core benefit is significant: contributions grow without being taxed annually, and withdrawals for tuition, fees, books, and even some K-12 expenses are exempt from federal income tax. Over 30 states also offer a state income tax deduction or credit for contributions, providing an immediate financial incentive. This combination of benefits makes the 529 plan a cornerstone of family-oriented financial planning.
How It Works in Practice
Let’s consider an example of a family maximizing this strategy. A couple in a state with a tax deduction contributes $10,000 to a 529 plan for their child. They immediately save $500 on their state taxes (assuming a 5% tax rate). That $10,000 grows to $25,000 over 15 years. When their child attends college, the entire $25,000 can be withdrawn tax-free to pay for tuition. Had that same $15,000 in growth occurred in a regular brokerage account, it would have been subject to capital gains taxes.
Actionable Tips for Optimization
To make the most of your 529 plan, focus on these key actions:
- Leverage State Tax Benefits: Before opening an account, research your home state's 529 plan. Prioritize plans that offer a state tax deduction or credit for your contributions, as this provides an immediate return on your investment.
- Explore "Superfunding": For those with the capacity, you can contribute up to five years' worth of annual gift tax exclusions at once ($90,000 for an individual or $180,000 for a couple in 2024) without incurring gift tax. This front-loads the account, maximizing the potential for tax-free compound growth.
- Coordinate with Education Credits: Time your 529 withdrawals carefully. To claim valuable education tax credits like the American Opportunity Tax Credit (AOTC), you must have paid for some expenses with non-529 funds. Pay for the first $4,000 of expenses out-of-pocket to claim the full credit, then use 529 funds for the rest.
- Change Beneficiaries as Needed: 529 plans are flexible. If one child receives a scholarship and doesn't need all the funds, you can change the beneficiary to another eligible family member, such as a younger sibling or even yourself, without tax penalties.
7. Income Timing and Deferral Strategies
One of the more sophisticated tax planning strategies for individuals involves strategically managing when you receive income. Income timing and deferral allow you to shift earnings from a high-tax year to a lower-tax year, smoothing out your tax liability over time and potentially keeping you out of higher tax brackets. By controlling the calendar year in which your income is recognized, you can optimize your overall tax outcome.
The core principle is to accelerate or delay income to align with years when you anticipate being in a lower tax bracket. This could be due to a job change, retirement, or a year with unusually high deductions. This forward-looking approach ensures you don't pay more tax than necessary simply because of the timing of a payment.
How It Works in Practice
Let’s consider an example. An executive is due to receive a $50,000 year-end bonus. Her regular salary already places her near the top of the 24% federal tax bracket. Receiving the bonus in December would push a significant portion of that income into the 32% bracket. By negotiating with her employer to receive the bonus in January of the following year, she defers the income. This keeps her in the 24% bracket for the current year and allows her to manage the tax impact in the next year, where her income might be lower or her deductions higher.
Another common use is an installment sale for a real estate investor. Instead of recognizing a large capital gain from a property sale in one year, the sale is structured so that payments are received over several years. This spreads the capital gain, and the resulting tax liability, across multiple tax periods, often keeping the investor in a more favorable long-term capital gains tax bracket each year.
Actionable Tips for Implementation
To make the most of this strategy, focus on these key actions:
- Project Future Income: Before making any decisions, create income projections for the current and next one to two years. This helps you identify which year is likely to have a lower tax burden.
- Time Stock Option Exercises: If you have stock options, plan the timing of your exercises carefully. Exercising them in a year when your other income is lower can result in significant tax savings.
- Consider Deferred Compensation Plans: If available, participating in a non-qualified deferred compensation (NQDC) plan allows you to elect to receive a portion of your salary or bonus at a future date, typically in retirement when your income is lower.
- Factor in the Time Value of Money: Remember that deferring income also means deferring when you have access to the cash. Ensure the tax savings outweigh the opportunity cost of not having the money to invest or use today.
8. Asset Location Optimization
Beyond asset allocation, a more advanced tax planning strategy for individuals is asset location. This technique involves strategically placing different types of investments into the most tax-efficient accounts to minimize your overall tax burden. By housing tax-inefficient assets in tax-advantaged accounts and tax-efficient ones in taxable accounts, you can significantly boost your after-tax returns without changing your underlying investment mix.
The core principle is to shield your least tax-friendly investments from annual taxation. This allows them to grow unimpeded by tax drag, maximizing their compounding potential over the long term. This approach moves beyond simple contribution strategies to thoughtfully structure your entire investment portfolio for optimal tax efficiency.
How It Works in Practice
Imagine an investor with three types of accounts: a taxable brokerage account, a traditional 401(k), and a Roth IRA. They want to invest in corporate bonds, growth stocks, and a tax-managed international index fund. A smart asset location strategy would place the highly-taxed corporate bonds (which generate ordinary income) into the tax-deferred 401(k).
The high-potential growth stocks would go into the Roth IRA, where all future growth and withdrawals will be completely tax-free. Finally, the tax-managed international index fund, which is already designed to be tax-efficient, would be placed in the taxable brokerage account. This alignment ensures each asset is in the ideal environment to maximize its after-tax growth.
Actionable Tips for Optimization
To implement this powerful strategy, concentrate on these key actions:
- Prioritize Inefficient Assets for Shelter: Place assets that generate high levels of ordinary income or non-qualified dividends, like REITs, high-yield bonds, and actively managed funds, inside your tax-deferred accounts (401(k), Traditional IRA).
- Reserve Roth for High Growth: Use your Roth accounts for assets with the highest expected growth potential, such as individual growth stocks or aggressive equity funds. This allows you to secure decades of tax-free compounding and withdrawals.
- Use Taxable Accounts for Efficient Investments: Your taxable brokerage account is best suited for tax-efficient investments. This includes buy-and-hold individual stocks, tax-managed mutual funds, or ETFs that generate qualified dividends and long-term capital gains.
- Review and Rebalance Mindfully: As your financial situation or tax laws change, review your asset location. When rebalancing, try to make adjustments within your tax-advantaged accounts first to avoid triggering capital gains in your taxable accounts.
Tax Planning Strategies Comparison for Individuals
| Strategy | Implementation Complexity 🔄 | Resource Requirements ⚡ | Expected Outcomes 📊 | Ideal Use Cases 💡 | Key Advantages ⭐ |
|---|---|---|---|---|---|
| Retirement Account Maximization | Moderate – understanding limits & plans | Moderate – steady income, payroll systems | Long-term tax-advantaged wealth accumulation | Individuals with stable income, aiming for retirement | Employer match, tax deferral, forced savings |
| Tax-Loss Harvesting | High – requires ongoing monitoring & rules | Moderate – trading costs, software tools | Reduced tax bill via offsetting gains | Taxable accounts with active portfolio management | Offsets gains, unlimited carryforward |
| Health Savings Account (HSA) | Moderate – requires HDHP & record keeping | Low to moderate – plan enrollment needed | Triple tax benefits & medical expense savings | Those with HDHPs, seeking healthcare and retirement | Triple tax advantage, no RMDs |
| Strategic Tax Bracket Management | High – complex multi-year planning | High – professional advice often needed | Minimized lifetime tax burden | High earners, retirees managing multiple income sources | Significant tax reduction flexibility |
| Charitable Giving Tax Strategies | Moderate – planning deductions & assets | Low to moderate – requires record keeping | Reduced taxable income via deductions | Philanthropists and high-income donors | Capital gains avoidance, estate benefits |
| 529 Education Savings Plan | Low to moderate – plan setup and rules | Low – contributions with gift tax limits | Tax-free growth for education expenses | Families saving for education | Tax-free withdrawals, state tax benefits |
| Income Timing and Deferral | High – requires income forecasting & timing | Moderate – coordination with employers | Optimize tax brackets and cash flow | Professionals with variable income, bonuses | Defers income to lower tax years |
| Asset Location Optimization | High – strategic portfolio structuring | High – diverse account types needed | Improved after-tax portfolio returns | Investors with multiple account types | Maximizes tax efficiency across accounts |
Integrating Your Strategies for Maximum Financial Impact
We've explored a powerful arsenal of tax planning strategies for individuals, moving from the foundational pillars of retirement account maximization to the nuanced tactics of asset location and income timing. Each strategy, whether it's leveraging the triple-tax advantage of an HSA or strategically harvesting investment losses, holds the potential to significantly reduce your tax liability. But viewing these as isolated tools misses the bigger picture. True financial optimization isn't about picking one or two strategies; it's about weaving them together into a cohesive, year-round financial tapestry.
The real power emerges when these concepts are layered and synchronized. Imagine a scenario where you're not just contributing to your 401(k), but you're also timing that contribution to keep you in a lower tax bracket. Simultaneously, you're using tax-loss harvesting in your brokerage account to offset capital gains, and the proceeds are reallocated to more tax-efficient investments. This multi-layered approach transforms tax planning from a reactive, annual task into a proactive, wealth-building engine.
From Individual Tactics to a Unified Plan
Thinking of these strategies in isolation is a common mistake. A more effective mindset is to see them as interconnected gears in your personal financial machine.
- Retirement and Investments: Your retirement contributions directly impact your taxable income, which in turn influences your tax bracket. The decision of where to locate assets (e.g., high-growth stocks in a Roth IRA, bonds in a traditional IRA) is directly tied to maximizing the tax-deferred and tax-free growth potential of those accounts.
- Income and Giving: Timing a large bonus or capital gain can have massive tax implications. By pairing income deferral with a significant charitable donation via a donor-advised fund in a high-income year, you can create a powerful, tax-reducing synergy that maximizes both your savings and your philanthropic impact.
- Health and Education: The HSA and 529 plan are not just savings vehicles; they are strategic tax shelters. Funding them reduces your immediate taxable income, but the real benefit comes from decades of tax-free growth and tax-free withdrawals for qualified expenses, compounding your savings in a way few other tools can match.
The goal is to build a system where each financial decision is evaluated through a tax-aware lens. This proactive approach ensures you are not just saving for the future, but doing so in the most tax-efficient manner possible, preserving more of your hard-earned capital to work for you.
Turning Knowledge into Actionable Results
Mastering these sophisticated tax planning strategies for individuals is the difference between simply paying taxes and strategically managing your tax outcome. It’s about taking control of the variables you can influence rather than passively accepting a tax bill at the end of the year. This requires a shift from viewing tax season as a stressful deadline to seeing the entire year as an opportunity for optimization.
This journey from knowledge to implementation can seem daunting. The tax code is complex and ever-changing, and the optimal combination of strategies depends entirely on your unique financial situation, income level, and long-term goals. This is where professional guidance becomes not just a convenience, but a critical component of your financial success. A dedicated tax advisor can help you connect the dots, identify blind spots, and build a customized plan that aligns these powerful strategies with your personal financial narrative. By moving beyond isolated tactics to an integrated and professionally guided plan, you unlock the full potential of your financial life and build a more secure, prosperous future.
Ready to transform your tax strategy from a year-end chore into a year-round asset? The expert CPAs and enrolled agents at Allied Tax Advisors in Clairemont, San Diego, specialize in creating personalized tax planning strategies for individuals to help you achieve your financial goals. Visit us online at Allied Tax Advisors to schedule a consultation and start building your custom financial roadmap today.