
A smooth tax season doesn't start in March with a shoebox full of receipts. It's the result of good habits built month after month, all year long. Getting your financial house in order isn't just about staying on the right side of the IRS; it's about gaining a crystal-clear view of your business's health so you can make smarter decisions.
This isn't just a hunch. The global tax preparation market is a massive $34.9 billion industry, and it's on track to hit $46.12 billion by 2029. What’s driving that growth? The needs of small and medium-sized businesses just like yours. In the U.S. alone, there are 31.7 million small businesses—they are the true engine of the economy, creating the vast majority of new jobs.
So, how do you build that solid, year-round tax foundation? It boils down to a few core disciplines.
Your Pre-Filing Game Plan: Getting Organized
Before a single form is filled out, the real work begins with gathering your information. A little organization here goes a long way, preventing frantic searches for missing documents later.
Below is a quick rundown of the essential documents you'll need to pull together. Think of this as your financial command center for tax season.
Your Essential Pre-Filing Document Checklist
| Document Category | Specific Examples | Why It's Important |
|---|---|---|
| Identification & Basic Info | Social Security Numbers (for all owners), Employer Identification Number (EIN). | The IRS needs to know who you are and which business you're filing for. |
| Income Records | Bank deposits, 1099-NEC/1099-K forms, sales records, invoices. | Provides a complete picture of all the money your business brought in. |
| Expense Documentation | Receipts, credit card statements, bank statements, bills, check images. | Every documented expense is a potential tax deduction, lowering your taxable income. |
| Payroll Reports | Forms 941 (quarterly), Form 940 (annual FUTA), W-2s and W-3s. | Crucial for reconciling wages paid and taxes withheld throughout the year. |
| Asset Information | Receipts for large purchases (vehicles, computers, equipment), date of purchase. | Needed to calculate depreciation, a significant deduction for many businesses. |
| Previous Year's Tax Return | Your complete federal and state returns from last year. | Provides a baseline and contains important carryover information. |
Having these items ready before you start—or before you meet with a professional—is the single best thing you can do to ensure an accurate and stress-free filing experience.
Building Your Year-Round Tax Foundation
The secret to a painless tax season is what you do from January to December. These aren't just bookkeeping chores; they are the fundamental practices that create clarity and control over your business finances.
Draw a Hard Line Between Business and Personal Finances
This is rule number one, and it's non-negotiable. Using your personal credit card for office supplies or paying your mortgage from the business checking account is a recipe for a massive headache. This commingling of funds makes bookkeeping a nightmare and can even put your personal assets at risk if your LLC or corporation faces legal trouble.
The fix is simple: open a dedicated business bank account and get a business credit card. Run every single dollar of business income and expenses through these accounts. That’s it. You’ve just created a clean, accurate, and defensible record of your business activity.
Pick Your Accounting Method
You have to decide when to count your income and expenses. This is your accounting method, and there are two main choices.
Cash-Basis: You log income when the money actually hits your bank account and expenses when the money leaves it. It’s simple, intuitive, and great for freelancers or small service businesses because it mirrors your cash flow.
Accrual-Basis: You record income when you earn it (like when you send an invoice) and expenses when you incur them (when you receive a bill), no matter when the cash changes hands. This gives a more accurate picture of your financial health over time and is generally required if you sell products and manage inventory.
A common mistake I see is a growing business clinging to the cash method for too long. If you have a lot of unpaid customer invoices or outstanding bills to vendors, the accrual method will give you a much truer sense of your profitability, even if it feels a little more complex at first.
Set Up a Solid Record-Keeping System
Meticulous records are your best defense in an audit and your best tool for uncovering every possible deduction. You can't deduct what you can't prove.
Today, the best way to do this is with good accounting software for small business. These platforms automate a ton of the work, pulling in bank transactions, helping you categorize them, and generating the financial reports you need, like a Profit & Loss statement.
Combine that software with a simple system for saving digital copies of every receipt, invoice, and bank statement. For a more detailed look at creating a bulletproof system, check out our guide on how to track business expenses. Consistent, daily tracking is what turns tax time from a chaotic scramble into a calm, orderly process.
How Your Business Structure Shapes Your Tax Filing
There’s no single, universal way to file small business taxes. The right path depends entirely on your business structure. Whether you're a sole proprietor, an LLC, or an S Corp, each has its own set of forms and rules you need to follow. Getting this right is the foundation of a smooth tax season.
One of the first big decisions that affects your tax forms is your accounting method. It's a fundamental choice.
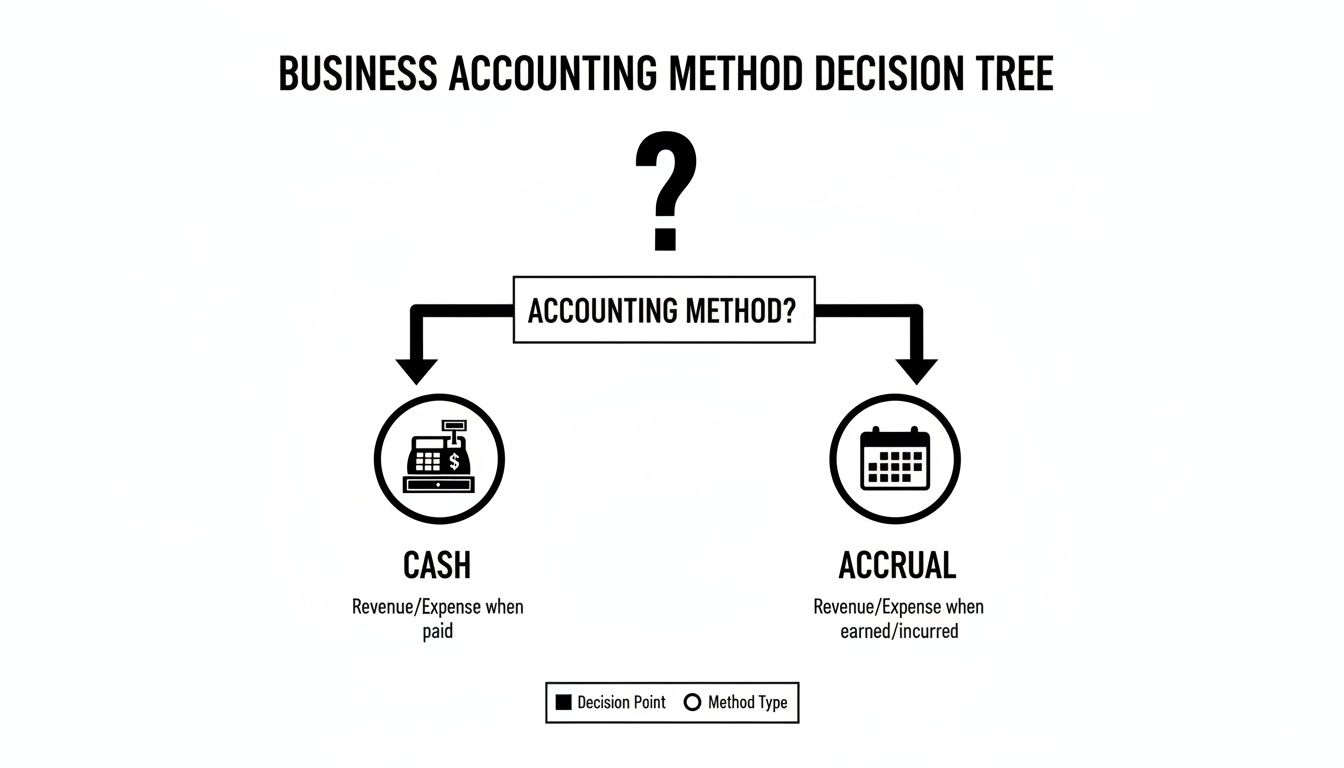
Choosing between cash and accrual accounting dictates how and when you report the very income and expenses that get reported on these forms.
The Sole Proprietor and Single-Member LLC Path
If you run your business as a sole proprietor or a single-member LLC (and haven't elected for a different tax status), the IRS treats you as a "disregarded entity." That might sound a little harsh, but it's actually great news for simplifying your taxes. Your business isn't taxed as a separate company; all its financial activity just flows through to your personal tax return.
You’ll report your business income and expenses on Schedule C, Profit or Loss from Business. This form then gets attached directly to your personal Form 1040. The final profit or loss from your Schedule C is added to your total personal income for the year. It's that straightforward.
- Real-World Example: Imagine a freelance graphic designer operating as a single-member LLC. She brings in $75,000 from client projects and spends $15,000 on essentials like software, marketing, and a home office. She'll fill out a Schedule C showing a net profit of $60,000, and that $60,000 is the number she'll carry over to her Form 1040.
This direct link means your business's bottom line has an immediate impact on your personal tax bill. A great year for the business means a higher personal income, and a tough year will lower it.
Navigating Partnerships and Multi-Member LLCs
Things look a bit different when your business has two or more owners. Partnerships and multi-member LLCs are also "pass-through entities," but they have an extra step: filing their own informational return with the IRS.
This is done with Form 1065, U.S. Return of Partnership Income. This form tallies up the partnership's total income, deductions, gains, and losses for the year. The key thing to remember is that the partnership itself doesn't pay income tax on its profits.
After the partnership files Form 1065, it then issues a Schedule K-1 to every partner. This document is critical—it breaks down each partner's unique share of the company's profits, losses, and credits, all based on the ownership percentages laid out in your partnership agreement.
The Schedule K-1 often trips up new partners. It's not just a summary; it’s the official record of the income you must report on your personal return, even if you never saw a dime of that money in a cash distribution.
Each partner takes the numbers from their K-1 and uses them to report their share of the business's activity on their own Form 1040.
The S Corporation Advantage
The S Corporation, or S Corp, is another popular pass-through structure that offers a unique tax twist. Just like a partnership, it files an informational return—in this case, Form 1120-S, U.S. Income Tax Return for an S Corporation—and profits are passed through to shareholders with a Schedule K-1.
The big difference is how owner compensation works. S Corp owners who are active in the business must pay themselves a "reasonable salary" as a W-2 employee. This salary is hit with standard payroll taxes (Social Security and Medicare). Any profits left over after that can be paid out to shareholders as distributions, which are not subject to self-employment taxes.
- Real-World Example: A small consulting firm, set up as an S Corp, has a net profit of $200,000. The owner pays herself a reasonable salary of $80,000. She only pays payroll taxes on that $80,000. The remaining $120,000 is passed through as a distribution, potentially saving her thousands in self-employment tax.
Choosing the right structure has huge financial consequences. If you're weighing your options, our deep dive into S Corp vs LLC structures can help clarify which is better aligned with your goals.
Finding Every Tax Deduction You Deserve
When it comes to small business tax prep, nothing impacts your bottom line more than maximizing your deductions. It’s a simple equation: every dollar you claim as a legitimate business expense is a dollar removed from your taxable income. That’s more money in your pocket, plain and simple.
But too many business owners stop at the obvious stuff—office supplies, software subscriptions—and leave serious cash on the table. We need to think bigger. Let’s go beyond the basics and dig into the deductions that really move the needle.
Unlocking the Home Office Deduction
If you run your business from your house, this deduction is one of the most powerful—and most misunderstood—write-offs you can take. The key rule is that you must use a specific area of your home exclusively and regularly for your business. That guest room that doubles as your office won’t cut it, but a desk in the corner of a room that’s only used for work? That qualifies.
You’ve got two ways to calculate it:
- The Simplified Method: This is the easy route. You get to deduct $5 per square foot of your office space, capped at 300 square feet (for a max deduction of $1,500). The record-keeping is minimal.
- The Actual Expense Method: This one takes more work but often delivers a much bigger tax break. You figure out the percentage of your home used for business—for example, a 150-square-foot office in a 1,500-square-foot home is 10%—and then deduct that same percentage of your actual home-related costs.
What counts as an actual expense? Think things like:
- Mortgage interest or rent payments
- Homeowners insurance
- Utilities (internet, electricity, gas)
- Repairs and upkeep
- Home depreciation
Imagine a marketing consultant with a 200-square-foot home office. Using the simplified method, she’d get a $1,000 deduction. But let's say her total annual home expenses are $20,000. If her office is 10% of her home's total square footage, the actual expense method would let her deduct $2,000—double the savings.
Capturing Vehicle and Travel Expenses
Business-related driving is a goldmine for deductions that many people overlook. Every trip to meet a client, pick up supplies, or attend a conference adds up. Just like the home office deduction, you have two ways to claim these expenses.
- Standard Mileage Rate: The IRS sets an official rate each year (for 2024, it's 67 cents per mile). You just track your business mileage and multiply. This rate is designed to cover gas, insurance, and general wear-and-tear without a ton of paperwork.
- Actual Expense Method: With this approach, you track and deduct the business-use percentage of all your car-related costs. This includes gas, oil changes, insurance, registration fees, repairs, and even depreciation. It requires meticulous logs, but it can be worth it for high-cost vehicles.
And what about travel that takes you away from home overnight? You can deduct the cost of your transportation (flights, trains), your hotel or lodging, and 50% of your meal expenses. So, if a software developer flies to a three-day industry conference, she can write off her airfare, her hotel bill, and half the cost of her food for the entire trip.
A common mistake I see is blurring the lines between business and personal travel. If you fly out for a five-day business trip but add two extra days for vacation, you can only deduct the expenses for those five business days. The IRS expects clear, honest records to back up your claims.
Beyond the Basics: Essential Business Deductions
While home office and auto expenses are the heavy hitters, don’t let other powerful write-offs slip through the cracks. These are crucial for any small business.
Insurance Premiums: The money you spend on general liability, professional liability (often called errors and omissions), and commercial property insurance is all fully deductible.
Professional Development: Did you take an online course to master a new software? Attend a workshop to sharpen your sales skills? The cost of any training or continuing education that helps you maintain or improve your abilities is a legitimate deduction.
Employee Benefits: If you have a team, the costs of providing benefits like health insurance, contributions to retirement plans (like a 401(k) match), and group-term life insurance are excellent deductions that also help you attract and retain talent.
The world of deductions is complicated, and just relying on off-the-shelf software can mean leaving money behind. While the U.S. tax preparation industry was valued at $14.3 billion in 2025, the rise of e-filing presents a real risk, especially to smaller practices. In fact, small firms of 1-3 people could lose over 13% of their business to DIY software. This points to a critical truth: software is a tool, but a human expert can spot nuanced, industry-specific deductions that an algorithm might miss.
For a deeper look into this topic, you might be interested in our complete guide to small business tax deductions.
Juggling Payroll, Sales, and Estimated Taxes
Great tax prep isn't a once-a-year scramble. It's about staying on top of the money flowing in and out of your business all year long. This is especially true for payroll, sales, and your own estimated taxes. Honestly, this is where I see most entrepreneurs get into trouble, getting hit with penalties and cash flow surprises that were completely avoidable.
Think of these as three separate financial streams you have to manage constantly. If you ignore them, you're not just creating a headache for next April; you're risking serious compliance issues with the IRS and state agencies at any time.
Navigating the World of Payroll Taxes
The minute you hire your first employee, your role changes. You become a tax collector for the government. With every single payroll run, you have a non-negotiable duty to withhold taxes from your employees' checks and pay your share as the employer.
These funds are earmarked for critical programs, and the government is very serious about you handling them with precision.
- Social Security & Medicare (FICA): This is a two-part contribution. You’ll withhold 7.65% from your employee's gross pay, and your business has to kick in a matching 7.65%. Together, that’s a total of 15.3% going to the government.
- Federal Unemployment Tax (FUTA): This one is just on you, the employer. You’ll pay FUTA on the first $7,000 of each employee's wages. The official rate is 6.0%, but there’s a big "but." If you pay your state unemployment taxes on time, you can get a credit of up to 5.4%, which drops the effective FUTA rate to a much more manageable 0.6%.
- State Unemployment Tax (SUTA): Every state runs its own unemployment program with different rates and rules. Don't overlook this one; it's a critical piece of your state-level compliance.
To keep everything straight and avoid penalties, using a good payroll compliance checklist is a smart move. It’s an easy way to stay organized and make sure you’re hitting all your deposit and filing deadlines.
Staying on Top of Sales Tax Obligations
If you sell taxable products or services, you’re also responsible for collecting sales tax and sending it to the right state and local governments. The magic word here is "nexus," which is just a fancy way of saying your business has a big enough footprint in a state to be required to collect its sales tax.
Nexus used to be simple—it was all about having a physical location. The internet changed everything. Now, you can trigger nexus in a state where you have no office or warehouse at all, simply by selling a certain amount to customers there. For a growing business, keeping up with dozens of different rates and rules is a huge operational challenge.
I see this catch e-commerce sellers all the time. They get so focused on their home state's rules that they don't realize that hitting $100,000 in sales to customers in California or New York just created a brand-new filing obligation. You have to watch your sales data on a state-by-state basis.
Paying Yourself with Estimated Taxes
As the business owner, you don't have an employer withholding taxes from your paycheck. But the IRS still wants its cut of your profits throughout the year. That's where quarterly estimated taxes come in. This system is how you pay both your income tax and your self-employment taxes (the full 15.3% for Social Security and Medicare).
If you don't pay enough as you go, you'll get slapped with an underpayment penalty. To avoid that nasty surprise, you generally need to pay at least 90% of what you'll owe for the current year or 100% of what you owed last year (110% if your adjusted gross income is over $150,000).
The need for expert help with these complexities is massive. Small businesses are the engine of the economy, and their tax challenges are driving the global tax prep industry toward a projected $38.3 billion in revenue by 2025. This isn't just a U.S. phenomenon; it highlights a universal need for professional guidance on tricky filings like payroll and sales tax.
When Should You Call a Tax Pro?
Let's be clear: DIY tax software can be a lifesaver for small businesses, especially when you're just starting out. It's affordable, it gets the job done for simple returns, and it puts you in control. But there comes a point in every growing business where the financial picture gets… messy.
That's when you hit a critical fork in the road. Sticking with the software-only approach can lead to costly mistakes and missed deductions, not to mention a whole lot of stress. Recognizing that you've outgrown the DIY route isn't a failure—it's a sign of success. It means you're playing in a bigger league, and the stakes are higher. Good tax work isn't just about filing; it's about smart, proactive financial management.
The Tipping Points: Time to Hire an Expert
Certain business milestones are practically screaming for professional help. If any of these situations sound familiar, the investment in a tax pro will almost certainly pay for itself.
- You’re doing business across state lines. The moment you have sales or a physical presence in multiple states, you're tangled in a web of different tax rules. Juggling various sales tax rates, income tax laws, and filing deadlines is a nightmare for the uninitiated. This is one of the most common reasons businesses call us.
- You've hired your first employees. Congratulations! You're an employer. You're also now responsible for payroll taxes. Messing up withholdings for Social Security, Medicare, and unemployment is a fast track to hefty penalties from both the IRS and state agencies.
- You're dealing with crypto or international sales. These aren't your average transactions. Tax laws around cryptocurrency are new and constantly changing, and the IRS is watching these transactions very closely. An expert can ensure you report every gain, loss, and transaction correctly.
- Your revenue just took a huge leap. A big jump in income is fantastic news, but it can easily bump you into a much higher tax bracket and put you on the IRS's radar. A tax professional can help you navigate this growth and find strategies to manage your new tax liability.
A quick but important warning: Be wary of "ghost preparers." These are unqualified or fraudulent preparers who will do your taxes but won't sign the return, leaving you 100% responsible for any errors. Working with a reputable firm like Allied Tax Advisors gives you accountability and expert representation you can count on.
A Tax Advisor Does More Than Just File Your Return
Thinking you only need a tax pro for a few weeks in the spring is one of the biggest misconceptions out there. The real magic happens all year long. Tax software is fundamentally reactive; you plug in numbers from last year and it spits out a result. A great tax advisor is proactive.
They become a strategic partner who helps you plan for what's ahead.
Year-Round Strategy, Not Just April Panic
A true tax professional looks at the big picture. They're focused on helping your business thrive financially throughout the entire year, not just at the filing deadline.
This partnership includes:
- Strategic Tax Planning: We're constantly looking for ways to legally lower your tax bill. This might mean advising you to buy that new piece of equipment before year-end to maximize depreciation or helping you select a retirement plan that offers the best tax advantages for your situation.
- Audit Representation: Nothing makes a business owner's heart sink like a notice from the IRS. If you're ever audited, having a CPA or Enrolled Agent in your corner is priceless. They speak the IRS's language and can handle the entire process for you.
- Compliance and Peace of Mind: At the end of the day, this is what it's all about. Partnering with a professional transforms tax season from a stressful, reactive chore into a forward-thinking part of your growth strategy. It frees you up to do what you do best: run your business.
Burning Questions About Business Taxes Answered
Let's be honest, navigating the tax code can feel like trying to solve a puzzle in another language. To cut through the noise, I've pulled together answers to the questions I get asked most often by business owners. This is the stuff you actually need to know to make smarter financial moves.
What Are the Biggest Tax Mistakes Small Businesses Make?
It's so easy to trip up, especially when you're just starting out. The number one mistake I see, time and time again, is mixing business and personal finances. When you use your business account for a family dinner or a personal card for office supplies, you create a bookkeeping nightmare. It makes tracking your real deductions nearly impossible and waves a giant red flag for the IRS.
Another huge one is just plain bad record-keeping. If you can't show a clear paper trail for your income and expenses, you can't back up your deductions if you get audited. It’s that simple. Solid bookkeeping is the foundation of everything.
Finally, a lot of new entrepreneurs either misclassify their employees as independent contractors (a costly mistake) or completely forget to pay their quarterly estimated taxes. Both of these can spiral into some seriously painful penalties.
The most damaging mistake isn't on a tax form—it's the failure to plan ahead. Tax prep is just reporting on the past. Real financial power comes from smart tax planning, making strategic choices all year long to legally lower what you'll owe come April.
How Long Do I Really Need to Keep My Business Tax Records?
The IRS has some specific timelines, and they’re probably longer than you think. The general rule of thumb is to hang on to your records for three years from the date you filed your return.
But, as with most things tax-related, there are exceptions.
- Underreported Income? Keep for 6 Years: If you accidentally underreport your gross income by more than 25%, the IRS gets six years to look into it.
- Worthless Stock or Bad Debt? That's 7 Years: If you're writing off a loss from worthless securities or a bad debt deduction, you need those records for a full seven years.
- Employment Taxes? Hold for 4 Years: For anything related to payroll taxes, keep those documents for at least four years after the tax was due or paid.
Honestly, with cloud storage being so cheap these days, the safest bet is to just keep digital copies of everything indefinitely. It's cheap insurance.
Can My LLC Deduct Home Office Expenses?
Yes, you absolutely can! The home office deduction has nothing to do with your business entity type—an LLC, S Corp, or sole proprietorship can all claim it. What really matters is meeting the two strict tests from the IRS.
First, the space must be your principal place of business. Second, you have to use that area exclusively and regularly for your work. That "exclusively" part is where most people get into trouble. A desk in the corner of the guest room that doubles as a playroom won't fly.
You’ve got two ways to calculate the deduction:
- The Simplified Method: This is the easy route. You get a flat $5 per square foot for up to 300 square feet, which maxes out the deduction at $1,500.
- The Actual Expense Method: This takes more work but often gives you a much bigger deduction. You figure out the percentage of your home used for business and then deduct that same percentage of actual home costs, like your mortgage interest, insurance, utilities, and repairs.
What's the Real Difference Between Tax Planning and Tax Preparation?
This is a huge one. Getting this distinction is what separates reactive business owners from proactive ones.
Tax preparation is the rearview mirror. It’s the process of gathering up last year's numbers, filling out all the right forms, and filing your tax return by the deadline. It's a necessary task focused on compliance—reporting what already happened.
Tax planning, on the other hand, is looking through the windshield. It's a year-round strategy where you actively look for ways to legally reduce your tax bill. This could mean timing a big equipment purchase to get the best depreciation, choosing a more tax-efficient business structure, or opening a specific retirement account.
Think of it this way: preparation is about dotting the i's and crossing the t's on last year's story. Planning is about writing a better story for next year.
Feeling like you're in over your head this tax season? You don't have to go it alone. The team at Allied Tax Advisors lives and breathes this stuff, helping businesses turn tax headaches into a strategic advantage. From year-round planning to flawless filing, we make sure you're not leaving money on the table. See how our expert advice can help your business thrive by checking out the Allied Tax Advisors website.