
When you file a joint tax return, you’re telling the IRS that you and your spouse are in it together. But what happens when one spouse makes a mistake—or worse, intentionally misleads the IRS—without the other's knowledge? That's where Innocent Spouse Relief comes in.
It’s an IRS provision that can get you off the hook for joint tax debt, including interest and penalties, that stem from errors your spouse or ex-spouse made on a return you signed together. Think of it as a crucial safety net, protecting you from a tax liability you had no part in creating.
Understanding Your Protection from Joint Tax Debt
Signing a joint return creates a powerful legal obligation called "joint and several liability." This is the tax world’s version of co-signing a loan; it means the IRS can come after either one of you for 100% of the tax debt, no matter who earned the income or made the mistake.
This becomes a nightmare if your partner hid income or claimed bogus deductions, leaving you with a massive, unexpected tax bill. It doesn't even matter if you're now divorced and your divorce decree says your ex is responsible for the debt. As far as the IRS is concerned, that’s a private agreement between you two—they can still collect the full amount from you.
The Role of Innocent Spouse Relief
This is the exact situation Innocent Spouse Relief was designed to fix. It’s a vital exception to that strict joint and several liability rule. If you qualify, the IRS can legally separate you from the debt caused by your spouse's actions.
These tax problems typically fall into two buckets:
- Understated Tax: This means the tax reported on your return was too low. Common causes are a spouse failing to report side-gig income or claiming deductions they weren't entitled to.
- Underpaid Tax: Here, the tax was calculated correctly on the return, but the full amount simply wasn't paid to the IRS.
The whole point of the program is to address the unfairness of holding someone responsible for financial mistakes they couldn't have known about. For instance, getting an IRS CP2000 notice proposing to increase your tax bill is a major red flag. Knowing what to do if you receive an IRS CP2000 notice is the first step toward figuring out if you need this kind of relief.
The core purpose of Innocent Spouse Relief is to provide a fair resolution for taxpayers who are unfairly burdened by joint tax liabilities. It acknowledges that not all financial partnerships are transparent and offers a path to separate your financial standing from a spouse's errors.
While this guide zeroes in on innocent spouse relief, a situation like this often highlights weak spots in your personal finances. It’s a good time to think about broader financial planning strategies to protect yourself in the future. Dealing with a complex tax issue really drives home the importance of having a solid financial plan.
The Three Paths to Spousal Relief
When you’re hit with a surprise tax bill from a joint return, it can feel like you’re backed into a corner. Fortunately, the IRS understands that punishing one spouse for the other's financial mistakes isn't always fair. They've created three distinct avenues for relief, each tailored to a different kind of situation.
Think of it this way: you wouldn't use a hammer to fix a leaky pipe. Likewise, the right type of spousal relief depends entirely on your circumstances—your marital status, what you knew (or didn't know) about the tax error, and whether it’s simply unfair to stick you with the bill. Figuring out which path is yours is the first step toward getting out from under that debt.
Innocent Spouse Relief: The Traditional Route
This is the one most people have heard of, and it’s exactly what it sounds like. It's designed for the spouse who was genuinely in the dark about the errors on a joint tax return. You signed the return in good faith, having no idea your spouse or ex-spouse was hiding income or inventing deductions.
To qualify for traditional Innocent Spouse Relief, the burden is on you to show the IRS that when you put your signature on that return, you had no knowledge and no reason to know about the "understated tax." This tax debt has to stem directly from your spouse's mistakes, such as:
- Failing to report income from a side business you never knew existed.
- Claiming bogus deductions for business expenses that were completely made up.
- Taking tax credits they weren't entitled to.
If you succeed, this relief wipes the slate clean. The tax, the penalties, and the interest are no longer your problem. But be warned: the "reason to know" standard can be a high bar. If your family was living a lifestyle far beyond your reported income—think luxury cars and exotic vacations on a modest salary—the IRS might argue that you should have asked some questions.
The infographic below breaks down the core eligibility factors the IRS looks at.
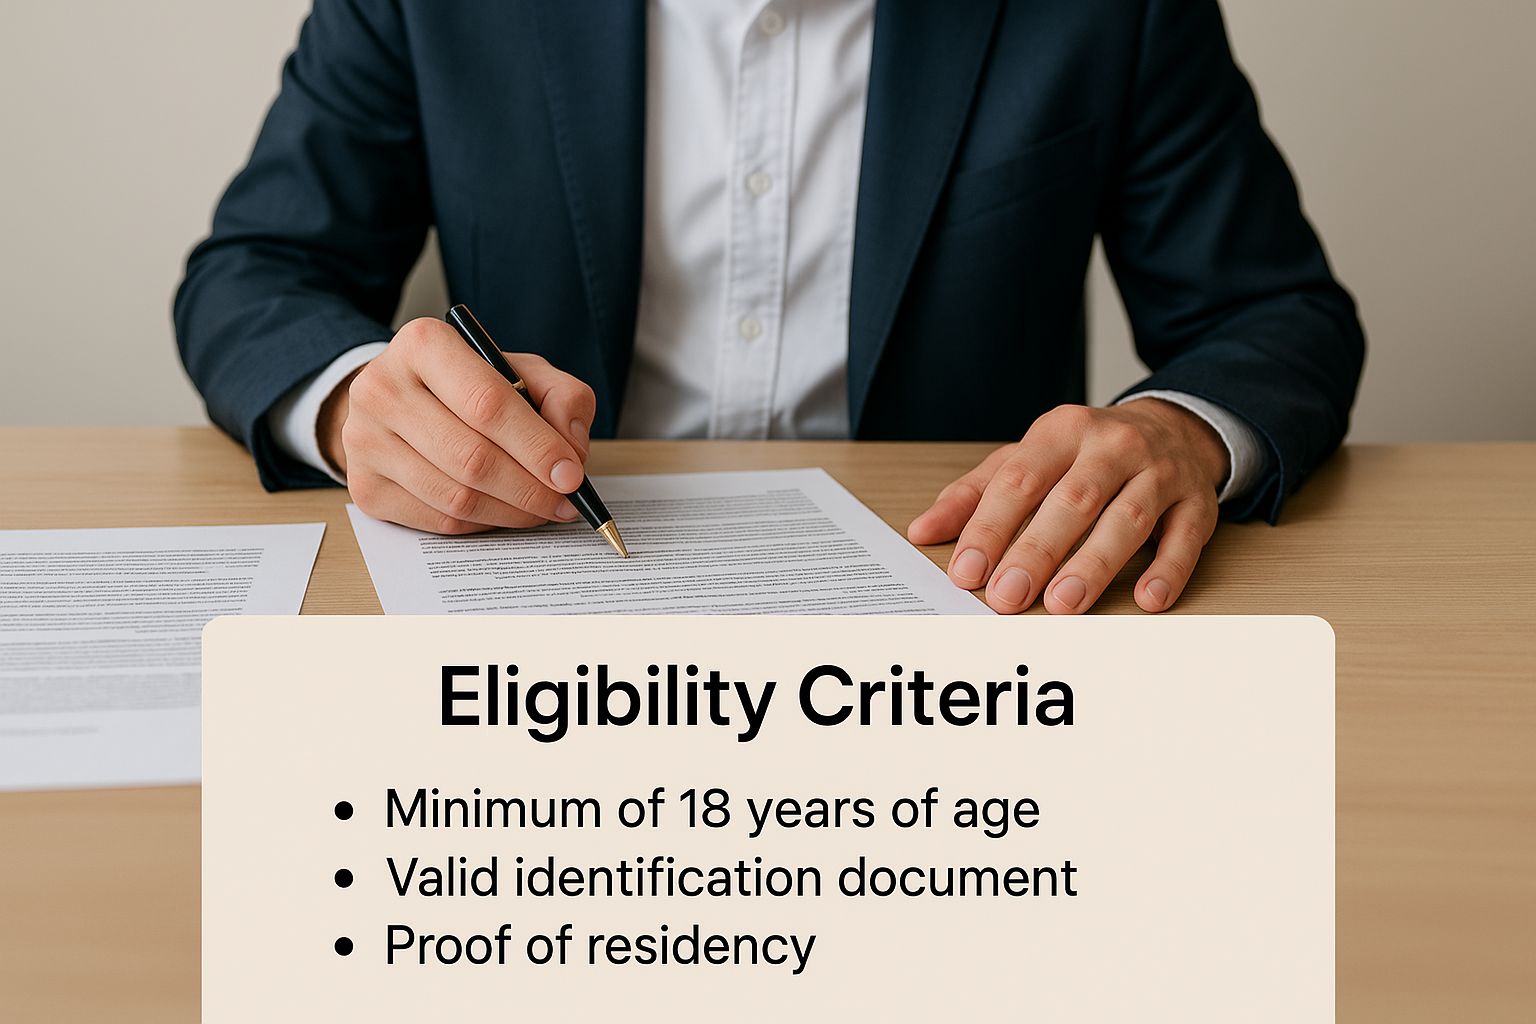
As you can see, what you knew and when you knew it plays a massive role in which type of relief makes the most sense for your situation.
Separation of Liability Relief: Dividing the Debt
Okay, but what if you did know about the issue on the tax return? Maybe you had your suspicions but didn't want to start a fight. If you’re now divorced, legally separated, or widowed, you may have another option: Separation of Liability Relief.
This path doesn't erase the tax debt, but it does something just as powerful—it draws a line down the middle. It allows you to legally divide the tax liability from the joint return. You become responsible only for the tax associated with your income and deductions, while your ex-spouse is left holding the bag for their share.
With Separation of Liability, you're essentially asking the IRS to re-calculate the tax as if you had filed separately from the beginning. It stops you from being on the hook for financial messes you didn't create, even if you were aware of them at the time.
To go down this road, you must meet one of these conditions when you file your request:
- You are divorced or legally separated.
- You are widowed.
- You haven't lived in the same house as your spouse for the entire 12-month period before filing for relief.
Equitable Relief: The Fairness Doctrine
Life is messy, and sometimes a situation doesn't fit neatly into the first two boxes. Maybe you had a reason to know about the error, so Innocent Spouse Relief is out. And maybe you’re still married and living together, so Separation of Liability won’t work either. This is where Equitable Relief comes in as a critical safety net.
Equitable Relief is all about one thing: fairness. The IRS will look at the whole picture—all the facts and circumstances—to decide if it would be fundamentally unjust to force you to pay the tax. It’s the most flexible option and often the last resort.
The IRS weighs several factors, including:
- Economic Hardship: Would paying this tax bill leave you unable to afford basic living expenses?
- Knowledge: Even if you knew about the error, were there other circumstances, like spousal abuse, that made it impossible to challenge?
- Abuse or Financial Control: Was your spouse controlling the finances to the point where you had no real say?
- Personal Benefit: Did you receive any significant benefit from the unpaid tax? A new car or a lavish vacation paid for with that money could work against you.
Crucially, this is the only type of relief that can apply to an underpaid tax—meaning the tax was reported correctly, but the bill was never paid. It’s for those who would otherwise be left with a completely unfair burden.
Comparing the Three Types of Spousal Relief
To make sense of these options, it helps to see them side-by-side. Each one is designed for a very different set of circumstances.
| Relief Type | Key Requirement | Best For… | Knowledge of Error |
|---|---|---|---|
| Innocent Spouse Relief | You did not know and had no reason to know about the tax error. | Spouses who were completely unaware of the understatement of tax. | No knowledge or reason to know is required. |
| Separation of Liability | You are divorced, legally separated, widowed, or have lived apart for 12+ months. | Spouses who are no longer with their partner and want to be responsible only for their portion of the tax. | You can have knowledge of the error. |
| Equitable Relief | It would be unfair to hold you liable for the tax debt under all circumstances. | Spouses who don't qualify for the other two types but face hardship or other compelling circumstances. | Some knowledge is acceptable if other factors (like abuse or hardship) weigh in your favor. |
As the table shows, your marital status and what you knew about the error are the biggest factors in determining your eligibility. Choosing the right path from the start is essential for a successful claim.
Checking Your Eligibility for Relief
Knowing that innocent spouse relief exists is one thing, but figuring out if you actually qualify is where the real work begins. The IRS doesn't hand this protection out easily, so it’s crucial to see if your situation lines up with their strict criteria.
Think of it like a checklist. To even have a shot at getting relief, you need to be able to tick every single box. Let’s break down exactly what the IRS is looking for.
The Five Core Tests for Eligibility
To get approved for traditional innocent spouse relief, you have to satisfy five key conditions. Here’s what each one means in the real world.
-
You Filed a Joint Return: This is the non-negotiable starting point. Innocent spouse relief was created specifically to address the legal concept of "joint and several liability," which only kicks in when you file a joint tax return. If you filed separately, this relief isn't for you, which is why the decision of married filing separately vs jointly is so important each year.
-
There's an Understated Tax on That Return: The problem must be that the tax on your return was reported too low. This is different from simply not paying the tax you owed (an underpayment). The understatement has to stem from what the IRS calls "erroneous items" from your spouse—things like unreported income from a side gig or completely fabricated business deductions.
-
You Didn't Know and Had No Reason to Know: This is the toughest hurdle for most people. You have to prove that when you put your signature on that tax return, you were completely unaware of the mistake. But it goes deeper: you also have to show you had no reason to suspect something was wrong. The IRS will look closely at your life to see if a reasonable person would have noticed any red flags.
-
It Would Be Unfair to Hold You Liable: Looking at the big picture, it must be fundamentally unfair to make you pay the tax debt. The IRS considers things like whether you personally benefited from the unpaid taxes (did you go on lavish vacations?) or if your spouse has since abandoned you, leaving you to deal with the financial fallout.
-
You Filed Your Request on Time: You must file Form 8857, the Request for Innocent Spouse Relief, no later than two years from the date the IRS first started trying to collect the tax from you. Miss this deadline, and your chances are gone.
Proving You Had No “Reason to Know”
That "reason to know" test is a major sticking point. The IRS expects you to act like any reasonably cautious person would. For instance, if your spouse suddenly bought a new boat while your joint tax return claimed you barely broke even, the IRS would argue you had a pretty good reason to ask some hard questions.
Let’s look at two quick examples to see how this plays out:
-
A Strong Case: Sarah's husband managed all their money. As a self-employed contractor, he kept all his business records and bank accounts separate, and he became controlling whenever she asked about finances. The IRS later found $50,000 in unreported income. Sarah can build a strong case that she was intentionally kept in the dark and had no way of knowing the truth.
-
A Weak Case: Mark and his wife shared a joint bank account. Mark saw large, random cash deposits appearing all year but never asked where the money came from. They used that extra cash to fund a trip to Europe. The IRS would almost certainly argue that Mark willfully ignored obvious warning signs and enjoyed the benefits of the untaxed income, making his claim for relief very weak.
Ultimately, getting approved comes down to painting a clear, honest, and believable picture for the IRS. If you can confidently check off all five requirements and tell a compelling story about why you were truly unaware, you’re on the right track to getting the relief you deserve.
A Step-by-Step Guide to the Application Process
Dealing with the IRS can feel like a maze, but applying for innocent spouse relief is a surprisingly straightforward process. The secret is to be methodical, honest, and incredibly thorough. Your entire case hinges on one crucial document: IRS Form 8857, Request for Innocent Spouse Relief.
This form is more than just paperwork; it's your formal petition to the IRS. It’s where you’ll lay out the facts of your case, present your evidence, and make the argument for why holding you responsible for this tax debt would be unfair. Think of it less like filling out a standard tax form and more like building a legal case for your financial future.
Step 1: Gather Your Essential Documents
Before you even glance at Form 8857, your first job is to gather all your documentation. A well-supported case is a persuasive case. Scrambling for these items later will only add stress and slow things down.
Start by getting these key documents together:
- The Joint Tax Return in Question: You'll need a full copy of the tax return for every single year you're asking for relief.
- IRS Notices: Collect every piece of mail you've received from the IRS about this specific tax debt. This means audit reports, collection letters—everything.
- Proof of Your Situation: This is where you back up your story. Divorce decrees, separation agreements, or any court orders that mention who is responsible for tax debts are vital.
- Evidence of Financial Control or Abuse: If this applies to you, collect anything that shows you were kept in the dark financially. This could be separate bank statements, emails showing your spouse controlled the finances, or other similar proof.
Having all this ready to go will make the next step infinitely easier and ensures your story is backed by solid evidence.
Step 2: Complete IRS Form 8857 with Care
With your documents in hand, it’s time to tackle Form 8857. This is not a form you want to rush through. Every question is there for a reason—to help the IRS figure out if you qualify for one of the three types of relief: Innocent Spouse, Separation of Liability, or Equitable.
You'll start with the basics about you, your spouse (or ex), and the tax years involved. But the most important section is the written narrative where you explain what happened. This is your chance to tell your side of the story.
Be detailed, specific, and completely honest. Explain what you knew and when you knew it. Clearly state why you believe you shouldn't be held liable for the debt. Vague statements will only hurt your claim, so create a clear timeline and reference your supporting documents.
Step 3: Submit Your Completed Application
Once the form is complete and you’ve attached copies of all your evidence, you’re ready to send it in. A word of caution: Do not send original documents. Always make copies for the IRS and keep the originals safe in your files.
You can mail or fax your Form 8857 package. The correct address and fax number are listed right in the form's instructions and depend on where you live. I always recommend sending it via a method that gives you proof of delivery, like certified mail. That little receipt is your proof that the IRS got it.
The need for this relief is significant. The IRS fields a massive number of these claims—around 45,000 requests are managed annually, a figure that has held steady for quite some time. You can read more about these IRS claim statistics on TaxpayerAdvocate.IRS.gov.
Step 4: Await the IRS Review Process
After you send your application, the waiting game begins. First, the IRS reviews your package to make sure it’s complete. Next, the law requires them to notify your spouse (or former spouse) about your request, giving them a chance to submit their own information.
The actual review can take a while, often six months or even longer. An IRS examiner will carefully go over your narrative, your evidence, and anything your spouse sends in, weighing it all against the strict eligibility rules. They might reach out with questions, so be sure to respond quickly to keep your case from stalling.
Real-World Examples: When Innocent Spouse Relief is Granted
The rules on paper are one thing, but seeing how they play out in real life is where it all clicks. The IRS doesn’t just look at checkboxes; they grant this powerful relief when the facts tell a clear story of a spouse who was truly left in the dark and unfairly stuck with a tax bill. These aren’t just abstract regulations—they’re applied to messy, complex human situations every single day.
Let's walk through a few common scenarios where someone would likely get the green light for relief. Each story shines a light on the critical factors the IRS weighs when making a decision.
The Hidden Business Income Scenario
Picture this: Alex runs a handyman business on the side, and it's all cash. He never reports a dime of it. His wife, Maria, is completely hands-off with his side gig and has never seen any of its financial records. They file a joint return based on Alex's main W-2 job and Maria's part-time salary, and she signs it, trusting it’s all correct.
A few years down the road, an audit uncovers $60,000 in unreported income from Alex's side work. The resulting tax bill is huge. Maria is a prime candidate for innocent spouse relief, and here’s why:
- She had no idea. Maria genuinely didn't know about the hidden income and had no reason to suspect it.
- She didn't benefit. Alex spent the extra cash himself, so Maria never enjoyed a lifestyle upgrade from the tax evasion.
- It would be unfair. Holding her responsible for a debt caused by Alex's deception would be a classic case of inequity.
The Post-Divorce Tax Blindside
Another all-too-common situation involves a person getting hit with an old tax bill long after a divorce. Imagine Sarah and Tom, who finalized their divorce last year. Suddenly, Sarah gets a notice from the IRS about a massive tax debt from a joint return they filed three years ago. The problem? Tom claimed a bunch of business deductions he wasn't entitled to.
Throughout their marriage, Tom managed all the money and had the taxes done. Sarah was a stay-at-home mom who trusted Tom when he said everything was filed correctly. Now that she's on her own and financially independent, her case for relief is very strong.
The IRS pays close attention to a change in marital status. A divorce or legal separation often strengthens the argument that it’s unfair to hold someone liable for a tax debt created by their ex-spouse.
When Financial Control Becomes Abusive
The most serious cases often involve financial abuse. When one spouse uses threats, intimidation, or manipulation to maintain total control over the finances, the other spouse might sign a tax return out of fear. They may even have a nagging feeling that something is off but are too scared to speak up.
In these tough circumstances, the IRS looks at the "reason to know" element through a different lens. If you can show a history of financial control or emotional abuse, it helps prove that even if there were red flags, you weren't in a position to safely question them. The IRS understands that in a coercive relationship, one partner simply doesn't have the freedom to act.
The legal landscape is always shifting, which impacts how these cases are decided. Tax courts continuously refine the rules, especially for divorced individuals still tangled in old joint tax debts. These rulings often highlight how a lack of financial control can be the key to a successful claim. To get a sense of these complexities in action, you can explore a recent innocent spouse case on IRSTaxTrouble.com.
What to Expect After You File Your Claim
Submitting your Form 8857 application is a huge step, but what happens next? Once the IRS gets your claim, a specific chain of events kicks off. Knowing what's coming can help you stay sane through the process.
The very first thing the IRS does is contact your spouse or ex-spouse. It's required by law. They have to be given the chance to participate, which means they can send in their own side of the story for the IRS examiner to consider.
The IRS Review and Decision Process
With the initial notification out of the way, the IRS starts its deep dive. An examiner will pour over your claim, the evidence you submitted, and anything your spouse or ex-spouse sent in.
This isn't a quick glance. The review is incredibly thorough and can easily take six months or longer, so it’s important to be patient.
When all is said and done, your case will have one of three outcomes:
- Full Relief Granted: This is the best-case scenario. The IRS agrees you're not responsible for any of the tax debt from your spouse's mistakes.
- Partial Relief Granted: The IRS might decide you qualify for relief on some of the tax issues, but not all of them.
- Denial of Relief: The IRS concludes that you don't meet the strict legal requirements for innocent spouse relief.
You won't be left in the dark. The IRS will mail you a preliminary determination letter explaining their decision. If they're planning to deny your claim, the letter will spell out exactly why, giving you a chance to respond before it's final.
What Happens If Your Claim Is Denied
Getting a denial letter feels like a punch to the gut, but it is absolutely not the end of the road. The system has built-in checks and balances, and you have the right to fight the decision.
Your first move is to file an appeal within the IRS. This gets your case in front of the IRS Independent Office of Appeals, a separate division that takes a fresh, unbiased look at everything.
If the Appeals office also says no, your next option is to petition the U.S. Tax Court. A judge will hear your case and issue an independent ruling. This can get complicated, which is why we put together a guide on how to appeal an IRS tax decision that walks you through every step.
Common Questions About Innocent Spouse Relief
When you're trying to untangle yourself from a tax mess created by a former spouse, a lot of practical questions come to mind. It's completely normal. Let's walk through some of the most common ones we hear from people in your exact situation.
How Long Do I Have to File My Claim?
This is one of the most important questions because the clock is ticking. For the two main types of relief—Innocent Spouse Relief and Separation of Liability Relief—you have a strict deadline. You must file Form 8857 within two years of the day the IRS first started trying to collect the tax debt from you.
The rules for Equitable Relief are a bit more forgiving. Generally, you have up to 10 years from the date the tax was originally assessed, which lines up with the IRS's overall time limit for collecting taxes. That said, don't wait. The sooner you file after discovering the problem, the stronger your case will be.
Will This Affect My New Spouse if I Have Remarried?
Absolutely not. It's a common worry, but you can put it to rest. An innocent spouse claim is entirely backward-looking and has no impact on your current spouse.
The entire process is focused on a specific joint tax return you filed with your former spouse in a past year. Your new life—including your new spouse's income and assets—is completely separate and won't be dragged into this.
Key Takeaway: Think of an innocent spouse claim as closing a financial chapter from a past relationship. It has no connection to your current marriage or financial situation.
What Evidence Is Most Helpful for My Claim?
Your story is important, but evidence is what wins a case with the IRS. Your job is to paint a clear, undeniable picture for the agent reviewing your file. The more proof you have, the better.
Here’s a checklist of the kind of evidence that really makes a difference:
- Financial Separation: Can you show you had separate bank accounts? Gather any statements or records that prove you didn't have access to or knowledge of your ex-spouse's money.
- Proof of Abuse or Control: If there was a history of spousal abuse or extreme financial control, this is critical. Court orders, police reports, or even a sworn statement from a therapist can be powerful evidence.
- Divorce Decree: Your final divorce decree is essential, especially if it specifically assigns the tax debt to your ex-spouse.
- Lack of Benefit: You need to show you didn't enjoy the fruits of the unpaid taxes. Provide evidence that your lifestyle remained the same and you weren't suddenly taking lavish vacations or buying luxury cars.
At Allied Tax Advisors, we know how stressful it is to be blindsided by a tax bill from a past you thought was behind you. Our team specializes in helping people navigate the IRS and find a resolution. If you need help building a strong case to protect your financial future, visit us at Allied Tax Advisors to schedule a consultation.