
Yes, you absolutely can deduct the costs of a leased car you use for your business. The IRS allows you to write off the portion of your lease payments and other vehicle expenses that are directly tied to running your company. For freelancers, contractors, and small business owners, this is a fantastic way to lower your overall taxable income.
Understanding Your Car Lease Tax Deduction
Think of your leased car like any other business tool, whether it's a laptop or a piece of machinery. Every time you drive to a client meeting, pick up supplies, or travel between job sites, that's a business activity. The IRS gets this and lets you deduct the costs associated with that use.
The critical part, however, is separating business use from personal use. Driving from your home to your main office, for example, is considered commuting and isn't deductible. The same goes for running personal errands. You can only deduct the expenses for the miles driven for your business.
To do this, you have two different methods to choose from. Each has its own set of rules for calculating the deduction and what records you need to keep, so it's important to pick the one that fits your situation best.
Two Paths to Your Deduction
Claiming your deduction starts with a big decision: choosing between two IRS-approved methods. The right one for you really depends on how much you drive, the cost of your lease and vehicle maintenance, and frankly, how much paperwork you're willing to handle. Knowing how to get the most out of your vehicle expenses is a core part of good financial planning, much like implementing effective fleet management strategies for larger operations.
Here are your two options:
-
The Standard Mileage Rate: This is the no-fuss, straightforward approach. You simply keep a log of your business miles and multiply that total by a standard rate the IRS sets each year. This rate is meant to cover all the variable costs of operating your car, like gas, oil changes, insurance, and general depreciation.
-
The Actual Expense Method: This one requires more detailed record-keeping but can often lead to a much larger deduction, especially with a more expensive lease. You'll track all your car-related costs—lease payments, gas, oil, insurance, registration fees, repairs, you name it—and then deduct the business-use percentage of that total.
To make this choice a little easier, let's break down how the two methods stack up against each other.
Standard Mileage vs. Actual Expense at a Glance
Here’s a quick comparison to help you see the core differences between the two primary methods for deducting your leased vehicle expenses.
| Feature | Standard Mileage Rate | Actual Expense Method |
|---|---|---|
| Simplicity | High (track miles only) | Lower (track all expenses) |
| Deductible Items | Business miles multiplied by IRS rate | Lease payments, gas, insurance, repairs |
| Best For | High-mileage drivers, simpler bookkeeping | High-cost vehicles, lower mileage |
| Record Keeping | Requires a detailed mileage log | Requires a mileage log and all receipts |
Ultimately, the best method depends on your unique circumstances. If you put a lot of miles on your car, the standard rate might be both easier and more lucrative. But if you have a pricier lease or significant repair costs, taking the time to track actual expenses could pay off big time.
Choosing Your Path: Standard Mileage vs. Actual Expenses
When it's time to deduct your leased car expenses, the IRS gives you two roads to take. Think of it this way: one is like getting a simple, flat-rate travel allowance, and the other is like submitting an itemized expense report for every single cost.
The first is the Standard Mileage Rate, and the second is the Actual Expense Method.
Neither one is universally "better." The right choice really boils down to your specific situation—the car you drive, how many miles you rack up for business, and frankly, how much paperwork you're willing to handle. Getting this decision right is key, as it sets the stage for your entire vehicle deduction for the year.
This little decision tree can help you visualize the choice you're facing right after you've confirmed you're using the car for business.
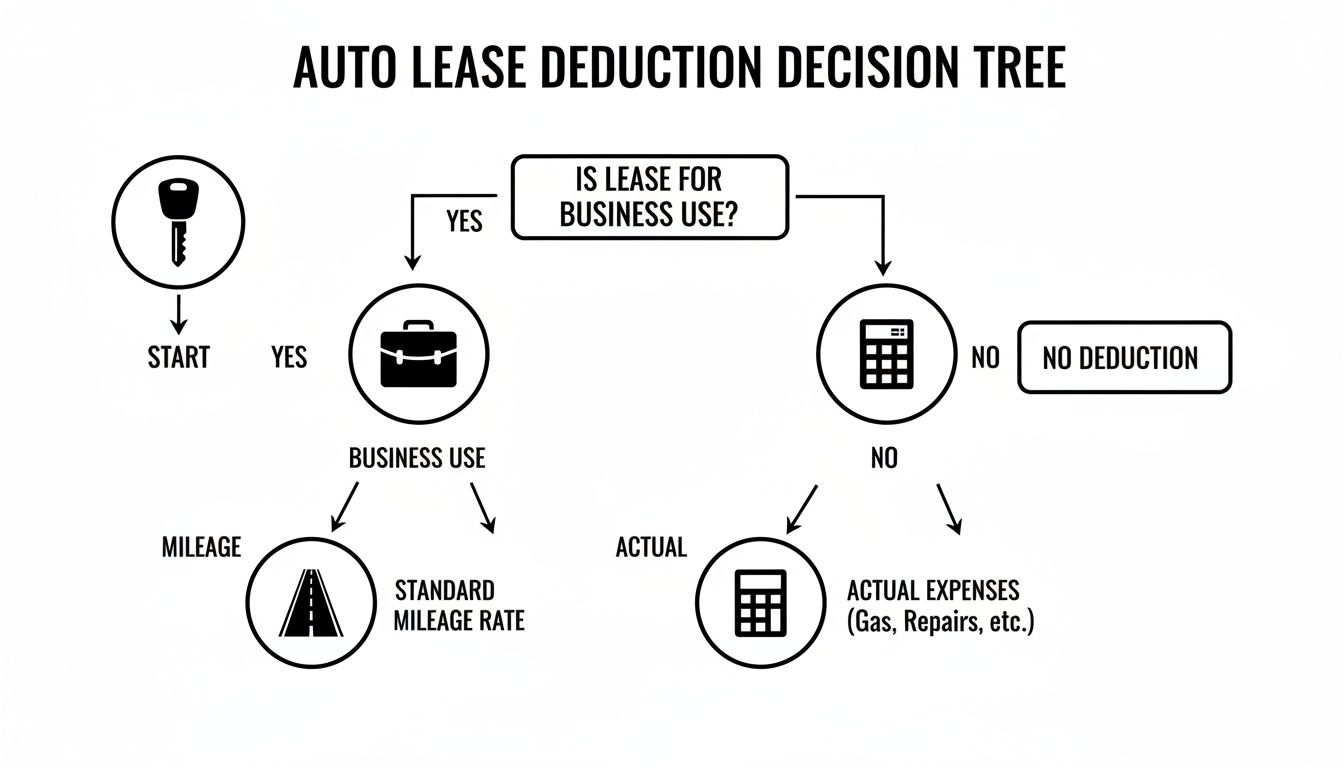
As you can see, it all comes down to that fork in the road. So, let's dig into what each path actually looks like.
The Standard Mileage Rate: The Simple Approach
For many self-employed folks and small business owners, the Standard Mileage Rate is the path of least resistance. It's wonderfully straightforward. Instead of hoarding a shoebox full of gas receipts and repair invoices, you only need to track one number: your business miles.
You simply multiply your total business miles for the year by the official rate the IRS sets. For 2024, that rate is 67 cents per mile. That single number is meant to cover all the variable costs of keeping your car on the road, like:
- Gas and oil
- Insurance
- Routine maintenance
- General wear and tear (the lease equivalent of depreciation)
One thing to remember is that even if you take this simple route, you can still deduct other specific travel costs on top of the mileage rate, like business-related parking fees and road tolls.
The bottom line: The standard mileage rate is often a great fit if you drive a lot of business miles in a reasonably fuel-efficient car. It saves a ton of administrative headaches, but be warned—you might be leaving money on the table if your actual car costs are on the higher side.
The Actual Expense Method: The Itemizer’s Choice
If you're the type of person who wants to squeeze every last drop out of your deductions, the Actual Expense Method is for you. This approach involves adding up every legitimate dollar you spent on your leased vehicle throughout the year.
From there, you calculate the percentage of time you used the car for business and apply that percentage to your total costs to find your deduction. For a deep dive into everything you can potentially write off, our guide on maximizing your savings by deducting vehicle expenses is a great resource.
Here are the most common costs you'll track with the Actual Expense Method:
- Your monthly lease payments (this is the big one!)
- Gasoline and oil
- Vehicle insurance
- Registration fees and taxes
- Repairs and maintenance
- New tires
- Business-related parking and tolls
Yes, this method demands diligent record-keeping—you'll need to keep those receipts. But for anyone with a hefty lease payment, a car that's expensive to maintain, or just plain bad gas mileage, the extra work often translates into a much bigger tax deduction.
Making the Right Decision for Your Business
So, which path should you take? It really comes down to running the numbers and being honest about your own habits.
The Standard Mileage Rate might be for you if:
- You put a lot of miles on your car for work (think 15,000+ miles a year).
- You drive an economical car with low running costs.
- You prioritize simplicity and want to spend less time on bookkeeping.
The Actual Expense Method is likely a better fit if:
- Your monthly lease payment is high (especially for a luxury or premium vehicle).
- Your car is a gas-guzzler or needs frequent, costly repairs.
- You don't drive a huge number of miles, but your per-mile cost is high.
Here’s a crucial rule you absolutely cannot forget for leased vehicles: If you choose the Standard Mileage Rate in the first year, you are stuck with it for the entire lease term. That includes any renewals of that same lease. However, if you start with the Actual Expense Method, you have the flexibility to switch to the mileage rate in a future year if it makes more sense. This makes that first-year decision incredibly important.
How to Calculate Your Business Use Percentage
When it comes to your car lease tax deduction, one number rules them all: your business use percentage. This figure is the foundation for your entire claim, as the IRS only lets you write off the portion of your car expenses directly tied to your business. Nailing this calculation isn't just a good idea—it's absolutely mandatory.
Think of your car's annual mileage as a pie. The IRS needs you to slice it into two pieces: business and personal. Your tax deduction is based entirely on the size of that business slice.
The Simple Formula for Success
The good news is that figuring out this percentage is pretty straightforward. It all comes down to tracking your miles consistently throughout the year.
-
Find Your Total Miles: First, you need the total miles you drove during the tax year. The easiest method is to jot down your odometer reading on January 1st and then again on December 31st. The difference between those two numbers is your total annual mileage.
-
Log Your Business Miles: This is where the real work comes in. You must keep a detailed log of every single mile driven for business purposes. This means tracking trips to see clients, drives between different job sites, and even runs to pick up supplies.
With those two figures in hand, the math is simple:
(Total Business Miles ÷ Total Annual Miles) x 100 = Your Business Use Percentage
Let's look at an example. Imagine a freelance photographer drives a total of 20,000 miles in a year. Her log shows that 16,000 of those miles were for photoshoots, client meetings, and scouting locations.
Her calculation would be: (16,000 ÷ 20,000) x 100 = 80%
This 80% is her magic number. It means she can deduct 80% of all her eligible car expenses—including her lease payments, gas, and insurance—if she's using the Actual Expense Method.
What Counts as a Business Mile?
One of the most common tripping points for small business owners is understanding what the IRS actually considers a "business mile." If you get this wrong, you could put your entire deduction at risk.
-
Deductible Business Miles Include:
- Driving from your office to meet with a client.
- Traveling between two different work locations (like from a job site back to your shop).
- Running errands specifically for your business, like going to the bank or post office.
- Driving to a professional conference or training seminar.
-
Non-Deductible Miles Include:
- Commuting: Your drive from home to your main office or place of work is never deductible. It's considered a personal expense.
- Personal Errands: Stopping at the grocery store or hitting the gym doesn't count, even if you happen to take a business call along the way.
Getting this distinction right is crucial. For a deeper dive, check out our guide on the differences between business miles vs. commuting miles in our detailed guide.
Why Your Mileage Log Is Your Best Defense
Let's be blunt: without an accurate, up-to-date mileage log, your business use calculation is just a guess. And the IRS doesn't deal in guesswork. If you're ever audited, that log is the first thing an agent will ask to see.
Your log doesn't have to be fancy. It can be a simple notebook you keep in your glovebox or one of the many GPS-tracking apps available for your phone. Whatever tool you use, it must record:
- The date of each trip.
- Your starting and ending odometer readings.
- The total mileage for the trip.
- The specific business reason for the trip (e.g., "Meet with Jane Smith at Acme Corp.").
This detailed record-keeping is what unlocks the powerful deductions available through leasing. The IRS allows you to deduct lease payments as a regular operating expense, but only if you can prove exactly how much you used the vehicle for business. A solid mileage log is your proof.
Navigating the Rules for Luxury Vehicles
Leasing a higher-end vehicle for your business feels great, but the IRS has a special rule you’ll need to get familiar with. It's called the lease inclusion amount. The name sounds a bit intimidating, but it’s really just a small adjustment to keep the tax rules fair.
Think of it this way: if you buy an expensive car for your business, the IRS caps how much depreciation you can write off each year. The lease inclusion rule was created to stop leasing from being a giant loophole around those depreciation limits. It’s a simple way to level the playing field between buying and leasing a luxury vehicle.
This small adjustment ensures the tax benefits stay comparable, no matter how you decide to get your wheels.
What Is the Lease Inclusion Amount?
The lease inclusion amount is a specific dollar figure you must add back to your income for each year of the lease. Another way to think about it is as a reduction from your total deductible lease payments for the year.
This rule only kicks in if the fair market value (FMV) of your vehicle at the start of the lease is above a certain amount set by the IRS. For vehicles first leased in 2024, that threshold is $62,000.
This isn't a penalty—it's just the IRS's way of equalizing the tax treatment. Getting a handle on how it works is the key to accurately calculating your deduction for any premium vehicle.
How to Find and Calculate Your Inclusion Amount
Figuring this out is actually pretty straightforward. You just need two things: your car’s Fair Market Value when the lease started and the official IRS tables from Publication 463.
Here’s the process:
- Find the Fair Market Value (FMV): Look at your lease agreement for the vehicle's FMV on day one. This is usually listed as the "capitalized cost," which is just the price you and the dealer agreed on for the car.
- Look Up the Inclusion Amount: Head over to the IRS's annual "Lease Inclusion Tables" in Publication 463 (Table 3 is the one for passenger cars). Find the value range that matches your car’s FMV, then find the dollar amount that corresponds to the current year of your lease.
- Adjust for Business Use: Take that dollar amount from the table and multiply it by your business use percentage for the year. That final number is your lease inclusion amount.
Let’s walk through a quick example to make it crystal clear.
Example Calculation
Imagine you leased a new SUV on January 1, 2024, with an FMV of $75,000. You tracked your mileage and found your business use for the year was 80%.
- First, you'd open the IRS table for cars leased in 2024.
- You find the row for an FMV "Over $74,000 but not over $76,000".
- For the first tax year, the table gives you an inclusion amount of $83.
- Now, just apply your business use: $83 x 80% = $66.40.
This $66.40 is what you have to "include" in your income. If your total deductible lease payments came to $9,600, your final, adjusted deduction would be $9,533.60 ($9,600 – $66.40).
To help you visualize how this works, here is a simple breakdown based on a vehicle's value.
Sample Lease Inclusion Calculation
| Vehicle FMV at Lease Inception | IRS Annual Threshold | Excess Value | Annual Lease Inclusion Amount (Example Rate) |
|---|---|---|---|
| $65,000 | $62,000 | $3,000 | $14 (for 1st year) |
| $75,000 | $62,000 | $13,000 | $83 (for 1st year) |
| $85,000 | $62,000 | $23,000 | $154 (for 1st year) |
| $95,000 | $62,000 | $33,000 | $223 (for 1st year) |
As you can see, the inclusion amount is quite small relative to the vehicle's cost, but it's a detail the IRS absolutely expects you to get right.
A Note on International Rules
It's always interesting to see how other countries handle similar issues. In Canada, for example, the government also sets limits on deductible leasing costs. For leases starting in 2025, the Canadian limit will be $1,100 per month, up from $1,050 in 2024 and $950 in 2023.
This shows a global trend of governments using tax rules to balance business incentives with fiscal responsibility. You can learn more about these automobile deduction limits in Canada to see how they've evolved.
Keeping Records the IRS Will Respect
When you're claiming a car lease on your taxes, think of your records as your ultimate backup. They're not just a suggestion from the IRS; they're the proof that separates a legitimate, money-saving deduction from a costly audit headache. If you can’t prove it, you can’t deduct it.
Building an audit-proof paper trail starts the second you sign that lease. The key is to track everything as it happens—not scrambling to piece things together in a panic months later. The IRS wants to see a consistent, real-time story of how you used that vehicle for business.
Your Essential Documentation Checklist
So, what does an IRS-friendly record-keeping system actually look like? It depends slightly on whether you choose the standard mileage or actual expense method, but a few documents are absolutely essential for everyone.
Think of this as your non-negotiable compliance file:
- The Original Lease Agreement: This is ground zero. It proves the lease exists, outlines the terms, and states the vehicle's Fair Market Value (FMV) at the start.
- A Detailed Mileage Log: This is the big one. Your log needs to show the date of each trip, the business purpose (e.g., "Client meeting with XYZ Corp"), starting and ending odometer readings, and the total miles driven.
- Receipts for All Actual Expenses: If you go this route, you need to save everything—receipts for gas, oil changes, insurance payments, new tires, repairs, and registration fees. For more on this, check out our guide on how to organize business receipts.
This might sound like a lot of work, but this level of detail is exactly what an IRS agent looks for.
Connecting Your Records to the Right Tax Forms
Once you’ve got all your ducks in a row, the final piece of the puzzle is putting the numbers on the right tax form. Where you report your vehicle expenses depends entirely on how your business is set up.
- For Sole Proprietors and Single-Member LLCs: You'll report everything on Schedule C (Form 1040), which is for profit or loss from your business.
- For Partnerships and Multi-Member LLCs: These expenses are entered on Form 1065, the U.S. Return of Partnership Income.
- For S Corporations: The deduction is claimed on Form 1120-S, the U.S. Income Tax Return for an S Corporation.
The strict American approach to proving business use is quite different from what you see in other countries. For instance, company car policies and tax rules in Europe are often much more lenient. In some European nations, company car plan participation can be as high as 97%, largely due to favorable tax laws, compared to just 45% in the US. These global differences in company car eligibility really highlight why meticulous record-keeping is so critical for U.S. business owners.
Common Mistakes That Can Cost You Money
Understanding the rules for your car lease tax deduction is only half the battle. Knowing what not to do is just as important, because a few simple errors can easily trigger an IRS audit or leave hundreds, if not thousands, of dollars on the table.
Getting this right means you keep more of your hard-earned money without attracting unwanted attention. Let's walk through the most common pitfalls business owners run into and, more importantly, how you can sidestep them completely.
Claiming 100 Percent Business Use
One of the biggest red flags you can wave at the IRS is claiming you use your vehicle 100% for business. Sure, it’s possible for something like a delivery van that never leaves the company lot overnight, but for the car you and I drive every day? It’s almost unheard of.
Think about it: even a quick stop at the grocery store on the way home from a client meeting means your business use has dipped below 100%. The IRS knows this, so an all-or-nothing claim without ironclad proof is basically an invitation for an audit. Be honest and realistic with your business-use percentage—it's just not worth the risk.
The rule is simple: if you can't prove it, you can't deduct it. The IRS operates on documentation, not just your word. An unsupported 100% claim is one of the easiest ways to have your entire vehicle deduction disallowed.
Sloppy or Nonexistent Mileage Logs
Saying you drove "about 10,000 miles for business" just isn't going to fly. Your mileage log is your single most important piece of evidence, and the biggest mistake people make is failing to keep a "contemporaneous" one—a fancy word for a log you update as you go.
A log that will stand up to scrutiny needs to include:
- The date of each business trip.
- The total miles you drove for that trip.
- The specific business purpose of your travel (e.g., "Client meeting with XYZ Corp").
Trying to recreate a whole year's worth of driving from memory on December 31st is a nightmare, and it's technically non-compliant. Grab a dedicated notebook for your glove box or use a mileage-tracking app to build an accurate, audit-proof record from day one.
Confusing Commuting with Business Miles
This is a classic rookie mistake. The IRS is crystal clear on this point: driving from your home to your main office or place of work is commuting. It’s considered a personal expense, and it is never, ever deductible.
Deductible business travel starts after you get to work—when you leave the office to meet a client, visit a job site, or run a business errand. The one exception is if you have a qualifying home office that serves as your principal place of business. Otherwise, that daily drive is off-limits. Mixing these up will seriously inflate your business mileage and can get you into hot water fast.
Answering Your Top Questions
Once you get the hang of the basics, the "what-if" questions start popping up. Let's tackle some of the most common scenarios we see, so you can handle the specific details of your lease with confidence.
Can I Deduct the Down Payment on My Car Lease?
This is a big one. It's tempting to think you can write off a large down payment all at once, but the IRS sees it differently. Since that upfront payment benefits you for the entire lease term, you have to spread the deduction out.
Think of it this way: if you put $3,600 down on a 36-month lease, you'll amortize that cost. You'd simply divide the down payment by the number of months ($3,600 ÷ 36 months), which gives you an extra $100 to add to your deductible expenses each month. Just like your regular payment, this amount is then multiplied by your business use percentage.
What Happens If I Buy the Car After the Lease?
When you buy your car at the end of the lease, you're officially switching from a renter to an owner. This means your tax strategy has to change, too. You'll stop deducting your monthly lease payments immediately.
Instead, you'll start depreciating the vehicle. Your cost basis for depreciation is the price you paid to buy the car. From there, you can use depreciation methods like Section 179 or MACRS to write off the car's value over its useful life. Of course, you can still deduct your other actual expenses—gas, insurance, repairs—based on your business use percentage, just as you did during the lease.
Are Electric Vehicle Leases Treated Differently?
For the most part, no. The rules for leasing an electric vehicle (EV) are the same as for a gas-powered one. You still have to choose between the standard mileage rate and the actual expense method, and your deduction is based on your business use.
The real difference comes down to the federal clean vehicle tax credits. As the lessee, you can't claim these credits yourself—the leasing company, as the legal owner, gets them. The good news? Many leasing companies will pass that savings on to you by factoring the credit into their pricing, which can lead to a lower monthly payment.
It’s an indirect benefit, but it can make leasing an EV a very smart financial move. Always make sure to ask the leasing company how they handle the EV credit before you sign.
Navigating the ins and outs of a car lease and tax deduction takes a bit of planning and know-how. At Allied Tax Advisors, our team is here to help you get the most out of every deduction while staying fully compliant. Schedule a consultation today to build a tax strategy that helps drive your business forward.