
If you're dealing with a foreclosure, tax season can feel like a second shock. The house is gone, the lender may have sent unfamiliar forms, and you're left wondering how the IRS could possibly view this as something that belongs on a tax return.
The part that trips up many homeowners is simple but unintuitive. A foreclosure is not one tax event. It's usually two separate tax events happening at the same time. If you blend them together, it's easy to file incorrectly, miss an exclusion, or assume a loss is deductible when it isn't.
Table of Contents
- The Two Sides of Foreclosure Taxes
- Calculating Gain or Loss on Your Property Sale
- Understanding Canceled Debt Income and Form 1099-C
- How to Exclude Canceled Debt from Your Taxable Income
- Handling Special Scenarios and Common Pitfalls
- A Step-by-Step Guide to Reporting Foreclosure on Your Taxes
The Two Sides of Foreclosure Taxes
You lose the house, then a tax form shows up in the mail. For many homeowners, that is the moment the situation stops feeling purely financial and starts feeling confusing. A foreclosure can create two separate tax issues at the same time, and treating them as one problem is where costly mistakes begin.
The cleanest way to understand it is to picture two sides of the same tax coin. One side is the property. The other side is the debt. Both relate to the same foreclosure, but the IRS measures them differently.
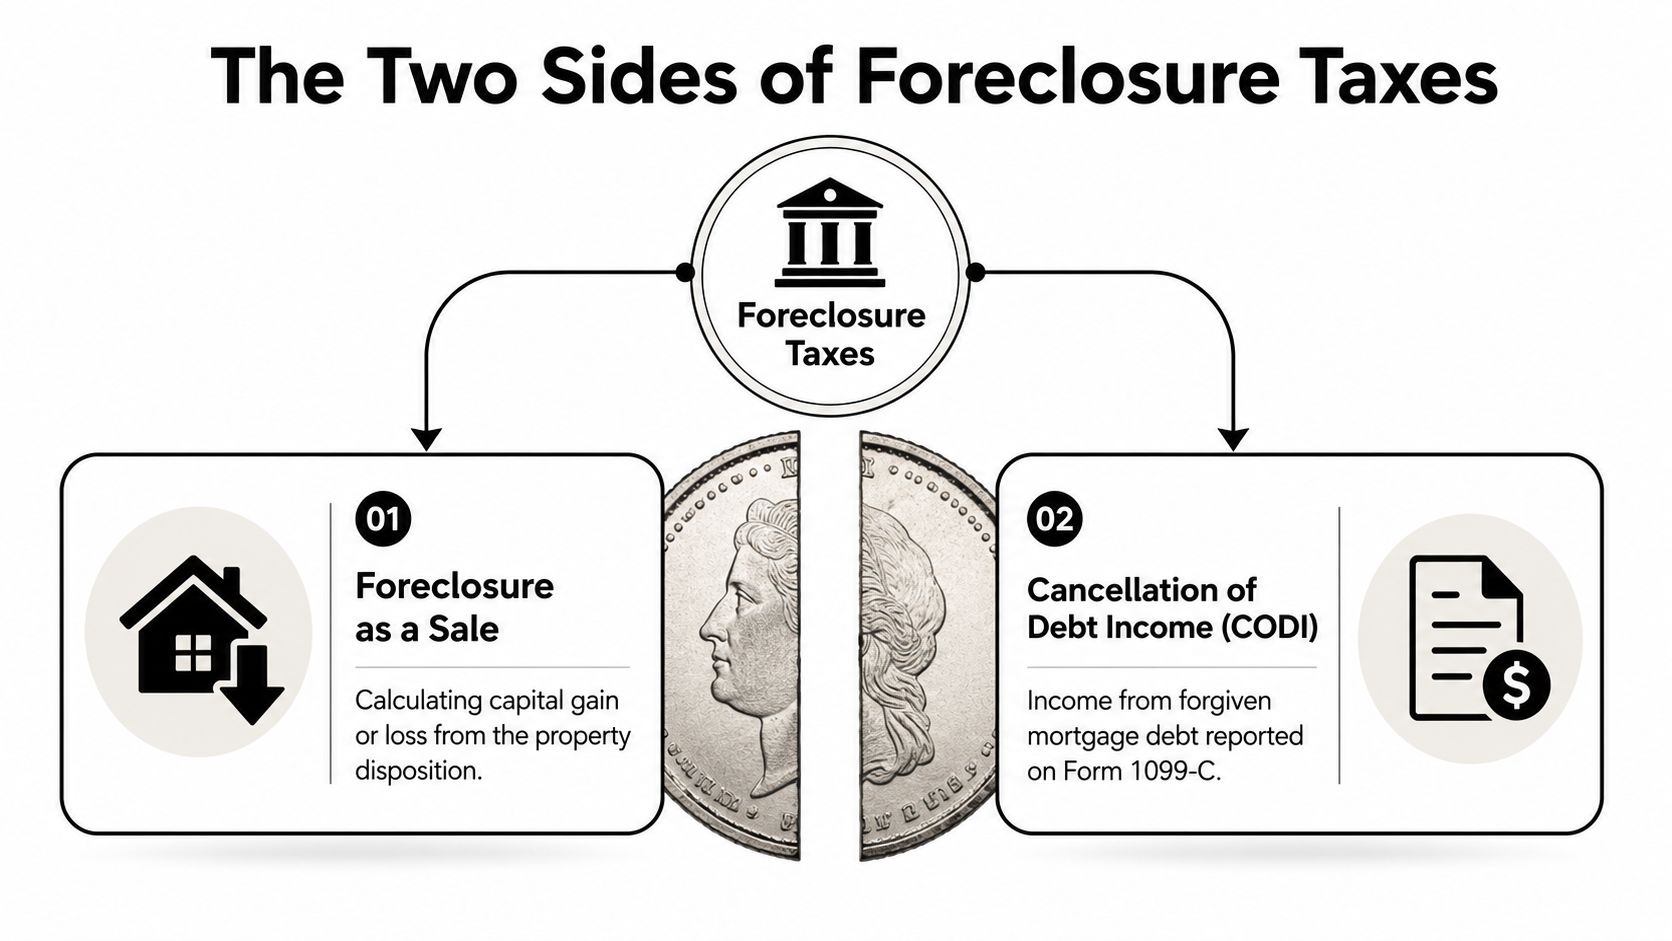
The property side of the coin
On the property side, the IRS generally treats the foreclosure as a sale or other disposition of the home. That means one question comes first: did the transfer create a gain or a loss compared with your adjusted basis?
This is the side many people recognize because it sounds like regular home sale tax rules. If you want background on how basis and gain work in a standard sale, our guide to capital gains tax on a house sale helps frame the concepts before foreclosure rules add another layer.
Here is the point many homeowners miss. If the foreclosed property was your personal residence, a loss on that property side is usually a personal loss, and personal losses are generally not deductible. In plain English, the tax law may acknowledge that you lost money on the house, but still give you no deduction for that loss.
The debt side of the coin
Flip the coin, and the question changes. Now the IRS is looking at the mortgage itself. If the lender forgave part of what you owed, that forgiven amount can be canceled debt income.
That income is separate from the gain-or-loss calculation on the home. Separate form, separate rules, separate analysis.
This is why a homeowner can face an unpleasant result that feels unfair at first glance. You may have no deductible loss on the home, yet still have taxable income because part of the mortgage balance was canceled. That is the two-sided coin in action.
Practical rule: Never assume the amount on a 1099-C matches your gain or loss on the property. They often measure different things for different tax purposes.
Why this distinction matters so much
Clients often say, "If I lost the house, surely that loss wipes out any tax bill." For a personal residence, that usually is not how the rules work. The property side and the debt side do not automatically offset each other.
A second common error goes the other direction. Some homeowners focus only on the canceled debt notice and never examine whether the foreclosure also counts as a reportable sale. Others report the sale concept but ignore the debt cancellation. Either mistake can lead to an incorrect return.
The confusion grows if the foreclosure happened while you were insolvent or involved in a bankruptcy case. In that setting, understanding bankruptcy and taxes can help you see how debt relief rules may interact with foreclosure reporting.
A simple chart helps keep the two sides straight:
| Tax side | What the IRS is measuring | Common form involved |
|---|---|---|
| Foreclosure as a sale | Gain or loss on the home | Form 1099-A |
| Canceled debt | Forgiven mortgage balance that may be income | Form 1099-C |
Keep that coin in mind as you read the rest of this guide. On one side, you are measuring what happened to the property. On the other, you are measuring what happened to the debt. Once you separate those two questions, the rules become much easier to apply correctly.
Calculating Gain or Loss on Your Property Sale
A foreclosure can feel like one event, but for tax purposes the property side has its own math. This side of the coin asks a narrower question: if the IRS treats the foreclosure as a sale, did that sale produce a gain or a loss?
The calculation follows the same basic structure used for other property sales:
- Determine your adjusted basis
- Determine your amount realized
- Compare the two
If the amount realized is more than your adjusted basis, you may have a gain. If it is less, you may have a loss.
Start with adjusted basis
Your adjusted basis is usually your starting tax investment in the home, then adjusted for later changes. In plain terms, begin with what you paid for the property and then account for items that increase or reduce basis under the tax rules.
This number matters more than many homeowners expect. If your records are incomplete, the gain or loss calculation can be wrong before you even get to the foreclosure documents.
If you want a broader refresher on how basis and gain work in a home transaction, this overview of capital gains tax on a house sale explains the same core concepts that carry over here.
If your home was in Florida, a broader Tax guide for Florida home sellers can also help as background, because the starting gain rules are similar even though foreclosure adds extra layers.
Then determine the amount realized
This is usually the part that causes confusion.
Your amount realized is the value the tax law treats you as having received when the property was taken. The tricky part is that the result can change based on whether the mortgage was recourse or nonrecourse debt. That is why two homeowners with similar loan balances can end up with very different tax outcomes.
A simple way to keep the terms straight is this:
- Adjusted basis measures your tax investment in the home
- Amount realized measures what the tax law treats as received in the foreclosure sale
Do not assume the lender's paperwork answers that question by itself. The forms are helpful, but the legal character of the loan still drives the analysis.
Why the loss often does not help on a personal residence
This is the point many clients find hardest to accept. A foreclosure can produce a real economic loss and still provide no deduction on the property side.
If the foreclosed property was your personal residence, a loss on that deemed sale is generally a nondeductible personal loss. In other words, the tax law may recognize that the sale happened, but it usually does not let you claim that personal loss on your return.
That rule is one side of the tax coin. The other side, canceled debt income, is a separate issue and does not automatically disappear just because the property sale produced a loss.
A gain is still possible
Some foreclosures do not create a loss for tax purposes. If your amount realized exceeds your adjusted basis, the foreclosure sale can produce a capital gain.
For a principal residence, that gain may still qualify for the home sale exclusion under Section 121 if you meet the ownership and use requirements. That is an important checkpoint because homeowners sometimes assume foreclosure always means a deductible loss, when the actual result can be a taxable gain, an excluded gain, or a nondeductible personal loss.
Use this short checklist before you report anything:
- Identify the property type. Principal residence, rental, and investment property do not follow the same loss rules.
- Reconstruct your basis. Gather your closing statement, improvement records, and any documents that changed your tax basis.
- Confirm the loan type. Recourse versus nonrecourse debt can change the amount realized.
- Separate the two tax questions. First compute gain or loss on the property sale. Then review whether any canceled debt creates income.
Understanding Canceled Debt Income and Form 1099-C
Many homeowners can accept that the IRS views a foreclosure as a sale. The bigger surprise is the second side of the coin. If the lender forgives debt, the IRS may treat that forgiveness as income.
Why forgiven debt can be taxable
The reasoning is straightforward even if the result feels harsh. If you borrowed money and no longer have to repay all of it, the tax law may view that canceled obligation as an economic benefit to you. That's why cancellation of debt income, often shortened to CODI, can show up on your return as ordinary income.
The most misunderstood version of this happens with recourse debt. In that setting, the tax law can split the foreclosure into two separate pieces:
| Piece of the event | Tax treatment |
|---|---|
| Basis compared with fair market value | Personal loss on a principal residence, generally not deductible |
| Fair market value compared with mortgage balance | Potentially taxable canceled debt income |
Iowa State University's legal brief puts this point clearly: for recourse debt, the difference between the home's fair market value and the mortgage balance creates taxable CODI, while the difference between the home's basis and fair market value creates a non-deductible personal loss that can't be claimed on Schedule D (Iowa State University CALT legal brief).
That is the heart of the "two sides" framework. You can lose money on the home and still have taxable income from the debt.
What Form 1099-C is telling you
Form 1099-C tells you the lender says some amount of debt was canceled. It doesn't automatically mean the amount is taxable. It does mean you need to address it.
A good first response is not panic. A better response is to ask:
- Was the debt canceled?
- Was the loan recourse or nonrecourse?
- Did the cancellation happen in the tax year shown on the form?
- Do any exclusions apply?
If you receive Form 1099-C and ignore it, the IRS may assume the full amount is taxable unless your return shows otherwise.
Homeowners also confuse 1099-C with 1099-A. The forms are related but not identical. One focuses on the acquisition or abandonment of secured property, and the other focuses on canceled debt. If you want a plain-language background on how these information returns fit into broader filing rules, this guide to 1099 filing requirements can help you understand why the IRS pays close attention to them.
How to Exclude Canceled Debt from Your Taxable Income
A homeowner can lose the house, have no deductible personal loss, and still receive a tax form showing income. That is the second side of the tax coin, and it is the part many people miss.
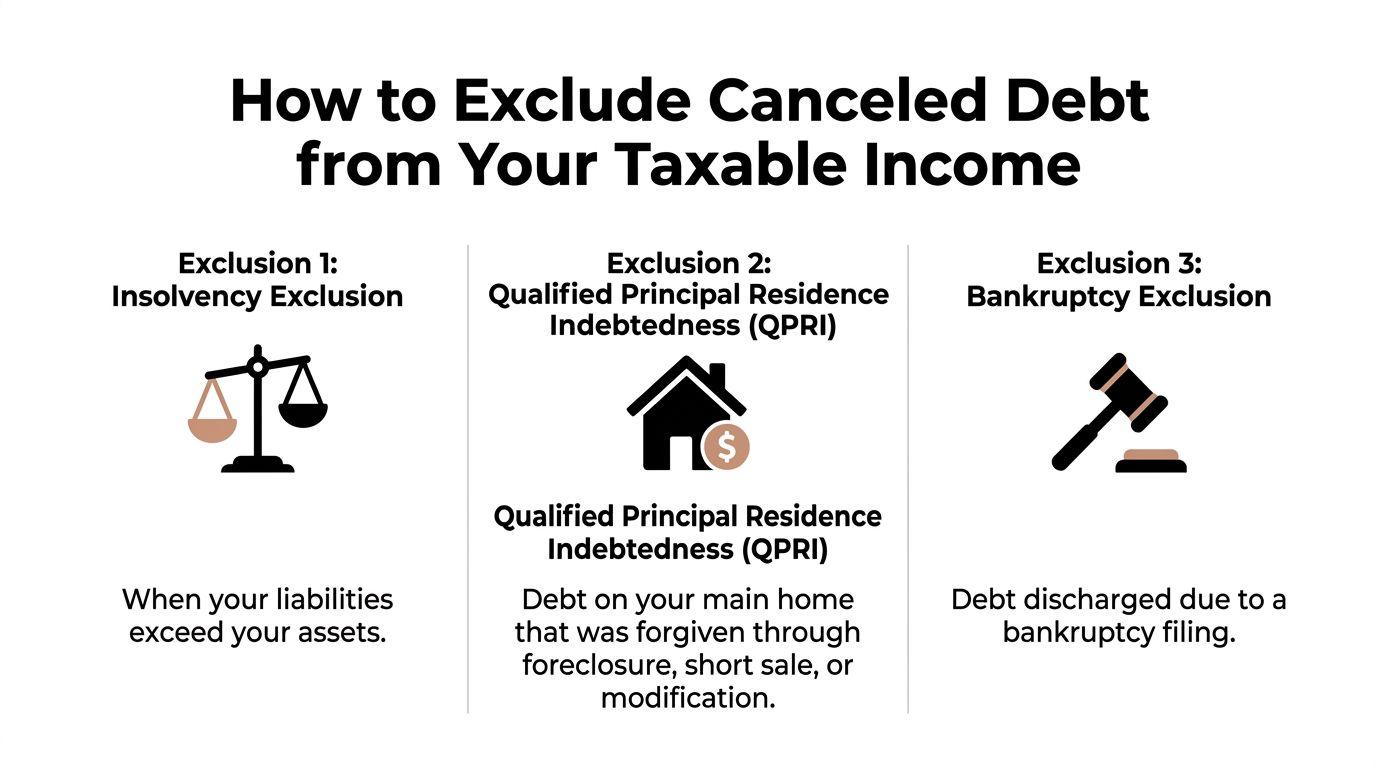
The good news is that canceled debt is not always taxable. Tax law provides several exclusions that can remove some or all of that income if the facts fit and the filing is done correctly.
Qualified principal residence debt
For many homeowners, the first exclusion to check is the one for canceled mortgage debt on a main home. Congress extended this rule through 2025, and it can apply when the forgiven debt was used to buy, build, or substantially improve your principal residence.
That last part matters. The exclusion is tied to how the loan proceeds were used, not just to the fact that the property was your home. If part of the mortgage was used for another purpose, that portion may be treated differently.
A careful review usually starts with four questions:
- Was the property your principal residence when the debt was canceled?
- Was the canceled debt used to buy, build, or improve that home?
- Did the cancellation occur in a year the exclusion is available?
- Did you report the exclusion on Form 982?
Insolvency exclusion
The insolvency exclusion works like a snapshot of your finances on the cancellation date. You compare everything you owed to everything you owned at that moment.
If your liabilities were greater than your assets, part or all of the canceled debt may be excluded, but only up to the amount of that insolvency. That limitation trips people up. A taxpayer who was underwater by $20,000 cannot exclude $50,000 of canceled debt under the insolvency rule.
This is a balance sheet exercise, not a feeling-based one.
You need records that show account balances, retirement assets, vehicle values, real estate equity, credit card balances, medical debt, personal loans, and other liabilities as of the date the lender canceled the debt. Small valuation mistakes can change the result.
Key point: A foreclosure can be financially painful without meeting the tax definition of insolvency. The tax rule depends on assets and liabilities at a specific date.
Bankruptcy exclusion
Debt discharged in a bankruptcy case may also be excluded from income. The timing has to line up with the court process, which is why this exclusion often requires a closer review of both the tax records and the bankruptcy documents.
If foreclosure and bankruptcy overlap, the order of events can affect the tax result. This overview of how bankruptcy affects taxes can help you sort out the bigger picture before filing.
Form 982 is how you claim the exclusion
Qualifying for an exclusion is only half the job. You also have to claim it properly.
Form 982 is the form used to report exclusions for canceled debt, including:
- Bankruptcy
- Insolvency
- Qualified principal residence indebtedness
A useful way to approach this is to separate the issue into two files. One file is the property sale side of the foreclosure. The other is the canceled debt side. Form 982 belongs to the canceled debt side.
A clean filing process usually looks like this:
- Match the canceled debt amount to the lender's form.
- Identify which exclusion, if any, applies.
- Gather documents that support that exclusion.
- Complete Form 982 carefully.
- Make sure the rest of the return reflects the same treatment.
That paperwork matters. If the lender sent a 1099-C and your return does not explain why the amount is excluded, the IRS may treat the canceled debt as taxable even when an exclusion was available.
Handling Special Scenarios and Common Pitfalls
A foreclosure can create tax confusion even when the facts seem simple. A homeowner loses the house, the loan is not paid in full, and a form arrives in the mail. It feels like one event. For tax purposes, it can be two separate events with different rules.
That is the mistake to avoid here.
Using the two sides of the tax coin helps. One side is the property sale. The other side is canceled debt. In unusual foreclosure situations, those two sides do not always happen at the same time, and they do not always use the same numbers.
Recourse and nonrecourse loans lead to different tax results
The first question is whether the loan was recourse or nonrecourse.
With a recourse loan, you were personally liable for the debt. If the foreclosure sale did not cover the balance, the lender may still have the right to pursue you for the difference, depending on state law and the loan terms.
With a nonrecourse loan, the property was the lender's only remedy. Once the property was taken, the lender generally could not come after you personally for the unpaid balance.
That difference matters because it changes how the two tax sides are measured.
For recourse debt, the foreclosure can split into two pieces:
- A sale side, usually based on the property's fair market value
- A debt side, for any balance the lender later cancels
For nonrecourse debt, those pieces are usually combined into the sale calculation. In practical terms, taxpayers with nonrecourse debt often do not have separate canceled debt income from the foreclosure itself.
A simple way to keep this straight is to treat recourse debt like a file with two folders. One folder is the transfer of the house. The other is any unpaid balance the lender may still collect or forgive later. Nonrecourse debt is often closer to a single folder because the unpaid debt is usually absorbed into the sale side.
Deficiency balances often create timing errors
A second common problem involves the deficiency balance.
After a foreclosure on recourse debt, the lender may still claim that you owe the remaining balance. If that happens, canceled debt income usually does not arise on the foreclosure date just because the property was taken. It generally arises later, when the lender forgives the deficiency, settles it for less than full value, or loses the legal right to collect it.
This timing point trips people up.
Some taxpayers report canceled debt too early because they assume foreclosure and debt forgiveness always happen together. Others do the opposite. They report the property transfer, then miss the later debt discharge entirely when a Form 1099-C shows up in a different year.
The tax return has to match the sequence of events, not just the emotional reality of losing the home.
Tax lien foreclosures can create a separate recovery issue
Tax lien foreclosures can add another layer. In some states, a former owner may have a right to claim excess equity or surplus proceeds after the foreclosure process. For example, Massachusetts explains current procedures and rights in its frequently asked questions on tax lien foreclosure cases in the Land Court.
That matters because a later payment to the former owner is not automatically tax-free. Its treatment depends on what the payment represents. In some cases, it may reduce or affect the property side of the transaction. In others, it may need separate analysis.
The key point is simple. Do not assume foreclosure means every dollar of value is gone forever.
Common mistakes that lead to bad filings
These errors show up often:
- Combining the sale loss and the canceled debt analysis. A personal loss on a foreclosed residence is generally not deductible. That does not answer whether canceled debt is taxable.
- Treating every 1099 form as the same type of income. A 1099-A and a 1099-C serve different purposes and may arrive at different times.
- Ignoring state law rights after foreclosure. Deficiency rules, redemption periods, and excess equity claims can all affect timing and tax treatment.
- Using the loan balance as the answer to every question. The outstanding debt, fair market value, and canceled amount may all be different numbers.
- Skipping the source documents. The note, foreclosure statement, lender notices, settlement records, and court filings often tell you which side of the tax coin you are dealing with.
If you remember one rule from this section, make it this one: the loss of the home and the forgiveness of debt may be related, but they are not the same tax event. Keeping those two pieces separate is how you avoid overstating income, claiming a loss that is not deductible, or missing a reporting requirement entirely.
A Step-by-Step Guide to Reporting Foreclosure on Your Taxes
You sit down to file your return, and the paperwork does not tell one clear story. A 1099-A talks about the property. A 1099-C talks about canceled debt. Your closing records show what you paid for the home and what you spent on improvements. The key is to sort those papers into the two sides of the tax coin before you enter anything on the return.
That step prevents one of the costliest foreclosure mistakes. Taxpayers often treat the foreclosure as one event with one answer. It is usually two tax questions. First, was there a gain or nondeductible personal loss on the property itself? Second, did the lender cancel debt that may have to be reported as income unless an exclusion applies?
The documents to gather
Pull together the records for the foreclosure year and the months that followed. Lenders do not always issue every form at the same time, so a missing form in February does not always mean it will never arrive.
You will usually want:
- Form 1099-A: Shows key facts about the acquisition or abandonment of the property.
- Form 1099-C: Shows canceled debt, if the lender discharged part or all of what you owed.
- Records for your adjusted basis: Purchase documents, closing statements, and records of capital improvements help establish your tax basis right before the foreclosure.
- Documents that support an exclusion: Bankruptcy filings, insolvency worksheets, or records tied to qualified principal residence debt if that rule applies for the year at issue.
- Lender and court correspondence: These documents can help show whether the lender pursued a deficiency, waived it, or canceled it later.
Keep these in two folders if that helps. One folder is for the home as property. The other is for the loan as debt.
The filing sequence that reduces mistakes
A clean filing order matters here because the forms can push you toward the wrong answer if you start entering them too soon.
- Classify each document before you report anything. Ask whether the document belongs to the property side, the debt side, or both. A foreclosure often creates related facts, but the reporting rules are not identical.
- Figure out the property result. Determine the amount realized under the foreclosure rules, compare it with your adjusted basis, and decide whether you have a gain or a personal loss. For a personal residence, a loss is generally not deductible.
- Analyze canceled debt separately. If you received Form 1099-C, do not assume the amount is automatically taxable. Review whether the debt was canceled and whether an exclusion applies.
- Prepare Form 982 if an exclusion applies. This is the form used to claim exclusions such as bankruptcy or insolvency.
- Report each item in the proper place on the return. The property side and the debt side do not always go on the same line or even the same form. As noted earlier, the gain or loss rules and the canceled debt rules have to be handled separately.
A simple rule helps here. Report the tax treatment, not the form by itself.
For example, entering a 1099-C as ordinary income without checking for an exclusion can overstate taxable income. Entering the foreclosure as a deductible loss on a personal residence can create a different error. The forms are starting points. They are not the final answer.
If you are dealing with taxes on a foreclosed home, slow the process down and match each document to the correct side of the transaction. That one habit can help you avoid reporting income you do not owe, missing an exclusion, or claiming a loss the tax law does not allow.
If you want help sorting out a foreclosure, canceled debt, Form 1099-C, or a possible exclusion, Allied Tax Advisors can help you review the documents, determine the right tax treatment, and file accurately with less stress.