
Choosing to become an S corp is a big step for any business owner. Before you get tangled up in the paperwork, it’s smart to take a moment and figure out if this is really the right path for you. An S corp election is a tax status, not a separate type of company, that can lead to some pretty hefty tax savings by letting profits pass directly to the owners without getting hit with corporate taxes first. It can be a huge financial win, but only if your business is truly ready for what comes with it.
Is an S Corp Election Right for Your Business?
Before you even think about IRS Form 2553, you need to take an honest look at your company’s structure, its financial health, and where you see it going. The S corp isn’t a silver bullet for every business. While the tax benefits are tempting, it also brings a whole new level of operational complexity and strict rules. If you’re not prepared, these can quickly become a headache.
Making the right call here means carefully weighing those attractive perks against the real-world drawbacks. For most business owners I talk to, the decision really boils down to one thing: tax savings.
The Allure of Pass-Through Taxation
The biggest draw for an S corp is definitely its pass-through taxation model. A traditional C corporation gets taxed on its profits, and then shareholders get taxed again when they receive dividends. It’s a classic case of “double taxation.” An S corp avoids this completely. Instead, its profits and losses are “passed through” directly to the owners’ personal tax returns, meaning the business itself pays no federal income tax.
Let’s look at a real-world example. Imagine you’re a consultant running your business as a single-member LLC, and you’ve cleared $120,000 in net profit for the year. As a standard LLC, that entire $120,000 is subject to self-employment taxes—that’s Social Security and Medicare—which hover around 15.3%. That’s a serious chunk of change going to taxes.
Now, if you elect S corp status, the game changes. You could pay yourself a “reasonable salary” of, say, $60,000. Only that salary is subject to payroll taxes. The other $60,000 can be taken as a profit distribution, which is not subject to self-employment taxes. Just by making this one strategic shift, you could save thousands of dollars every single year.
Key Takeaway: The potential to drastically cut your self-employment tax bill is the single most compelling reason for many small business owners to file for S corp status. It lets you draw a clear line between your salary and your business profits, which is key to optimizing your tax situation.
Understanding the Trade-Offs and Responsibilities
Of course, those tax savings don’t just appear out of thin air. They come with new responsibilities. When you become an S corp, you’re signing up for a higher level of administrative work. The IRS has very strict rules, and if you slip up, you could face penalties or even lose your S corp status altogether.
Here are a few of the major responsibilities you’ll have to take on:
- Running Payroll: This is a big one. You must pay yourself a “reasonable salary” as an owner-employee. That means setting up a formal payroll system, withholding the right amount of taxes, and filing payroll tax returns every quarter.
- Stricter Ownership Rules: S corps have rigid limits on who can be an owner. You can’t have more than 100 shareholders, and they all have to be U.S. citizens or residents. Other corporations and partnerships are not allowed to be shareholders.
- Formal Corporate Formalities: You’ll need to get serious about record-keeping. This includes holding regular shareholder meetings, documenting everything with corporate minutes, and maintaining official bylaws. It’s a layer of administrative work that sole props and standard LLCs don’t have to worry about.
For a business that’s growing, these formalities are often good habits to build anyway. They create that crucial separation between your personal and business finances, which strengthens the liability protection your company structure was designed to provide in the first place. If you want to dig deeper into the structure, our detailed guide on the S corporation is a great resource.
Ultimately, deciding to become an S corp is a strategic business move. It’s best suited for established businesses that have consistent, predictable profits—high enough to justify the costs and effort of running payroll and keeping up with the added paperwork. If you’re just starting out or your income is all over the place, the extra complexity could easily outweigh the tax benefits.
Meeting the Strict S Corp Eligibility Rules
Before you can start enjoying the tax advantages of an S corporation, you have to get past the gatekeepers at the IRS. These aren’t just friendly suggestions; they’re strict, non-negotiable criteria. If you miss even a single one, your S corp election will be denied, and you’ll be right back where you started.
Think of these rules as the very foundation of the S corp structure. They exist to make sure this special tax status is used by the kinds of small, domestically-owned businesses it was originally designed for. Getting a firm grip on them now is the key to a smooth and successful filing.
The Shareholder Number and Type Restrictions
First things first, an S corp is very particular about who can own it and how many owners it can have. This is probably the most common roadblock businesses run into when trying to make the switch.
For starters, your company cannot have more than 100 shareholders. This cap is designed to keep S corps from becoming massive, publicly traded companies, which are what the C corp structure is for. Honestly, for most small businesses, this 100-shareholder limit is rarely a problem.
What’s far more critical is that every single shareholder must be an “allowable” owner. The IRS has a very specific list of who qualifies:
- Individuals: This is the standard shareholder and the most common by far.
- Certain Trusts and Estates: Some specific types of trusts, like a living trust or a qualified subchapter S trust (QSST), are allowed.
- U.S. Citizens or Residents: Every shareholder must be a U.S. citizen or a legal resident. Non-resident aliens are strictly forbidden from owning S corp stock.
What’s not on that list? Other business entities. Partnerships and other corporations are not allowed to be shareholders. This is a crucial detail to consider, especially if your business has a complex ownership structure.
An S corp structure is exclusive by design. The IRS wants to prevent complex ownership webs that involve foreign entities or multiple corporate layers. The goal is to keep the pass-through tax benefit clean and simple for straightforward, U.S.-based small businesses.
The Single Class of Stock Rule
Here’s another absolute deal-breaker: an S corp can only have one class of stock. This rule trips up a surprising number of founders because it’s not just about what you call the stock; it’s about the rights that stock grants.
In simple terms, it means all shares must have the exact same rights to distributions and liquidation proceeds. You can have both voting and non-voting shares—that’s perfectly fine. The critical point is that every shareholder must share in the company’s profits and losses in direct proportion to how much of the company they own.
For instance, you can’t create a special “founder’s stock” that gets a higher dividend payout per share than the stock you issue to early employees. That would create different distribution rights, which is an immediate disqualification. All profits must be handed out based on the percentage of shares each person holds.
Why These Rules Matter for Your Filing
Confirming your eligibility is the absolute most important thing you can do before you even think about touching IRS Form 2553. The S corp has exploded in popularity for good reason. Recent data shows that around 5.9 million S corp tax returns were filed in 2023 alone, a solid 5.3% jump from the year before. This growth is heavily concentrated in sectors like professional services (16.3%), construction (13%), and real estate (11.2%), which shows just how appealing it is to a wide variety of small businesses. You can dig into more data on S corp trends from Equitable Growth.
With that kind of popularity, you can bet the IRS is watching closely. So, take a hard look at your business right now:
- Do you have more than 100 shareholders?
- Is every single owner a U.S. citizen or resident?
- Are any of your shareholders a partnership or another corporation?
- Does your operating agreement create different profit distribution rights for different owners?
If you answered “yes” to any of those questions, you’re currently ineligible. You’ll need to restructure your business to meet these requirements before you can even think about filing for an S corp election. Getting this sorted out from the very beginning will save you a world of frustration and the wasted effort of a rejected application.
Getting Your Business Ready for the S Corp Election
You can’t just wake up one morning and decide your business is an S corp. From the IRS’s point of view, an S corp isn’t a business entity itself—it’s a special tax status you elect for an existing, formally registered company. That means you need to lay the proper groundwork first.
This initial setup is non-negotiable. Rushing through it or making a mistake can lead to a rejected election, tax headaches, and legal issues you really don’t want. Think of it like pouring the foundation for a house; if it’s not solid, everything else you build on top is at risk.
Your first major decision is what kind of company to form before you make the switch. Most businesses will start as either a Limited Liability Company (LLC) or a C corporation. For a deep dive into which one makes more sense for you, check out our guide comparing S corp vs LLC structures.
First, Form Your Legal Business Entity
Once you’ve settled on the underlying structure—LLC or C corp—it’s time to make it official with your state. This isn’t a federal process; it’s all handled at the state level, and the specifics can vary depending on where you operate.
Generally, you’ll need to tackle these core tasks:
- Register Your Business Name: First, you have to make sure another company in your state isn’t already using your desired name. Most Secretary of State websites have a free, searchable database you can use for this.
- Appoint a Registered Agent: This is a person or service designated to receive official legal and tax mail on your company’s behalf. Your registered agent must have a physical street address in the state where you’re forming the business.
- File Formation Documents: For an LLC, you’ll file a document typically called the Articles of Organization. For a C corp, it’s the Articles of Incorporation. Submitting this paperwork with the state filing fee is the step that officially creates your legal entity.
Expert Tip: Don’t sleep on your internal documents, like an operating agreement (for LLCs) or corporate bylaws (for corporations). While you might not have to file them with the state, these documents are your company’s rulebook. They spell out ownership, operational rules, and how stock is handled—all crucial for proving you meet the S corp’s single-class-of-stock requirement down the line.
Next, Get Your Employer Identification Number (EIN)
Once your state has given you the green light and your LLC or corporation is officially formed, you have another must-do task: get a federal Employer Identification Number (EIN) from the IRS. An EIN is a unique nine-digit number that acts like a Social Security number for your business.
You absolutely must have an EIN before you can file Form 2553 to make the S corp election. It’s the primary way the IRS will identify your business for all tax matters. The good news? Applying for one is simple and completely free. You can do it directly on the IRS website and usually receive your number instantly.
The popularity of this structure speaks for itself. Between 1980 and 2011, the number of S corp tax returns filed exploded from roughly 545,000 to over 4.15 million—a staggering 660% increase. This surge, detailed in research on pass-through businesses from the Tax Foundation, shows just how many entrepreneurs benefit from this status. It also underscores why getting these foundational steps right is so critical.
With your legal business entity formed and your EIN secured, you’ve completed the pre-flight checklist. Now you’re ready for the main event: filing Form 2553.
A Practical Guide to Completing IRS Form 2553
You’ve got your business legally formed and your EIN is in hand. Now comes the main event: filing IRS Form 2553, “Election by a Small Business Corporation.” This is the official form you send to the IRS to switch your company’s tax status. It can look a little intimidating at first glance, but once you break it down, it’s completely manageable.
Think of this form as where the rubber meets the road. Accuracy here is everything. I’ve seen elections get rejected for the simplest mistakes—a wrong date, a forgotten signature—which can force you to start the whole process over or, even worse, make you miss the filing window for the current tax year. Let’s walk through the critical parts so you can get it right the first time.
Part I: The Core Business Information
The first section of Form 2553 is all about your fundamental business details. It’s mostly straightforward, but a few boxes need your full attention.
- Name and Address: Use the exact legal name and address your business is registered under. This must match what you used for your EIN application.
- Employer Identification Number (EIN): Double-check this nine-digit number. Then check it again. An incorrect EIN is one of the most common—and easily avoidable—reasons for rejection.
- Date and State of Incorporation: This is the date the state officially formed your LLC or C corp, not the day you started working on your business idea.
- Effective Date of Election: This is a big one. You have to pick a specific date for your S corp status to kick in. For a brand-new business, this can be your formation date. For an existing company, it’s almost always the first day of your tax year (January 1 for most).
A classic mistake is picking an effective date that doesn’t fly with IRS rules. For instance, if you’re filing in April, you can’t just put down today’s date. The election has to start at the beginning of a tax year.
The internal steps you take—like drafting bylaws and issuing stock—are the foundation for your S corp election. They give your business the formal structure the IRS expects to see.
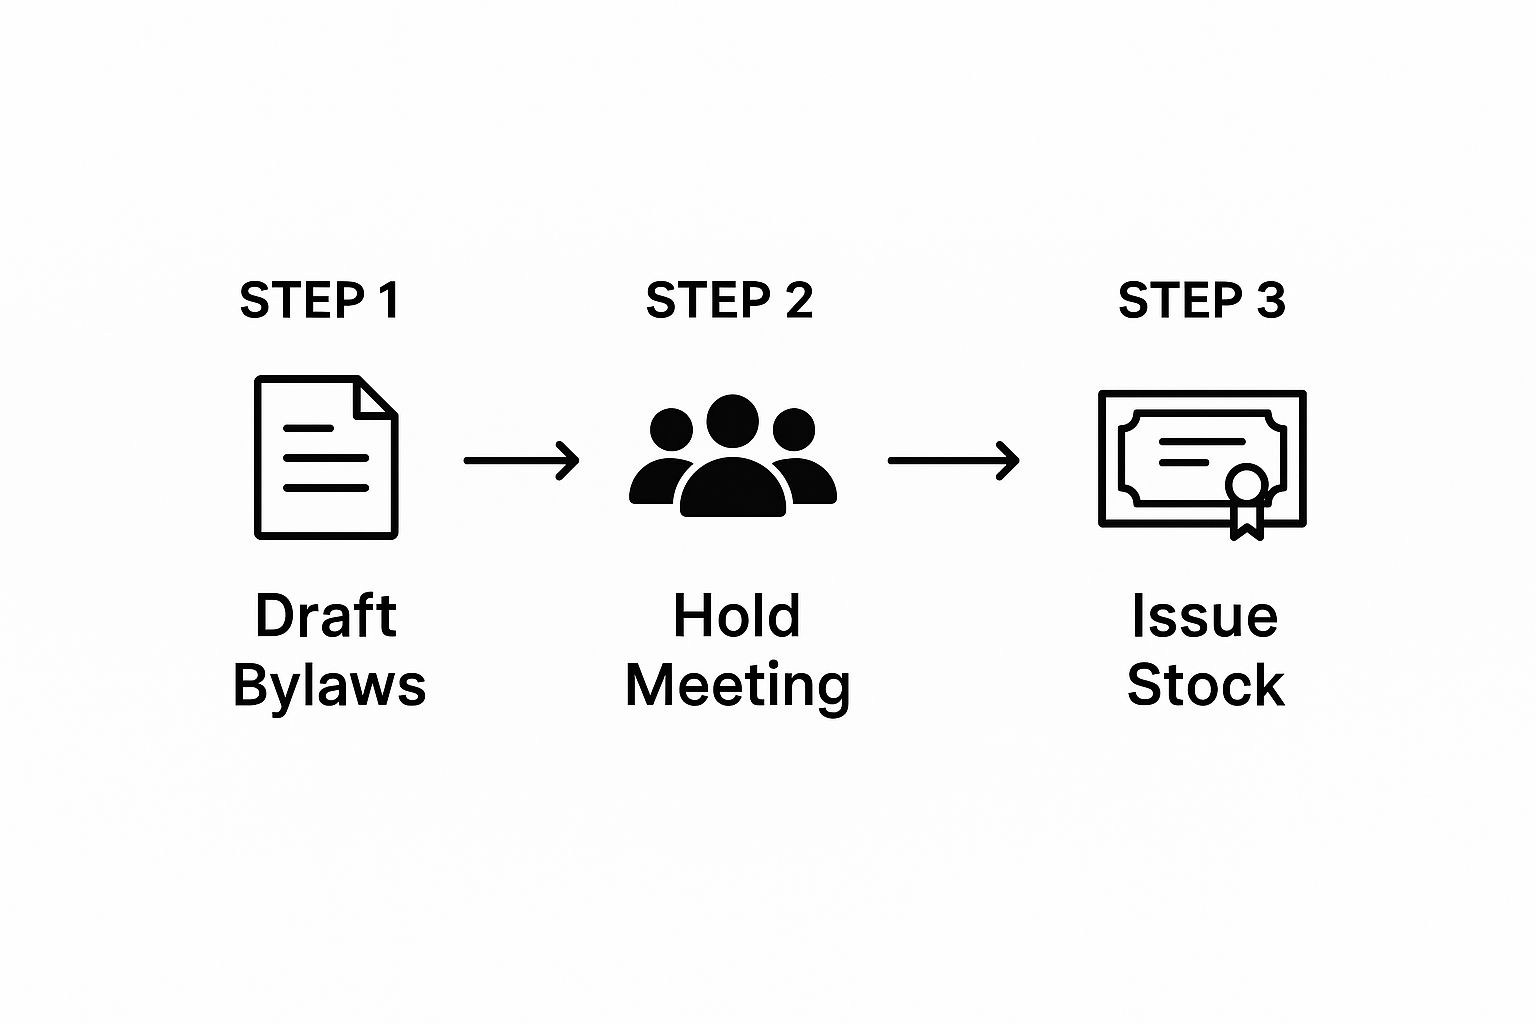
This visual shows the kind of formal corporate actions that should be in place. Having this structure reinforces the legitimacy of your business before you even send Form 2553 to the IRS.
Deadlines and Filing Your Form on Time
Timing is everything with Form 2553. To make sure your S corp election is effective for the current tax year, you need to file it within the first two months and 15 days of that tax year. If you run on a calendar year, your deadline is March 15.
Here’s a quick breakdown of the key filing deadlines.
IRS Form 2553 Filing Deadlines
This table outlines the critical deadlines for submitting Form 2553 to ensure your S corp election is accepted for the desired tax year.
| Filing Scenario | Deadline for Form 2553 Submission |
|---|---|
| Existing Business (Calendar Year) | No later than March 15 of the current tax year. |
| New Business | Within two months and 15 days of your official date of incorporation. |
| For the Next Tax Year | Can be filed at any time during the preceding tax year. |
Getting this form in on time prevents a lot of headaches, so be sure to mark these dates on your calendar.
Navigating Shareholder Consent and Tax Years
After you’ve entered the basic details, the form moves on to shareholders and your tax year. This is where I see a lot of business owners get tripped up.
Column K requires every single shareholder to consent to the S corp election in writing. Every person who owns stock as of the election date must sign and date the form. You’ll also need to list their name, address, Social Security number, and the number of shares they own. A missing signature is an automatic rejection, so be meticulous.
Next up is your tax year. The vast majority of small businesses use a calendar year ending on December 31, and honestly, it’s the simplest way to go. If you have a solid business reason for a different fiscal year—like a highly seasonal business—you’ll have to justify it in Section B of Part I.
One of the top unforced errors I see is a forgotten shareholder signature. If you have multiple owners, get everyone on the same page to make sure they all sign. For spouses who co-own shares, both individuals need to sign separately.
What to Do If You File Late
Life happens. Sometimes deadlines get missed. If you miss the standard filing window, don’t panic—Part IV, Late Election Relief, might be your saving grace.
The IRS provides a potential fix if you have a reasonable cause for filing late. To qualify for this relief, you have to meet a few conditions:
- You truly intended for the business to be an S corp from the effective date you wanted.
- Your failure to file on time was due to a reasonable cause.
- The corporation and all its shareholders have reported their income consistent with an S corp for all the years the election was supposed to be in effect.
If you check all these boxes, you can fill out Part IV and attach a statement explaining your reasonable cause. Common examples that work include getting bad advice from a tax professional or simply not being aware of the rule despite your best efforts. Relief isn’t guaranteed, but it provides a critical lifeline if you’ve missed the initial deadline. Getting this part right is your key to fixing a late filing and getting the S corp status you wanted, retroactively.
Filing with Your State After Federal Approval
Getting that S Corp acceptance letter from the IRS feels like a huge win. For many business owners, it seems like the final step. But hold on—celebrate, but don’t stop just yet. A common and costly mistake I see people make is assuming that federal approval automatically translates to their state. That assumption can lead to some nasty surprises, like compliance headaches and unexpected tax bills down the line.
The reality is, states are all over the map when it comes to S Corps. Figuring out your state’s rules is a non-negotiable part of the process. While a lot of states will honor your federal election without a fuss, a surprising number won’t. You absolutely have to check your state’s specific requirements to make sure you’re buttoned up on all fronts.
State Recognition Varies—A Lot
The good news? Most states do what’s called “conformity.” This just means if the IRS gives you the S Corp nod, your state does too, with no extra paperwork needed from you. Business owners in states like California and Illinois have it a bit easier because of this.
But then there are the others. A handful of states demand their own, separate S Corp election filing. If you miss this step, you could find yourself in a weird spot: you’re an S Corp for federal taxes but still a C Corp or LLC for state taxes. This can completely wipe out the tax advantages you were aiming for in the first place.
Here are a few common examples of states that require their own forms:
- New York: You’ll need to file Form CT-6, Election by a Federal S Corporation to be Treated as a New York S Corporation.
- New Jersey: They require Form CBT-2553, S Corporation Election, and you have to get it in within about a month of your federal filing.
- Arkansas: To make it official here, you need to file Form AR1103, S Corporation Election.
Expert Tip: My best advice is to never, ever assume. Go straight to the source. A quick visit to your state’s Department of Revenue or Secretary of State website is all it takes. Search for “S corporation election” and you should find exactly what you need to know.
How to Find Your State’s Requirements and Forms
Your state’s Department of Revenue (or whatever they call their tax agency) is your source of truth. Head to their website and look for the business or corporate tax section. That’s where you’ll find the information and, if needed, the specific forms for a state-level S Corp election.
If you discover your state does require a separate filing, pay very close attention to the deadlines. Some states give you a pretty tight window after the IRS approves your election to get your state paperwork submitted. Missing that deadline could mean you lose your S Corp status for the entire tax year at the state level, which often results in a much higher tax bill.
Don’t Forget About Other State-Specific Taxes
Even after you’ve locked in your S Corp status with both the feds and the state, you’re not entirely off the hook. Many states have other business taxes that apply to everyone, S Corps included.
Keep an eye out for things like:
- Franchise Taxes: This is basically a fee for the privilege of doing business in the state. It’s often calculated based on your company’s net worth or assets.
- Minimum Taxes: Think of this as an annual flat fee. Even if your business didn’t turn a profit, you still have to pay it. California’s annual minimum franchise tax is a classic example of this.
The S Corp has absolutely exploded in popularity, with filings jumping by an incredible 839 percent between 1980 and 2021. As more founders choose this path, it’s become even more critical to be diligent. If you want to dive deeper into this trend, check out this primer on S corporations from the American Action Forum. Staying on top of these state-level details ensures you won’t get blindsided when it’s time to file your state return.
How to Keep Your S Corp Status for the Long Haul
Getting your S corp election approved by the IRS is a huge win, but that’s just the starting line. The real challenge—and where the real value lies—is in keeping that status intact year after year. To protect the tax benefits you worked so hard to get, you have to stay on top of ongoing compliance. If you don’t, the IRS can step in and terminate your election, which is a headache you definitely want to avoid.
The key is to build good habits from the very beginning. You have to treat your S corp like the separate, formal business entity it is. These corporate formalities aren’t just suggestions; they’re strict requirements that protect your personal assets and keep your business structure sound.
Pay Yourself a Reasonable Salary Through Payroll
This is probably the most critical part of S corp maintenance. If you’re an owner who works in the business, you absolutely must run payroll and pay yourself a reasonable salary. That salary gets hit with FICA taxes (Social Security and Medicare), just like any employee’s wages. Only after paying yourself a proper salary can you take profit distributions.
So, what’s “reasonable”? The IRS is a bit vague, but they define it as what a similar business would pay someone for the same work. They’ll look at your experience, your job duties, and how much money your company is bringing in. Trying to game the system by paying yourself a tiny salary and taking huge distributions is a massive red flag for an audit. Don’t do it. Running proper payroll isn’t optional.
Hold Meetings and Keep Meticulous Records
To maintain that corporate veil that protects your personal assets, you have to act like a corporation. This means holding formal annual meetings for shareholders and directors. Yes, even if it’s just you in the room. In these meetings, you should officially discuss and approve major business decisions, review the company’s financials, and plan for the future.
The golden rule here is to document everything. You need to keep detailed corporate minutes from these meetings. These written records are your official proof that the business is a separate legal entity, which is absolutely crucial for shielding your personal assets if the business ever gets into trouble.
File Your Annual Returns and Steer Clear of Common Pitfalls
Each year, your S corp has to file an informational tax return, Form 1120-S, with the IRS. This form details the company’s income, expenses, profits, and losses. That information then “passes through” to the shareholders on a Schedule K-1, which they use to file their personal taxes.
Beyond the annual filing, you need to be careful to avoid a few common mistakes that can get your S corp status terminated by accident.
- Watch Out for Ineligible Shareholders: You can’t just sell or give stock to anyone. Bringing on a non-U.S. citizen, another corporation, or a partnership as a shareholder will instantly kill your S corp election.
- Don’t Create a Second Class of Stock: This is another big one. All shares in an S corp must have the same rights to distributions. You can’t create different payout plans for different owners—that violates a core S corp rule.
Juggling these ongoing tasks is vital. If you need help staying on top of compliance and making smart tax decisions, you might want to explore professional business taxation services. Being proactive is the best way to make sure your S corp continues to be a powerful asset for your financial future.
Answering Your Top S Corp Questions
When you’re digging into the S corp election process, it’s natural for a bunch of specific questions to pop up. Feeling stuck on one of these “what if” scenarios is common, but getting them answered can save you from simple missteps and give you the confidence to push forward.
What Happens If I Miss the Filing Deadline?
So you missed the deadline to file Form 2553. Don’t panic—it doesn’t automatically mean you have to wait until next year.
The IRS actually has a built-in fix for this exact situation. It’s called late election relief, and you’ll find the instructions for it in Part IV of the form. To qualify, you’ll need to show you had a reasonable cause for the delay. Maybe you got some bad advice from a professional, or perhaps you were genuinely unaware of the deadline despite doing your due diligence. If the IRS accepts your explanation, they can make your S corp status retroactive to the tax year you originally wanted.
Can My LLC Really Become an S Corp?
Yes, it absolutely can. In fact, this is one of the most common and effective tax strategies for LLC owners.
It’s important to understand that you aren’t changing your company’s legal structure. Instead, you’re just telling the IRS you want to be taxed differently. The process involves filing Form 8832 to be treated as a C corp for tax purposes, and then immediately following that up with Form 2553 to elect S corp status.
Think of it as a two-step tax move, not a legal one. Your business stays an LLC under state law, which means you get to keep the operational flexibility you love while gaining the tax benefits of an S corp. It’s the best of both worlds.
What Exactly Is a “Reasonable Salary”?
This is a big one, and the IRS is very clear about it. As an S corp owner who works in the business, you must pay yourself a reasonable salary before you take any profit distributions.
So, what’s considered “reasonable”? It’s what a similar company would pay someone for doing the same job.
A few factors come into play here:
- What are your actual duties and responsibilities?
- What’s your background and level of expertise?
- How is the company doing financially? Look at gross profits and overall health.
A great starting point is to research salary data for your role within your specific industry and geographic area. This helps you establish a number that you can confidently defend if ever asked.
Getting these details right is where having an expert in your corner really pays off. The team at Allied Tax Advisors has spent decades guiding business owners through successful S corp filings and helping them stay compliant. You can learn more about how Allied Tax Advisors can support your business on their website.
Article created using Outrank