
Tax season often feels like navigating a maze, but with the right map, it becomes a clear path to financial accuracy and peace of mind. Our definitive 2025 small business tax preparation checklist is designed to be that map. Whether you're a sole proprietor just starting, a multi-member LLC, or a seasoned S Corp, this guide breaks down the complex process into manageable, actionable steps. We provide a structured approach to ensure you have every document, figure, and form ready for a smooth filing experience.
This comprehensive guide moves beyond a simple list of documents. We will detail everything from organizing financial records and bank statements to accurately calculating business income and compiling expenses for maximum deductions. You will find specific instructions on how to document a home office, gather vehicle mileage records, and manage your 1099 forms. By following this checklist, you'll not only ensure compliance but also uncover opportunities to optimize your tax position, transforming tax time from a source of stress into a strategic advantage for your business.
To truly master your 2025 taxes, it's crucial to stay updated on recent legislative changes. For instance, you might want to look into the impact of the changes brought by Trump's 'Big Beautiful' Tax Bill on various business deductions. Understanding how such reforms affect areas like asset depreciation and pass-through income is key to accurate filing. This checklist will equip you with the foundational knowledge needed to prepare for these nuances, ensuring no detail is overlooked and no potential saving is missed. Let's begin building a stress-free and strategically sound approach to your business taxes.
1. Organize Financial Records and Bank Statements
The cornerstone of any successful small business tax preparation checklist is meticulous financial organization. Before you can calculate income, identify deductions, or file a single form, you must have a complete and orderly collection of your financial data from the entire tax year. This foundational step involves gathering all bank and credit card statements from January 1st to December 31st and creating a system to categorize and access them efficiently.
Neglecting this step creates a chaotic and stressful tax season, leading to missed deductions and potential inaccuracies that could trigger an audit. A well-organized system provides a clear financial picture, empowering you and your tax professional to prepare an accurate return that maximizes your savings.
Why This is the First Step
Think of your financial records as the raw ingredients for your tax return. Without them, you can't cook the books, so to speak. A local coffee shop, for instance, needs to consolidate its point-of-sale (POS) reports, supplier invoices, and business bank deposits to get a true picture of its revenue and expenses. Similarly, a freelance graphic designer must pull together records from multiple payment platforms like Stripe, PayPal, and direct bank transfers to accurately report their total income.
Actionable Tips for Implementation
- Establish a System Early: Don't wait until tax season. At the start of the year, create dedicated folders, either physical or digital (e.g., in Google Drive or Dropbox), for each month and each account. This proactive approach turns a year-end mountain into small, manageable monthly tasks.
- Leverage Technology: Accounting software like QuickBooks or Xero can automatically import and categorize transactions from your business accounts. This significantly reduces manual data entry and human error.
- Reconcile Monthly: The single most effective habit is to reconcile your bank and credit card statements every month. This practice ensures discrepancies are caught early and provides a running, accurate tally of your financial health, preventing a last-minute scramble.
- Retain Records: The IRS generally recommends keeping tax records for at least three to seven years, depending on the circumstances. Securely storing digital or physical copies protects you in the event of an audit. For more insights on this, read about how to organize business receipts effectively.
2. Calculate Business Income and Revenue
Accurately calculating your total business income is a critical component of any small business tax preparation checklist. This step involves summing up all revenue from every source throughout the tax year, including sales of goods, fees for services, and any other income-generating activities. Properly calculating your gross revenue and then subtracting returns and allowances is essential for establishing the correct starting point for your tax return.
Underreporting income, even accidentally, can lead to significant penalties, interest, and audits from the IRS. A precise calculation ensures compliance and provides a clear, defensible foundation for your entire tax filing. It also gives you valuable insight into your business's financial performance over the year.
Why This is a Critical Step
Your gross income is the top line on your tax return from which all deductions and credits are subtracted. An error here affects every subsequent calculation. For example, an e-commerce store must reconcile sales from multiple platforms like Shopify, Amazon, and direct website sales to arrive at a single, accurate revenue figure. Similarly, a consulting firm needs to consolidate all paid invoices from various clients to report its total service income correctly.
Actionable Tips for Implementation
- Leverage Accounting Software: Use tools like QuickBooks or Xero to generate automated income or profit-and-loss reports. These systems centralize data from different payment processors and bank accounts, providing an accurate, real-time view of your total revenue.
- Track Revenue by Source: Categorize your income streams to identify your most profitable business segments. This not only aids in tax preparation but also informs strategic business decisions for the coming year.
- Cross-Reference 1099 Forms: If you receive Forms 1099-NEC or 1099-K from clients or payment processors, carefully compare the amounts reported on these forms with your own records. Discrepancies must be resolved to avoid IRS inquiries.
- Document Non-Cash Income: Don't forget to include non-cash transactions, such as bartering for goods or services. You must report the fair market value of what you received as income. Keeping detailed records of these exchanges is crucial for accurate reporting.
3. Compile and Categorize Business Expenses
Once your income is accounted for, the next critical task in any small business tax preparation checklist is to meticulously compile and categorize all your business expenses. Systematically gathering and organizing every legitimate business cost from the tax year is the key to maximizing deductions and ensuring your tax return is accurate. This involves sorting expenses into logical categories such as supplies, equipment, utilities, rent, and professional fees.
Failing to properly categorize expenses means you risk leaving money on the table through missed deductions. More importantly, it can create a messy financial picture that complicates filing and could attract IRS scrutiny. A well-organized expense ledger allows you to claim every dollar you are entitled to, reducing your taxable income legally and effectively.
Why This is an Essential Step
Your business expenses are the direct offset to your gross income. The more legitimate deductions you can claim, the lower your taxable profit will be. For example, a home-based consultant must diligently track the business-use percentage of their internet, phone, and utility bills to claim a home office deduction. Similarly, a small manufacturing business needs to properly categorize raw materials, labor costs, and facility rent to accurately calculate its cost of goods sold and operating expenses.
Actionable Tips for Implementation
- Implement Receipt Capture Tools: Use apps like Expensify or Dext (formerly Receipt Bank) to digitally capture and categorize receipts on the go. This eliminates the risk of losing paper receipts and automates a significant portion of the work.
- Establish a Chart of Accounts: Create a standardized chart of accounts based on IRS guidelines. This framework ensures consistency and makes it easy to map your expenses to the correct lines on your tax forms. For more detail, read about how to categorize expenses in QuickBooks.
- Use Dedicated Business Accounts: Funnel all business spending through a dedicated business credit card or bank account. This practice creates a clean, centralized record of your expenses and simplifies the reconciliation process.
- Don't Overlook Small Deductions: Seemingly minor costs add up. Remember to track expenses like business-related software subscriptions, professional development courses, bank fees, and industry publication memberships.
4. Document Home Office Deduction
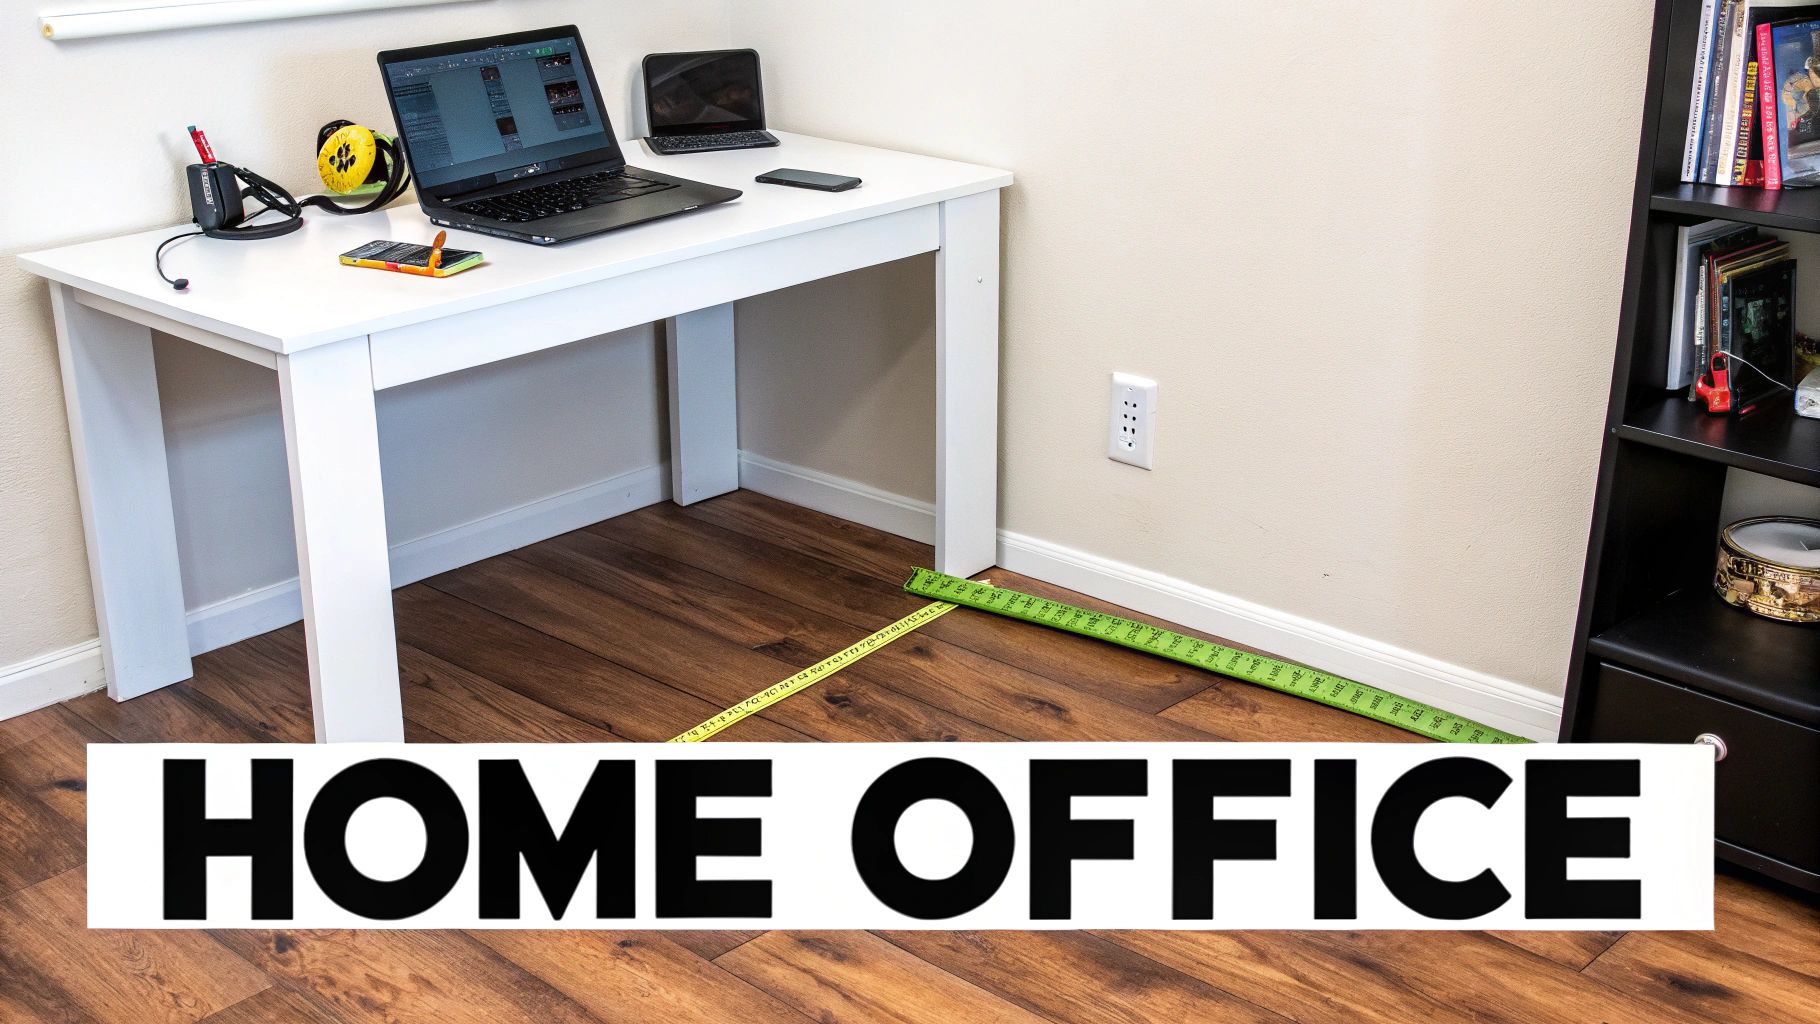
For the millions of small businesses run from a spare room, basement, or dedicated studio, the home office deduction is a powerful tool for reducing taxable income. To claim it, you must use a part of your home exclusively and regularly for business purposes. Properly documenting and calculating this deduction is a key part of any small business tax preparation checklist and can lead to substantial savings.
Failing to properly substantiate your claim can result in its disallowance during an audit. Careful record-keeping not only ensures you comply with IRS rules but also helps you choose the calculation method that yields the greatest tax benefit for your specific situation.
Why This is an Essential Step
The home office deduction allows you to convert a portion of your personal living expenses into legitimate business write-offs. For example, a virtual assistant with a 200-square-foot dedicated office can use the simplified method to claim an easy $1,000 deduction (200 sq. ft. x $5). In contrast, a CPA operating from a larger home office might use the regular method to deduct a percentage of their actual rent, utilities, insurance, and home repairs, potentially resulting in a much larger deduction.
Actionable Tips for Implementation
- Measure and Document Your Space: Precisely measure the square footage of your dedicated office. Calculate this as a percentage of your home's total square footage and take photos to document that the space is used exclusively for business.
- Choose Your Method: The IRS offers two options. The simplified method allows a standard deduction of $5 per square foot (up to 300 sq. ft.). The regular method requires tracking the actual costs of your home (mortgage interest, property taxes, utilities, repairs) and deducting the business-use percentage.
- Maintain Meticulous Expense Records: If using the regular method, keep detailed records and receipts for all home-related expenses throughout the year. This includes utility bills, homeowners insurance, and invoices for repairs.
- Understand the "Exclusive Use" Rule: The space must be used only for your trade or business. A desk in the corner of your family's living room generally won't qualify, but a separated room or area will.
5. Gather Vehicle and Mileage Records
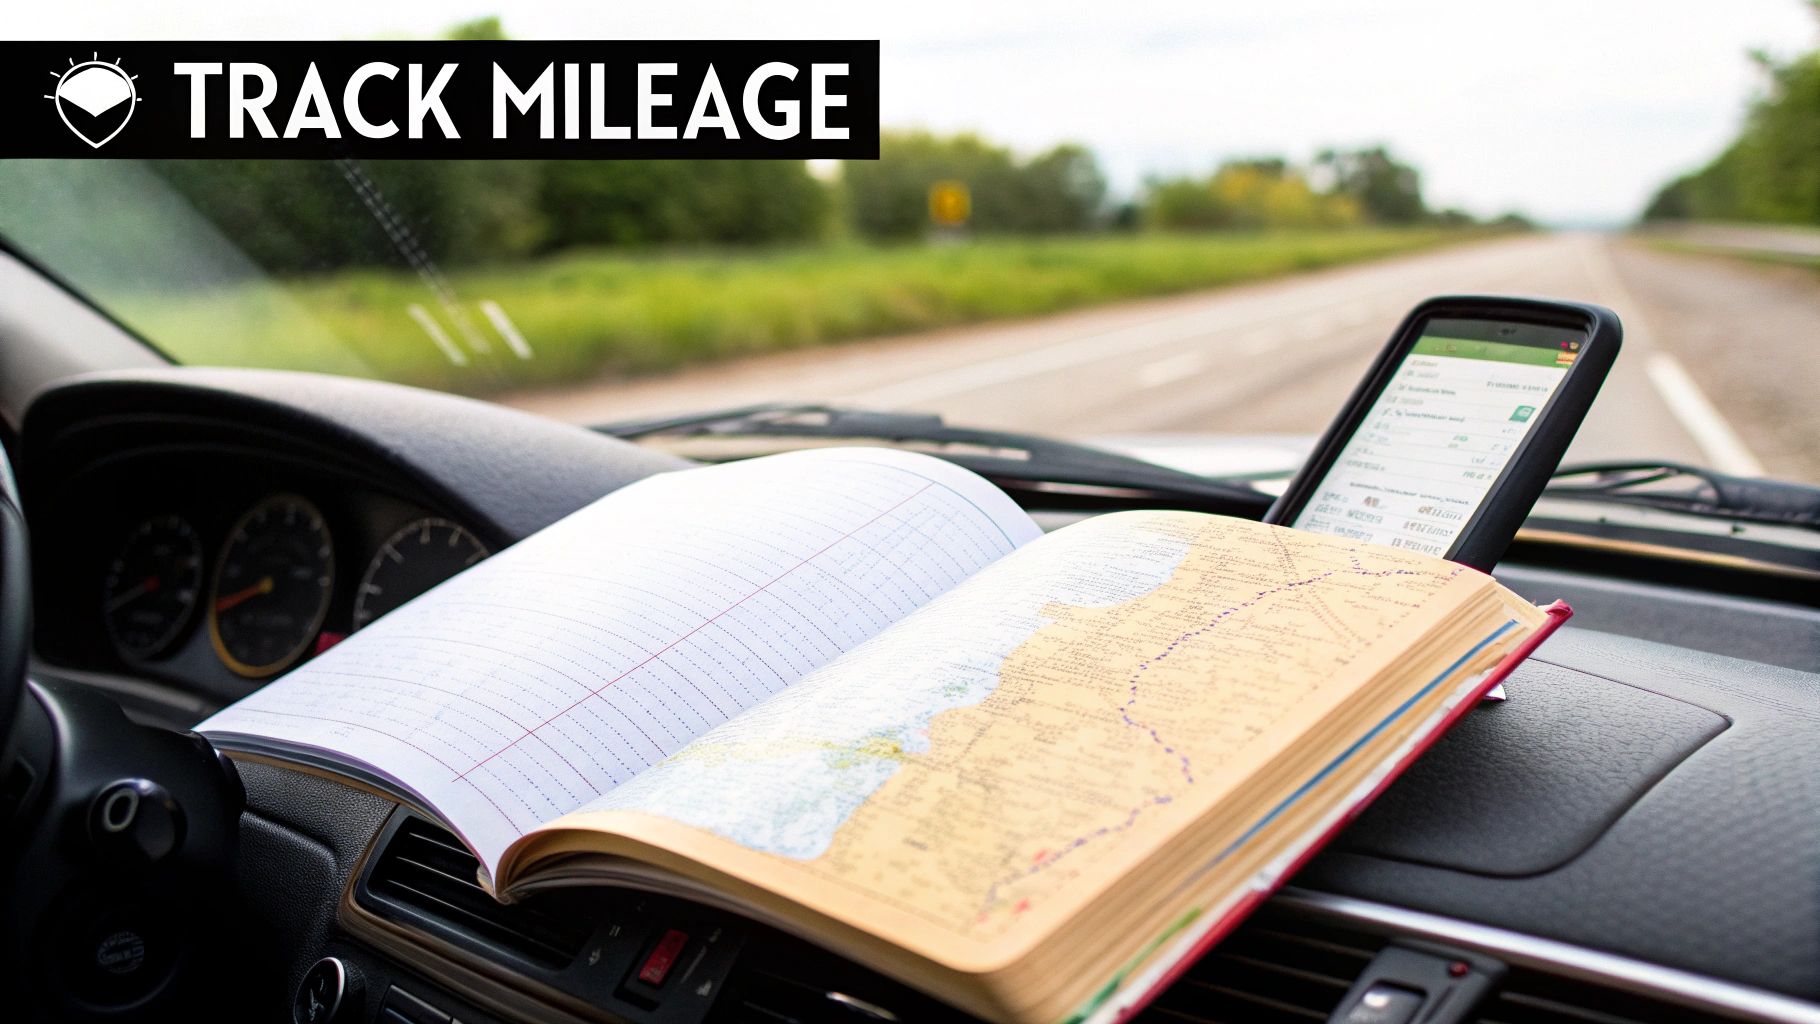
For many small businesses, vehicle expenses represent a significant and often overlooked tax deduction. Properly documenting your business vehicle usage is a critical part of any comprehensive small business tax preparation checklist. Whether you use your personal car for business errands or have a dedicated company fleet, maintaining meticulous records is essential for substantiating your claims with the IRS.
Failing to keep contemporaneous logs can result in disallowed deductions and costly penalties during an audit. By gathering these records, you can choose between two methods for claiming this deduction: the standard mileage rate or the actual expense method, each offering different benefits depending on your specific circumstances.
Why This is an Essential Step
Your vehicle logs are the primary evidence needed to prove business use. Without them, you cannot legally claim the deduction. For example, a real estate agent who drives 15,000 business miles can claim a deduction of $10,050 using the 2024 standard rate of 67 cents per mile. Alternatively, a plumbing business with a dedicated work van might find the actual expense method more beneficial, deducting $8,000 in depreciation plus another $3,500 for fuel and repairs.
Actionable Tips for Implementation
- Use a Mileage Tracking App: Simplify record-keeping with apps like MileIQ or Stride. These tools use your phone's GPS to automatically track drives, allowing you to easily classify trips as business or personal with a simple swipe.
- Maintain a Physical Backup: Technology can fail. Keep a simple, physical logbook in your vehicle's glove compartment as a reliable backup. Record the date, starting and ending odometer readings, total mileage, and the business purpose of each trip.
- Document Contemporaneously: Record your mileage and the purpose of your trip at the time it happens, not weeks or months later. The IRS requires contemporaneous records, and reconstructing logs at year-end is a major red flag.
- Separate Commuting Miles: The drive from your home to your primary place of business is considered commuting and is not a deductible business expense. Be sure to exclude these miles from your business log.
- Collect All Receipts for Actual Expenses: If you plan to use the actual expense method, you must retain every receipt for gas, oil changes, insurance, registration fees, repairs, tires, and lease payments. For more guidance on managing these costs, explore our specialized small business tax services.
6. Review and Organize 1099 Forms
For many small businesses, especially those in the service industry or gig economy, income doesn't just come from direct sales; it's often reported by clients on Form 1099. Properly collecting, reviewing, and reconciling all 1099 forms you receive is a non-negotiable part of your small business tax preparation checklist. These forms are direct reports of your income to the IRS, so any discrepancies between them and your records can raise red flags.
Neglecting this step can lead to underreporting income, a major compliance issue that attracts IRS attention. A systematic review ensures the income you report matches what the government has on file, preventing automated notices, penalties, and potential audits. This process solidifies the accuracy of your gross income calculation before you even begin factoring in deductions.
Why This is a Critical Step
Think of each 1099 as an official witness statement to the IRS about your income. If your tax return tells a different story, you need a very good reason why. A freelance marketing consultant, for example, must gather all their 1099-NEC forms from various clients. If their invoices total $95,000 for the year, but the 1099s only add up to $92,500, they still must report the full $95,000. Conversely, if a 1099 reports more income than was received, it's crucial to get it corrected immediately.
Actionable Tips for Implementation
- Create a 1099 Tracking System: Maintain a simple spreadsheet listing every client who should issue you a 1099 (those who paid you over $600). As each form arrives, check it off the list. The deadline for payers to send 1099s is January 31st.
- Reconcile Against Your Records: Compare the amount on each 1099 against your own invoicing and payment records in your accounting software. Do they match exactly? If not, investigate the discrepancy right away.
- Request Corrections Immediately: If you find an error on a 1099, contact the issuer promptly and request a corrected form. Document all your communications in writing. An incorrect 1099 can lead to you overpaying taxes on income you never received.
- Keep Meticulous Copies: Store digital or physical copies of every 1099 form you receive with your tax records. The IRS recommends keeping these records for a minimum of three to seven years, as they are primary evidence of your reported income.
7. Calculate Quarterly Estimated Tax Payments
Unlike W-2 employees who have taxes withheld from each paycheck, small business owners are responsible for paying their own income and self-employment taxes throughout the year. This is accomplished through quarterly estimated tax payments, a critical component of any small business tax preparation checklist that helps you avoid a large tax bill and potential underpayment penalties when you file your annual return. This process involves projecting your total annual income and tax liability and paying it in four installments.
Failing to make these payments, or paying too little, can result in penalties from the IRS. Staying on top of quarterly estimates ensures you meet your tax obligations incrementally, making tax season less financially burdensome and keeping your business in good standing with federal and state authorities.
Why This is an Ongoing Task
Estimated taxes are the pay-as-you-go system for entrepreneurs. A freelance consultant projecting $80,000 in net income for the year might estimate their total tax liability to be $20,000. They would then pay this amount in four installments of $5,000 each quarter. Likewise, if a retail business has a much stronger first half of the year than anticipated, they must adjust their Q3 and Q4 payments upward to account for the increased income and avoid an underpayment penalty.
Actionable Tips for Implementation
- Use Last Year as a Guide: A good starting point is to use your prior year's income and tax liability. Adjust these figures based on any expected growth or changes in your business for the current year.
- Utilize the IRS Worksheet: The IRS provides a worksheet with Form 1040-ES, Estimated Tax for Individuals, to help you calculate your expected adjusted gross income, deductions, and credits. This is an essential tool for an accurate projection.
- Set Aside Funds Consistently: A practical habit is to set aside 25-30% of your net business income each month in a separate savings account. This ensures the funds are available when quarterly payment deadlines arrive.
- Review and Adjust Quarterly: Your business income can fluctuate. Before each payment deadline, review your year-to-date income and re-project for the rest of the year. Adjust your payment up or down as needed to stay on track. For a deeper dive, read our guide on how quarterly estimated tax payments work.
8. Verify Retirement Plan Contributions
A powerful tool in any small business tax preparation checklist is the strategic use of retirement plans. Documenting and verifying contributions to qualified plans like a SEP-IRA, Solo 401(k), or SIMPLE IRA is not just about saving for the future; it's a critical step for significantly reducing your current taxable income. Business owners can make substantial contributions for themselves and their employees, turning a future-focused financial goal into an immediate tax advantage.
Failing to properly document these contributions means leaving one of the most valuable small business deductions on the table. Accurate records ensure you claim the maximum allowable deduction, directly lowering your tax liability and helping you build wealth more efficiently. This step transforms retirement savings from a personal finance task into a core component of your business tax strategy.
Why This is a Key Deduction
Retirement contributions are an above-the-line deduction, meaning they reduce your adjusted gross income (AGI) before you even get to standard or itemized deductions. For a small business owner, this is a direct and impactful way to lower their tax bill. For example, a solo consultant with $80,000 in net self-employment income can contribute up to 20% of that income to a SEP-IRA. A contribution of $16,000 would directly reduce their taxable business income to just $64,000.
Actionable Tips for Implementation
- Establish Plans Promptly: While you can often make contributions for the previous tax year up until the tax filing deadline (including extensions), the plan itself must typically be established by December 31st of that year. Plan ahead to avoid missing out.
- Document Every Contribution: Keep meticulous records of all contributions made. This includes transaction receipts and year-end statements from the plan custodian (e.g., Fidelity, Vanguard). These documents are your proof for the deduction.
- Maximize Contribution Types: If you have a Solo 401(k), remember you can contribute as both the "employee" and the "employer," significantly increasing your potential deduction compared to other plans.
- Consider Catch-Up Contributions: If you are age 50 or older, you are eligible to make additional "catch-up" contributions. This is a fantastic opportunity to accelerate your savings and further reduce your tax burden. For more tailored advice, consider a consultation on small business tax strategies.
9. Collect Receipts and Invoices Documentation
While organized financial statements provide a high-level overview, the IRS demands documentary evidence to back up every deduction you claim. Collecting and organizing all your receipts and invoices throughout the year is a non-negotiable part of any audit-proof small business tax preparation checklist. These documents serve as the proof needed to substantiate your expenses, transforming them from mere numbers on a spreadsheet into legitimate, defensible tax deductions.
Failing to maintain this proof can result in disallowed deductions, leading to a higher tax bill, penalties, and interest if you are ever audited. An organized system for your source documents ensures that every claimed expense is easily verifiable, providing peace of mind and a solid defense against IRS inquiries.
Why This is Foundational Proof
Think of your tax return as a legal argument where you claim certain business expenses reduced your taxable income. Your receipts and invoices are the evidence you present to prove your case. A marketing agency, for example, must keep the invoices from freelance copywriters and receipts for software subscriptions to deduct those costs. Similarly, a construction company needs to retain receipts for materials, equipment rentals, and subcontractor payments to validate its cost of goods sold.
Actionable Tips for Implementation
- Go Digital Immediately: Use a receipt-scanning app like Expensify, Dext, or Shoeboxed to capture a digital image of every receipt the moment you get it. This prevents lost or faded paper records and allows for easy categorization.
- Organize by Category and Date: Whether you store them digitally or physically, organize your documents by expense category (e.g., "Marketing," "Office Supplies," "Travel") and then chronologically. This aligns with your accounting software and makes retrieval effortless.
- Use Bank Statements as a Backup: While not a substitute for an itemized receipt, a credit card or bank statement can serve as secondary proof of a transaction, especially when combined with other documentation.
- Adhere to IRS Retention Rules: The IRS generally requires you to keep records for three years from the date you filed your original return. However, keeping them for at least seven years is a safer best practice to cover various circumstances. For more guidance on record-keeping, learn how Allied Tax Advisors can streamline your bookkeeping.
10. Report Estimated Tax Credits and Tax Planning Adjustments
Beyond standard deductions, tax credits and strategic planning adjustments represent a powerful way to directly reduce your tax liability. Unlike deductions, which lower your taxable income, credits reduce your final tax bill dollar-for-dollar. This crucial step in your small business tax preparation checklist involves identifying, documenting, and claiming all available credits and making any necessary year-end financial moves to optimize your tax position.
Ignoring this step is like leaving money on the table. Proactively planning for and claiming these credits can significantly impact your bottom line, freeing up capital for reinvestment, debt reduction, or operational growth. A thorough review ensures you leverage every tax-saving opportunity the law provides.
Why This is a Critical Step
Tax credits are essentially government incentives designed to encourage specific business activities, such as hiring certain employees, investing in research, or providing employee benefits. For example, a small tech startup can claim the Research and Development (R&D) Credit for expenses related to developing new software, potentially saving tens of thousands of dollars. Similarly, a local retailer that starts offering health insurance to its employees might qualify for the Small Business Health Care Tax Credit, directly offsetting the cost of coverage.
Actionable Tips for Implementation
- Work with a Tax Professional: The landscape of tax credits is complex and constantly changing. A qualified professional can identify industry-specific and general business credits you might overlook, ensuring you meet all eligibility requirements.
- Maintain Meticulous Records: To claim a credit, you must have detailed proof. If pursuing the R&D credit, keep records of employee hours, supply costs, and contractor payments related to development. For the Work Opportunity Tax Credit (WOTC), maintain documentation for qualifying new hires.
- Review Credits Annually: Don't assume the credits you claimed last year are still available or that new ones haven't been introduced. Make it an annual practice to review federal, state, and local credits.
- Incorporate Long-Term Planning: For small business owners focusing on long-term financial health, strategic tax planning is essential. Exploring various alternative tax strategies for retirement can provide significant advantages and align your business goals with personal wealth-building.
Small Business Tax Prep: 10-Item Checklist Comparison
| Task | Implementation Complexity 🔄 | Resource Requirements 💡 | Expected Outcomes 📊 | Ideal Use Cases ⭐ | Key Advantages ⚡ |
|---|---|---|---|---|---|
| Organize Financial Records and Bank Statements | Moderate — time-consuming for many accounts | Accounting software, cloud storage, dedicated folders | Accurate income reporting; faster filing; audit readiness | All businesses, freelancers, high-transaction operations | Reduces audit risk; speeds tax prep; identifies deductions |
| Calculate Business Income and Revenue | Moderate–High — multiple streams & recognition rules | Bookkeeping system, invoices, 1099s, revenue reports | Correct tax liability; clear profitability metrics | E‑commerce, service firms, consultants | Supports financing; reveals seasonal trends |
| Compile and Categorize Business Expenses | Moderate — requires meticulous categorization | Receipt capture apps, chart of accounts, policies | Maximized deductions; improved cash-flow visibility | Small businesses, freelancers, home-based businesses | Lowers taxable income; simplifies budgeting |
| Document Home Office Deduction | Moderate–High — regular method can be complex | Square‑footage measurements, expense records, photos | Potential significant deduction; depreciation considerations | Remote workers, home‑based businesses with dedicated space | Substantial deduction potential; simplified method option |
| Gather Vehicle and Mileage Records | Moderate — requires contemporaneous logs | Mileage tracking apps, logbook, receipts for actual method | Vehicle-related deductions; better cost tracking | Realtors, delivery, service businesses | Standard method simplicity; actual method captures full costs |
| Review and Organize 1099 Forms | Low–Moderate — reconciliation often needed | Client communications, record reconciliation tools | Prevents IRS mismatches; ensures income accuracy | Freelancers, contractors, investors | Avoids matching discrepancies; streamlines filing |
| Calculate Quarterly Estimated Tax Payments | Moderate — requires periodic estimation & discipline | Form 1040‑ES, EFTPS access, cash reserves | Avoids penalties; smoother cash-flow management | Self‑employed and business owners with tax liability | Prevents large year‑end bills; payments adjustable |
| Verify Retirement Plan Contributions | Moderate — plan rules and deadlines apply | Plan documents, custodian statements, advisor support | Reduced taxable income; retirement savings growth | Small business owners, self‑employed individuals | Significant tax deductions; tax‑deferred growth |
| Collect Receipts and Invoices Documentation | Moderate — ongoing discipline required | Scanning apps, physical filing system, backup records | Audit defense; substantiated deduction claims | Expense‑heavy businesses; agencies, contractors | Improves accuracy; supports audit substantiation |
| Report Estimated Tax Credits & Planning Adjustments | High — eligibility and calculations complex | Tax professional, detailed activity records, research | Dollar‑for‑dollar tax reductions; possible refunds | Startups, R&D firms, employers offering benefits | Direct tax liability reduction; some refundable credits |
Beyond the Checklist: Your Next Steps to Tax Success
Navigating the extensive small business tax preparation checklist you've just reviewed is a monumental step toward financial clarity and compliance. You’ve journeyed through the critical distinctions between entity types, from the straightforward needs of a sole proprietorship to the intricate requirements of an S Corp or C Corp. You now have a clear roadmap for organizing income records, categorizing every potential deduction, and managing complex areas like payroll, asset depreciation, and state-specific filings.
This guide was designed to transform an overwhelming process into a series of manageable, actionable steps. By understanding the importance of meticulous record-keeping for expenses like vehicle mileage and the home office deduction, you are no longer just reacting to tax season; you are proactively shaping your financial destiny. You've seen how tools like QuickBooks and IRIS can streamline bookkeeping and how crucial it is to stay ahead of deadlines for estimated tax payments and 1099 filings.
However, the true value of this checklist lies not just in completing it, but in understanding what it represents: a foundation. Tax preparation is not a once-a-year event but a continuous cycle of strategic financial management.
From Compliance to Strategic Advantage
The ultimate goal of mastering your business taxes extends far beyond simply avoiding penalties. It's about transforming a mandatory obligation into a strategic advantage that fuels your business growth.
- Maximizing Deductions: Diligently tracking every expense, from office supplies to software subscriptions, directly increases your net profit. The difference between a forgotten receipt and a documented deduction is real money that stays in your business.
- Informed Decision-Making: When your financial records are clean and organized for tax purposes, they also provide invaluable insights. You can accurately assess profitability, manage cash flow more effectively, and make data-driven decisions about expansion, hiring, or investment.
- Capitalizing on Credits: Tax credits are a dollar-for-dollar reduction of your tax liability. By identifying and claiming credits related to retirement plan contributions, energy efficiency, or research and development, you are directly investing back into your company's future.
- Building a Defensible Position: An organized, well-documented tax file is your best defense in the unlikely event of an audit. The peace of mind that comes from knowing your records are audit-ready is invaluable, allowing you to focus on running your business without unnecessary stress.
Think of each item on this small business tax preparation checklist as a building block. By mastering each one, you are constructing a resilient financial framework that supports your business not just during tax season, but all year round.
Turning Knowledge into Action
The journey from understanding to implementation is where many small business owners falter. The complexities of changing tax laws, the nuances between different business structures, and the sheer time commitment can be significant hurdles. The checklist provides the "what," but a professional partner can provide the "how" and the "why."
Key Insight: A completed checklist is a powerful tool, but a professional tax advisor can analyze that information to uncover opportunities for future savings and growth that you might have missed. They can help you structure your business for optimal tax efficiency and plan for major financial events.
Completing this checklist is not the finish line; it is the starting line for a more strategic and empowered approach to your business finances. You now possess the knowledge to ask the right questions, provide the right documentation, and engage with your finances on a deeper level. The next step is to leverage this preparation into a long-term strategy for success, ensuring that every financial move you make is as tax-efficient as possible. This proactive stance is what separates thriving businesses from those that merely survive.
Don't let your hard work stop at the checklist. The experts at Allied Tax Advisors can review your prepared documents to ensure accuracy, maximize your deductions, and develop a forward-looking tax strategy tailored to your unique business goals. Contact Allied Tax Advisors today to transform your tax compliance into a powerful tool for growth.