
Accounting for a contracting business isn't like running the books for a coffee shop or a retail store. It's a different beast entirely, built around the unique rhythm of project-based work. We're talking about job costing, progress billing, and navigating a maze of complex tax rules. Unlike a business with predictable monthly sales, your success hinges on tracking profitability one project at a time. This is what keeps you in the game for the long haul.
Building Your Financial Blueprint
You’d never start a custom home build without a solid blueprint, right? Your business's finances are no different. A strong accounting system is your master plan—the blueprint that guides every decision you make, from bidding on a new job to hiring your next crew member. It’s what ensures you’re actually making money and not just staying busy.
This financial plan is designed to tackle the daily chaos contractors face. You're dealing with cash flow that ebbs and flows with project milestones, expenses that need to be tracked across multiple job sites, and specific rules for paying your team. Getting this foundation right from the very beginning isn't just a good idea; it's non-negotiable for survival and growth.
Choosing Your Business Structure
The first block you’ll lay in this financial foundation is your business entity. This one decision has a ripple effect on everything from your personal liability to how much you pay in taxes.
- Sole Proprietorship: This is the default and simplest setup. The catch? There's no legal separation between you and the business. If something goes wrong on a job, your personal assets are on the line. It's easy to start, but it offers zero protection.
- Limited Liability Company (LLC): This is a game-changer for most contractors. An LLC creates a protective wall between your business and personal life. If the business faces a lawsuit or racks up debt, your home, personal savings, and vehicle are shielded. This is a crucial safeguard in a high-risk industry like construction.
- S Corporation (S-Corp): An S-Corp isn't a business structure itself, but a tax election. It can potentially lower your self-employment tax bill by allowing you to pay yourself a "reasonable salary" while taking any additional profits as distributions, which are taxed at a lower rate.
Choosing an entity is a critical first step. An LLC is often the go-to for contractors because it combines liability protection with operational flexibility. As your business grows, electing S-Corp status can offer significant tax advantages.
Setting Up Separate Finances
Once your business entity is official, your very next move should be to open a dedicated business bank account and credit card. Mixing personal and business finances is one of the most common—and costly—mistakes a contractor can make. It turns bookkeeping into a nightmare, makes it impossible to know if a job was truly profitable, and can even destroy the liability protection your LLC is supposed to provide.
A separate account brings immediate clarity. Every dollar of income and every expense is clearly categorized, making your financial tracking clean and simple. When building out this system, specialized tools like Sage 100 Contractor can offer a powerful, all-in-one solution designed for the complexities you face.
This strict separation is the bedrock of clean records. And if you're using software to manage your books, you'll need a system built for your specific needs. For those getting started, our guide on how to set up QuickBooks is a fantastic resource. A clean, dedicated financial system is the only way to truly understand the health of your business and build a company that lasts.
Know Your Numbers: Job Costing and the Path to Real Profit
Are you busy, or are you profitable? It's a critical question, and the answer isn't always obvious just by looking at a full schedule. For contractors, the single most important accounting practice to answer this is job costing. It’s the difference between having a simple history of your spending and having a powerful roadmap for future growth.
Think of it this way: your overall business accounting is like checking your bank balance at the end of the month. Job costing, on the other hand, is like getting a detailed receipt for every single project. It shows you exactly which jobs are making you money and which ones are secretly costing you. Without it, you’re flying blind.
Setting Up Your Financial Blueprint: The Chart of Accounts
The foundation of good job costing is your Chart of Accounts (CoA). Don't let the name intimidate you; it's just a structured list of all your company's accounts. Think of it as the set of folders you use to organize every dollar that comes in and goes out.
For a contracting business, a generic, off-the-shelf CoA is practically useless. You need one built for project-based work. The key is to separate the direct costs you can pin to a specific job from the indirect overhead of just keeping the lights on.
Your business structure also plays a role here. How you set up your company—whether as a sole proprietor or something more formal—affects how you'll manage these accounts and protect your personal finances from business risks.
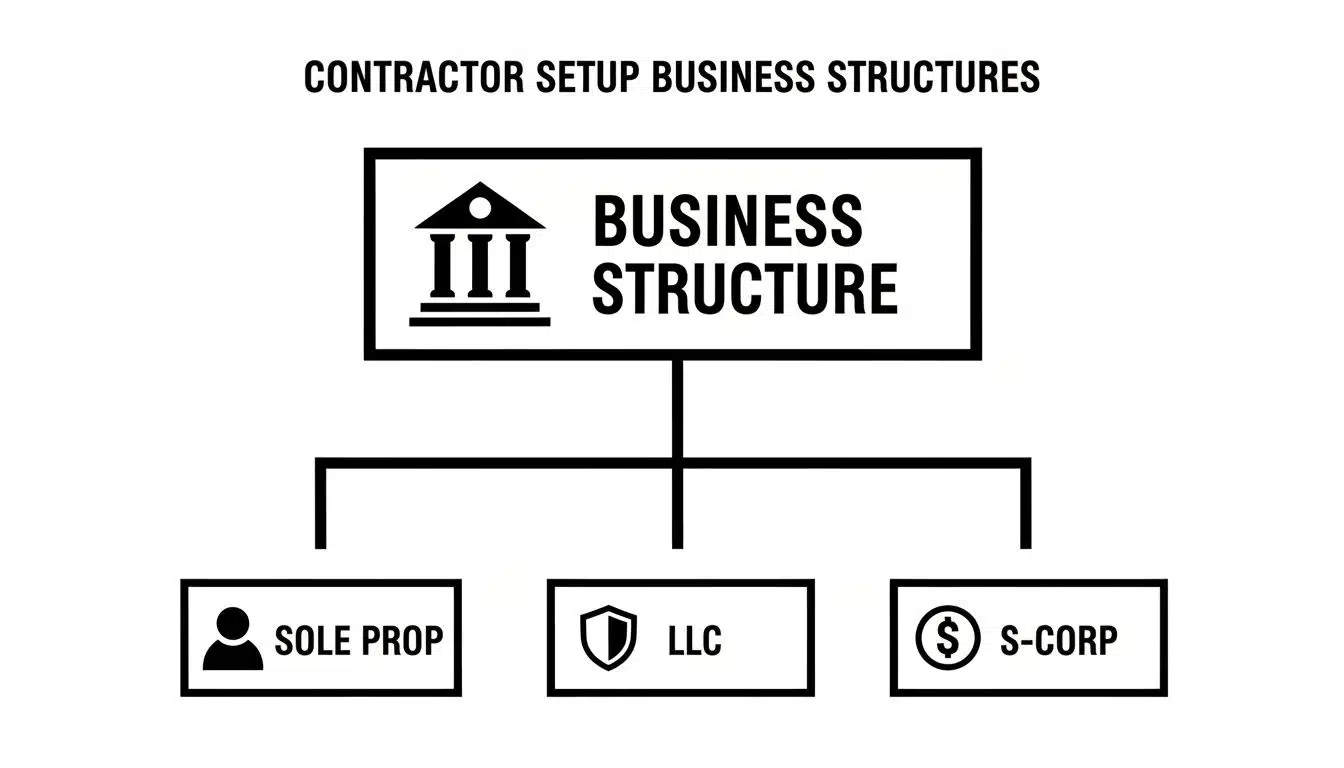
While a Sole Proprietorship is the easiest to start, forming an LLC or an S-Corp is a smart move for most contractors. It creates a legal shield between your business debts and your personal assets, which is essential in this industry.
A well-organized Chart of Accounts is what makes accurate job costing possible in the first place. Here’s a basic table showing what a contractor-specific CoA might look like.
Sample Contractor Chart of Accounts
This table provides a simplified look at how you might categorize your finances. Notice the clear distinction between income, direct project costs (Cost of Goods Sold), and general business expenses (Overhead).
| Account Type | Account Name | Description |
|---|---|---|
| Income | Construction Sales | Total revenue from all completed projects. |
| Cost of Goods Sold | Direct Material Costs | Lumber, drywall, fixtures, paint bought for specific jobs. |
| Cost of Goods Sold | Subcontractor Costs | Invoices from plumbers, electricians, etc. for a job. |
| Cost of Goods Sold | Direct Labor | Wages for your team when working on a specific project. |
| Overhead Expense | Vehicle Expenses | Fuel, maintenance, and insurance for your work truck. |
| Overhead Expense | General Liability Insurance | Premiums for your business insurance policy. |
| Overhead Expense | Software & Subscriptions | Monthly fees for your accounting or project software. |
This structure ensures that every time you buy materials or pay a sub, that cost is logged against the correct project, not just thrown into a vague "Expenses" bucket.
Job Costing in the Real World
Let's see how this works with a practical example. Say you land a $25,000 bathroom remodel. With your CoA set up, you can now track every single cost against this specific project.
- Materials: You spend $6,500 at the supply house for the tile, vanity, tub, and fixtures. You assign this entire purchase directly to the "Bathroom Remodel" job.
- Subcontractors: Your plumber sends an invoice for $3,000, and the electrician bills you $2,200. Both of these payments get logged against the "Bathroom Remodel" job.
- Labor: You have an employee who logs 80 hours on-site. At their loaded rate of $30/hour, that’s $2,400 in labor costs that you allocate directly to the "Bathroom Remodel" job.
By meticulously tracking these costs, you can see your total direct expenses for the project are $14,100. That means you’ve made a gross profit of $10,900 before factoring in your overhead.
This kind of clarity is incredibly powerful. You instantly see your real-time profit margin on that job. Was your materials estimate on point? Did labor run over? This data is pure gold and gives you a massive advantage when you're putting together your next bid.
This process—turning past performance into future profit—is exactly why many contractors now rely on specialized construction estimating software. These platforms can connect directly to your accounting data, helping you build bids based on actual, historical costs. It takes the guesswork out of estimating and ensures your proposals are both competitive and profitable from the start.
Optimizing Invoicing and Cash Flow Management
You can have profit on paper, but that doesn't mean a thing if your bank account is running on fumes. For a contractor, healthy cash flow is the lifeblood of your business. It all comes down to how you handle your invoicing. Think of your business finances like a plumbing system: a smart invoicing strategy keeps cash flowing freely, while sloppy practices create clogs that can bring your entire operation to a standstill.
The name of the game is getting paid on time, every time. This is about more than just firing off a bill when the job’s done. It means picking the right invoicing model for the project, creating invoices that are impossible to misunderstand, and having a system to track every dollar. When you get cash flow management right, you’ll always have the funds to buy materials, make payroll, and grow your business.
Choosing Your Invoicing Method
When it comes to invoicing, one size definitely does not fit all. The method you choose should match the job's timeline and complexity. In the contracting world, two main approaches are king, and each has a huge impact on your cash flow.
Time and Materials (T&M): This is the most straightforward route. You bill clients for the actual hours your crew works and the real cost of the materials you use. It's a perfect fit for smaller jobs or projects where the scope might shift, because it ensures you get paid for every bit of work you do.
Progress Billing: For bigger, multi-month projects, progress billing isn't just nice to have—it's essential. You invoice the client at specific, pre-agreed-upon milestones. Think foundation complete, framing up, or passing a final inspection. This approach injects cash into your business throughout the job, so you aren't forced to finance the entire project yourself.
Opting for progress billing basically turns one massive project into a series of smaller, manageable payments. This makes your income far more predictable and is a cornerstone of solid contractor accounting.
Creating Invoices That Get Paid
Your invoice is more than a bill; it’s a professional document that speaks to the quality of your work. A clear, detailed invoice cuts down on confusion and disputes, which dramatically speeds up how quickly you get paid.
An invoice should tell the complete story of the work you performed. Leave no room for questions. The easier you make it for a client to understand what they’re paying for, the faster that money will hit your account.
Your invoice needs to be airtight. Vague line items like "Labor and Materials" are just asking for payment delays and follow-up questions. Instead, give them an itemized breakdown that includes quantities, rates, and clear descriptions of the work completed for that billing cycle.
Every invoice you send should include:
- Your Business Information: Full name, address, phone, and email.
- Client Information: The full name and address of the person or company you're billing.
- An Invoice Number: A unique number is critical for tracking and reference.
- Clear Payment Terms: State exactly when payment is due (e.g., "Due upon receipt," "Net 15," "Net 30"). Don't leave it open to interpretation.
- Accepted Payment Methods: Tell them how they can pay you (check, ACH transfer, credit card).
Finally, have a polite but firm process for following up on overdue payments. A quick email reminder a day or two after the due date often does the trick. A well-defined invoicing and collections system is absolutely fundamental to keeping your business's financial pulse strong and steady.
W-2 Employees vs. 1099 Subcontractors: Getting It Right
As your business grows, you're going to need more help. It's a great problem to have. But how you bring on that extra set of hands carries serious financial and legal weight. Misclassifying an employee as a subcontractor is one of the most punishing mistakes a contractor can make—one that can bring on a world of hurt from the IRS.
The difference between a W-2 employee and a 1099 independent contractor isn't just a matter of preference. It's a determination based on strict IRS rules. Getting this wrong can put your entire business at risk.
The IRS Control Test: Who's Really in Charge?
So, where's the line? The IRS uses what's known as a "control test" to figure out a worker's status. Forget about job titles or what your contract says; what matters is the day-to-day reality of your relationship. The more control you have over what work is done and how it gets done, the more likely the IRS will see that person as an employee.
Think of it this way. The IRS looks at three main areas to see who holds the power:
- Behavioral Control: Do you tell the worker how to do their job? If you're providing specific instructions, training them on your methods, or dictating the sequence of their tasks, that's a sign of an employee. A true subcontractor is an expert you hire to achieve a result; they decide how to get there.
- Financial Control: Do you control the money side of things? If you're paying them a regular wage, reimbursing their expenses, or providing the expensive tools and equipment for the job, they look a lot like an employee. A subcontractor brings their own tools, covers their own costs, and typically gets paid by the project, not by the hour.
- Relationship of the Parties: What does the arrangement look like? If the person works exclusively for you, you provide benefits like paid time off, and there’s an expectation the job will continue indefinitely, that points toward an employee-employer relationship. Subcontractors work on a defined project basis and are free to take on jobs with other companies.
Misclassifying a worker is a huge red flag for the IRS. The penalties are severe and can include all the back Social Security and Medicare taxes you should have withheld, plus unemployment taxes and steep fines. Payroll taxes are a primary source of federal income, and the government does not take non-payment lightly.
Your Paperwork and Payroll Duties: W-2 vs. 1099
Once you've determined a worker's status, your accounting responsibilities go in two completely different directions. Each path has its own forms, payment procedures, and tax-filing requirements.
For a W-2 Employee, you are responsible for:
- Having them fill out a Form W-4 so you know how much tax to withhold.
- Running payroll on a regular schedule.
- Withholding federal and state income taxes, plus their share of Social Security and Medicare (FICA).
- Paying the employer's matching share of FICA taxes, as well as federal and state unemployment taxes (FUTA/SUTA).
- Sending them a Form W-2 by January 31 each year that details their total earnings and taxes paid.
For a 1099 Subcontractor, your job is simpler:
- You must collect a completed Form W-9 from them before you cut their first check. This form gives you their correct legal name and Taxpayer ID Number (TIN).
- You pay them their full invoice amount. No tax withholding is necessary.
- If you paid them $600 or more in the calendar year, you must send them a Form 1099-NEC by January 31.
Getting that Form W-9 is non-negotiable. It's the key to staying compliant. As you can discover in our post about the statutory employee definition, these rules can get tricky. By creating a firm process for classifying every new worker and handling the paperwork correctly from day one, you can protect your business and grow your team with confidence.
Maximizing Your Contractor Tax Deductions
What you earn is only half the story. The real measure of a successful year for any contractor is how much of that hard-earned money you actually get to keep.
This is where smart accounting becomes your best friend. It’s not just about counting the money coming in; it’s about strategically tracking every single dollar that goes out. Waiting until April to think about your expenses is a surefire way to miss out on thousands in savings. A deduction is worthless without a record to back it up, making good bookkeeping your most powerful profit-boosting tool.
Beyond the Obvious Job Costs
Everyone knows to deduct materials and subcontractor payments. Those are the easy ones. The real money is often found in the dozens of other operational costs you incur just to keep the lights on and the business running.
Many contractors leave a surprising amount of cash on the table by simply overlooking these day-to-day expenses. Let’s dig into some of the most valuable—and most frequently missed—deductions you should be claiming.
Vehicle Expenses: A Major Write-Off
That work truck isn't just a ride; it's a rolling office and a critical piece of your equipment. The IRS offers two distinct methods for deducting its use, and your choice can have a big impact on your tax bill.
- Standard Mileage Rate: This is the simplest route. You just track your business miles and multiply the total by the IRS-set rate (which was 67 cents per mile for 2024). You can still deduct parking fees and tolls separately.
- Actual Expense Method: Here, you add up what you actually spent on the vehicle—gas, insurance, repairs, oil changes, tires, registration, and even depreciation. You then deduct the business-use percentage of that total cost.
So, which one is better? It depends. If you have an older, paid-off truck and drive a ton of miles, the standard rate is often a clear winner. But for a newer vehicle with a loan payment and higher maintenance costs, the actual expense method might provide a much larger deduction.
Whichever method you use, keeping a detailed mileage log is non-negotiable. An app on your phone or a simple notebook in the glove compartment works perfectly. Just be sure to log the date, mileage, and the business purpose of every trip.
Often-Overlooked Contractor Deductions
From your cell phone bill to the boots on your feet, small expenses add up fast. The key to capturing them all is an organized system for tracking everything throughout the year.
The following table highlights some of the most common tax write-offs for contractors. Use it as a checklist to ensure you’re not missing anything.
Common Contractor Tax Deductions
| Expense Category | Examples | Record-Keeping Tip |
|---|---|---|
| Tools & Equipment | Hand tools, power tools, safety gear (boots, gloves, glasses), ladders, generators. | For small tools, keep the receipts. For large purchases (over $2,500), track the date and cost for depreciation. |
| Insurance Premiums | General liability, workers' comp, commercial auto policies, builder's risk insurance. | Keep a digital copy of your policy declarations page, which shows your annual premium cost. |
| Home Office | A portion of rent/mortgage interest, utilities, property taxes, and home insurance. | Use a clear method (simplified or actual) and keep records showing the space is used exclusively for business. |
| Professional Services | Fees paid to your CPA, bookkeeper, lawyer, or business consultants. | Save all invoices and payment confirmations from these professionals. They are 100% deductible. |
| Software & Subscriptions | QuickBooks, IRIS, project management apps, trade journals, estimating software. | Most services email monthly or annual receipts. Create a dedicated email folder to store them all. |
| Continuing Education | Costs for licensing renewal, certification courses, trade school classes, or industry seminars. | Keep receipts for course fees and any related travel expenses (if you travel overnight for a conference). |
This list just scratches the surface. Diligent tracking is what separates contractors who pay their fair share from those who overpay.
For a more exhaustive breakdown, take a look at our complete 1099 tax deductions list to make sure every possible write-off is on your radar. A proactive approach to documenting expenses isn't just about compliance; it's a fundamental part of smart accounting for contractors.
When to Hire a CPA for Your Contracting Business
Let's be real: you got into this business to build things, not to become a part-time accountant. While modern software makes managing your own books easier than ever, knowing your limits is one of the smartest things you can do. Calling in a professional isn't a sign of failure—it's a strategic move to protect your growing business.
First, it’s helpful to know who does what. A bookkeeper is your day-to-day financial scorekeeper. They’re in the trenches with you, recording transactions, categorizing expenses, and making sure the numbers line up. A Certified Public Accountant (CPA), on the other hand, is your financial strategist. They look at the big picture: tax planning, business structure, and representing you if the IRS comes knocking.
Signs It's Time for Expert Help
When you're just starting out, you can probably wear all the hats yourself. But as your operation gets bigger, certain things will happen that should be a clear signal to bring in a CPA. Ignoring these can lead to some seriously expensive mistakes and sleepless nights.
Look out for these clear indicators:
- Your Business Gets More Complicated: You're not just a one-person show anymore. You're hiring your first W-2 employees, stocking significant inventory, or juggling multiple large jobs at once.
- You're Thinking About an S-Corp: If you're currently an LLC and hear about saving on self-employment taxes by electing S-Corp status, pump the brakes. This is a major decision that needs a pro to run the numbers and see if it actually makes sense for you.
- You Get a Letter from the IRS: This is the big one. Never, ever try to handle an audit or official notice from the IRS on your own. A CPA knows the process, speaks their language, and can represent you. It's a non-negotiable.
- You're Blindsided by Your Tax Bill: If every April feels like a nasty surprise, you're being reactive, not proactive. A CPA will work with you all year long to create a tax strategy, so you know what's coming and can legally minimize what you owe.
Think of a CPA as an investment that pays for itself, not just another bill. The right advice can easily save you thousands in taxes and penalties, making their fee look small in comparison. The peace of mind alone is worth it.
The Value of a Strategic Partner
Ultimately, it all boils down to a simple question: what is your time really worth? Every hour you spend hunched over a spreadsheet trying to figure out tax code is an hour you’re not on-site, bidding a new project, or leading your team.
A good CPA does so much more than just file your taxes once a year. They become a partner who truly gets the ins and outs of the construction world. They can advise you on whether that big equipment purchase makes financial sense, help you prepare the statements needed to get a business loan, and give you the data to make smart decisions.
Hiring a CPA is about recognizing that your highest value is as a great contractor. Let an expert handle the complex financial stuff so you can get back to doing what you do best: building your business.
Common Questions We Hear
Even after getting the big picture right, a few specific questions always seem to pop up. Let's dig into some of the most common ones we hear from contractors trying to get their books in order.
What’s the Best Accounting Software for a Small Contractor?
For most contractors, the go-to answer is QuickBooks Online. It's really become the industry standard for a reason. Its "Projects" feature is fantastic for job costing, letting you see exactly how profitable each project is. Plus, it connects with a huge library of other apps built specifically for trades and construction.
But it’s not the only game in town. If your business is on the simpler side, other tools can be a great fit.
- FreshBooks is a solid choice for service-focused contractors who just want dead-simple invoicing and time tracking.
- Wave is perfect if you're just starting out and need to watch every penny, offering free accounting and invoicing to get you off the ground.
Should I Use the Cash or Accrual Method?
This is a big one. Most small contractors start with the cash basis method because it’s so straightforward. You record income when the check clears and expenses when you actually pay the bill. It’s easy because it lines up perfectly with what you see in your bank account.
However, the accrual basis method gives you a much truer sense of your company's financial health. With accrual, you record income when you earn it (the moment you send the invoice) and expenses when you incur them (the moment a supplier gives you a bill). This is absolutely critical for understanding your profitability on long projects.
While cash basis is simpler day-to-day, accrual accounting shows you the real story. As of 2024, the IRS even requires businesses with over $29 million in average annual revenue to use the accrual method, so it's a good concept to understand as you grow.
What Do I Do with Leftover Materials?
This is a classic job costing problem. When you buy a skid of lumber or a case of fixtures for a specific project, that’s a direct cost (Cost of Goods Sold) for that job. Simple enough.
But what happens when the job is done and you have a bunch of materials left over? Don't just let them sit in the shop unaccounted for. You need to move their value from that job's expense account to an "Inventory Asset" account on your balance sheet. Then, when you use those materials on the next job, you expense them to that new project. This little step is key to making sure your profit-per-job numbers are actually accurate.
Getting these details right is what separates a good-enough system from a great one. The team at Allied Tax Advisors lives and breathes this stuff, and we can help you choose the right software, decide on an accounting method, and build a workflow that tracks every dollar. Contact us today to simplify your contractor accounting.