
Only the interest and certain points portions of a mortgage payment are ever tax deductible, and only when you itemize on Schedule A. The principal and most insurance components aren't deductible.
You may be looking at a January mortgage statement right now, seeing one large payment and assuming the entire amount should help reduce your taxable income. It won't. A mortgage payment is a bundle of separate costs, and the tax treatment depends on which cost you're looking at, how the loan was used, when the debt began, and whether your itemized deductions exceed the standard deduction.
The practical answer is straightforward: don't enter your total monthly payment as a deduction. Pull apart the statement, identify the qualified interest, check the applicable debt limit, and then compare your potential Schedule A deductions with the standard deduction for your filing status.
Table of Contents
- What a Mortgage Payment Actually Includes
- The Mortgage Interest Deduction and the $750,000 Cap
- How the Rules Differ by Property Type
- Itemizing Versus Taking the Standard Deduction
- Forms, Records, and What About Points and PMI
- Common Mistakes That Trigger IRS Scrutiny
- Two Worked Examples for Real Filers
- When to Bring in a Tax Professional
What a Mortgage Payment Actually Includes
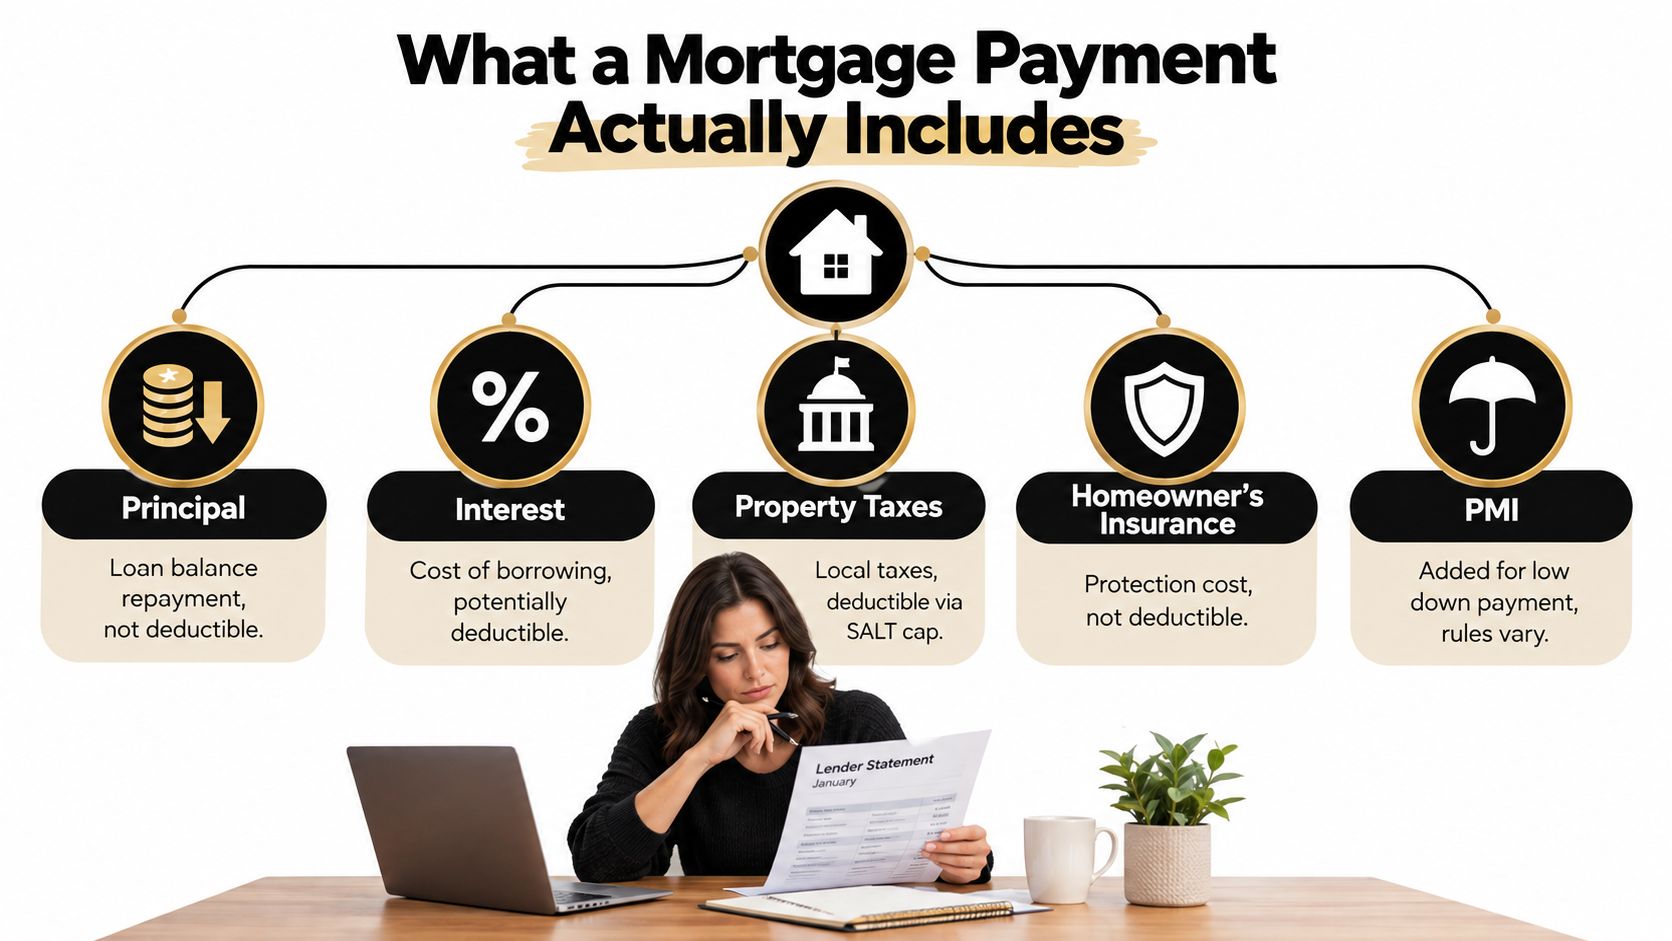
A homeowner reviewing a lender statement will usually see several buckets blended into one monthly amount. The lender may collect principal and interest for the loan, while placing property taxes and homeowners insurance into an escrow account. If you made a smaller down payment, private mortgage insurance, or PMI, may appear as another charge.
Read the statement by category
Principal reduces what you owe. It builds equity, but it isn't a current federal income-tax deduction.
Interest is the lender's charge for allowing you to use borrowed money. Qualified mortgage interest may be deductible on Schedule A, but only if you itemize and satisfy the home, debt-use, and dollar-limit rules.
Property taxes are separate from mortgage interest. They may belong in the state and local tax, or SALT, category. For a broader explanation of the property-tax rules, review this guide to deducting property taxes.
Homeowners insurance protects the property against covered risks. Insurance premiums on a personal residence generally aren't mortgage-interest deductions, even when the lender collects them with your payment.
PMI is insurance protecting the lender when the borrower has limited equity. It has had separate, temporary federal tax treatment, so don't assume the amount is automatically deductible.
Why your interest changes over time
An amortizing loan applies each payment between interest and principal. Early payments generally contain a larger interest share because the outstanding balance is larger. As the balance declines, more of each payment goes toward principal and less goes toward interest.
That means your potential mortgage-interest deduction usually changes over the life of the loan. Your lender's annual Form 1098, not your rough multiplication of the monthly payment, is the figure you should start with.
Points, qualified closing costs, PMI, and interest from a home-equity line of credit require separate analysis. Treat them as distinct tax questions instead of adding every escrow or loan-related charge together.
The Mortgage Interest Deduction and the $750,000 Cap
The cap that catches homeowners most often is the difference between $750,000 and $1,000,000 of qualified mortgage debt. Under the IRS rules, debt incurred on or before December 15, 2017, generally receives the older limit of $1,000,000, or $500,000 for married taxpayers filing separately. Debt incurred after that date generally uses the $750,000 limit, or $375,000 for married taxpayers filing separately. See IRS Publication 936 for the governing mortgage-interest rules and transition details.
| Loan Date | Cap, married filing jointly | Cap, married filing separately | Refinancing Rule |
|---|---|---|---|
| On or before December 15, 2017 | $1,000,000 | $500,000 | Older treatment can continue for qualifying debt |
| After December 15, 2017 | $750,000 | $375,000 | New debt generally uses the lower cap |
The cap applies to qualified acquisition debt secured by a qualifying home. If a post-breakpoint purchase loan is $500,000, the debt falls below the cap, so the entire qualified interest amount can potentially be considered, subject to itemizing and the other rules. If the loan is $900,000, only the interest allocable to the permitted debt amount is potentially deductible. A simple allocation would use $750,000 divided by $900,000, or five-sixths of the qualified interest, but your tax software or preparer should handle the exact calculation.
A pre-breakpoint loan of $1.2 million doesn't receive a deduction on the entire balance. The older rule generally limits the calculation to the first $1 million of qualified debt. A binding contract signed before December 15, 2017, with a qualifying closing before April 1, 2018, may fall under a narrow transition rule described by the IRS.
Practical rule: Preserve the original closing documents. Loan dates, refinancing history, and debt purpose matter more than the balance shown on this year's statement.
The cap is based on combined qualified debt tied to your main home and second home, not a separate fresh limit for each property. Don't assume buying a second residence creates another unrestricted bucket. The IRS and Congress describe these rules as applying for tax years 2018 through 2025, so 2026 planning requires checking whether Congress changes the law or allows the scheduled framework to change. For debt-allocation strategies, see this guide to maximizing your mortgage-interest deduction.
How the Rules Differ by Property Type
The same loan can produce a different tax result depending on the property and the use of the borrowed funds. A personal residence, a rental, and a HELOC aren't interchangeable because each involves real estate.
| Property Type | Where Deducted | Cap Applies? | Key Rule |
|---|---|---|---|
| Primary residence | Schedule A | Generally, for qualified personal acquisition debt | Interest must relate to buying, building, or substantially improving the home |
| Second home | Schedule A | Generally, combined with qualifying debt on the primary residence | Personal-use second-home interest follows the home-mortgage rules |
| Rental property | Schedule E | Different regime from personal Schedule A debt | Interest is generally a rental expense connected with producing rental income |
| HELOC | Schedule A or applicable rental schedule | Depends on use and the secured property | Interest generally requires proceeds to buy, build, or substantially improve the securing home |
A primary residence and a qualifying second home generally use the personal mortgage-interest rules. Keep the combined debt picture in view. A second home isn't a way to separate debt from the overall limitation.
Rental property follows a different reporting path. Mortgage interest connected with a rental is generally reported as a rental expense on Schedule E, where it is considered alongside rental income and other property expenses. It isn't added to personal itemized deductions. Passive-activity rules can limit when a rental loss becomes usable, even when the expense itself is properly calculated.
HELOCs require tracing
A HELOC is deductible based on what you did with the money, not merely on the fact that your home secures the line. Proceeds used to buy, build, or substantially improve that home may qualify. Proceeds used for a vehicle, vacations, credit-card payoff, or unrelated personal spending generally create personal interest that isn't deductible.
Keep invoices, bank transfers, and a written tracing schedule. If you mixed home-improvement proceeds with personal spending in one account, reconstruct the flow before filing. Houseboats and recreational vehicles don't qualify as homes for these mortgage-interest rules simply because they have sleeping or living space.
Itemizing Versus Taking the Standard Deduction
Mortgage interest only helps you federally when you itemize. That makes the core question less about whether interest appears on Form 1098 and more about whether your total Schedule A deductions beat the standard deduction available to you.
For 2025, the standard deduction is $15,000 for single filers, $30,000 for married couples filing jointly, and $22,500 for heads of household. Those figures come from the filing-year rules and should be verified against the instructions for your return. Married taxpayers filing separately have a $7,500 standard deduction, subject to the applicable filing rules.
| Filing Status | 2025 Standard Deduction | Itemized Bucket Needed | Likely Decision |
|---|---|---|---|
| Single | $15,000 | Mortgage interest, SALT, gifts, and allowable medical expenses above the threshold must exceed it | Use the larger total |
| Married filing jointly | $30,000 | The combined Schedule A total must exceed it | Standard deduction is often competitive |
| Head of household | $22,500 | Total itemized deductions must exceed it | Compare both calculations |
| Married filing separately | $7,500 | A smaller threshold can make itemizing more relevant | Coordinate with the spouse's election |
Your Schedule A total may include qualified mortgage interest, eligible state and local taxes subject to the SALT limitation, charitable contributions, and qualifying medical expenses above the applicable percentage of adjusted gross income. Don't assume mortgage interest alone gets you over the line.
Use a two-column test
First, total the itemized categories. Second, compare that total with your standard deduction. Choose the larger permitted deduction, not the method that feels more connected to homeownership.
The decision is made year by year. Taking the standard deduction this year doesn't permanently waive mortgage interest, and itemizing this year doesn't force you to itemize in every later year. Keep your Form 1098 and tax records either way, because a refinancing, large charitable gift, property-tax change, or income shift can change the comparison.
Forms, Records, and What About Points and PMI
Your lender's Form 1098 is the starting document. Box 1 generally shows mortgage interest received by the lender. Box 5 may show mortgage insurance premiums when the lender reports them, and points may appear in Box 6. Seller-paid points can be reported separately, so compare the form with your closing documents instead of assuming the lender captured every detail.
Follow the paper trail
The reporting flow is simple in concept:
- Start with Form 1098. Confirm the lender, property, loan period, and interest amount.
- Separate interest from escrow. Escrow deposits for future taxes or insurance aren't the same as interest paid to the lender.
- Review points. Points paid to obtain the loan may be deductible immediately when they satisfy the applicable requirements. Otherwise, they generally must be spread over the loan term.
- Transfer only eligible amounts. Schedule A carries the personal itemized deduction. Rental-related amounts generally belong on Schedule E.

PMI and FHA mortgage insurance, or MIP, have separate rules and haven't been permanently available as a deduction in every filing year. The temporary provision covered 2018 through 2021, and the deduction is currently inactive. For homeowners who no longer need the coverage, this resource explains how to cancel private mortgage insurance. For the tax treatment itself, see this guide to mortgage insurance premiums.
Keep records that explain the calculation
Retain the Closing Disclosure, or the older HUD-1 for earlier transactions, your Forms 1098, and the points amortization schedule. Keep refinance documents and a debt-tracing log for HELOC proceeds. If your allocation is unusual, ask a tax professional whether Form 8275 or another disclosure is appropriate.
A landlord or self-employed property owner should not force rental interest onto Schedule A. Maintain property-level records so the interest, insurance, taxes, repairs, and depreciation can be reported with the rental activity rather than blended into personal deductions.
Common Mistakes That Trigger IRS Scrutiny
Most mortgage-deduction errors come from treating a payment as one number. The IRS receives lender reporting, and mismatches become difficult to explain when the return claims more than the documents and debt history support.
The most expensive mistakes are predictable:
- Mixing HELOC proceeds: If one draw paid for a kitchen renovation and another paid personal bills, don't deduct all the interest. Trace each draw and allocate interest by use.
- Losing the acquisition-debt trail: Keep the purchase agreement, closing statement, invoices, and bank records that show how borrowed funds bought, built, or substantially improved the home.
- Using the wrong cap: A loan that appears old because the property is old may have been refinanced after the relevant breakpoint. Review the refinance documents before claiming the older limit.
- Putting rental interest on Schedule A: Move interest connected with rental operations to Schedule E. Personal itemizing and rental expense reporting are separate paths.
- Double-counting points: Don't claim points as a current deduction if the same amount has already been included in another interest figure. Use the amortization schedule when immediate deduction rules don't apply.
- Treating escrow as interest: Escrow deposits for property taxes and insurance aren't mortgage interest. Use the actual tax and insurance records for their respective categories.
- Claiming inactive PMI: Check the law for the filing year before entering mortgage insurance premiums. A prior-year tax treatment doesn't automatically continue.
If you already filed incorrectly, don't repeat the error next year. Correct the return with Form 1040-X when appropriate, prepare a written debt-allocation log, or move rental figures to Schedule E before filing. An IRS notice deserves a timely, document-supported response, not a guess based on the monthly payment total.
Two Worked Examples for Real Filers
The cleanest way to understand the rule is to follow the money from the lender statement to the return.
Example one, a San Diego homeowner
A married couple has a $480,000 loan on their primary residence. Their monthly principal-and-interest payment is $1,200, and the January statement shows $720 of interest. For this illustration, assume the interest amount remains $720 each month, producing annual mortgage interest of $8,640.
They also paid $1,800 of property taxes and $14,000 of state income tax. Their itemized total from these amounts is $24,440, not $22,440, because $8,640 plus $1,800 plus $14,000 equals $24,440. Even before considering other Schedule A categories, that total is below the $30,000 standard deduction for married filing jointly in 2025.
| Item | Example 1, Primary Residence | Example 2, Landlord |
|---|---|---|
| Interest treatment | $8,640 considered on Schedule A | Rental interest considered on Schedule E |
| Property tax | $1,800 personal tax category | Rental property expense |
| Insurance | Not a personal interest deduction | Rental expense when properly connected |
| Depreciation | Not applicable to personal residence | $4,800 rental expense |
| Personal standard deduction | $30,000 for 2025 joint return | Depends on landlord's filing status |
| Practical result | Standard deduction wins on listed amounts | Rental activity calculation controls |
The couple should compare the complete Schedule A total, including any eligible charitable or medical deductions, but the listed mortgage-related amounts alone don't justify itemizing. Their tax delta from choosing the standard deduction instead of the listed $24,440 itemized amount is $5,560 of additional deduction, before considering other items.
Example two, a rental owner
A landlord owns a rental with a $425,000 loan and a $380,000 outstanding balance. The stated interest rate is 7%, and the landlord also has $6,200 of property tax, $2,400 of insurance, and $4,800 of depreciation. Interest is calculated from the actual lender records, not by applying the rate mechanically to the balance, because amortization and payment timing affect the amount paid during the year.
The landlord reports qualifying mortgage interest, property tax, insurance, and depreciation with the rental activity on Schedule E. Those expenses reduce rental income before the landlord decides whether to take the standard deduction personally. If the rental produces a loss, passive-activity rules may restrict the immediate use of that loss.
The tax difference isn't measured by subtracting the rental expenses from personal Schedule A deductions. The homeowner compares personal itemizing with the standard deduction, while the landlord first calculates the rental result and then applies the passive-activity rules.
When to Bring in a Tax Professional
A self-filer can usually handle a straightforward return with one W-2 job, one personal home, no rental, no HELOC, and a clean Form 1098. The key is to enter the qualified interest, not the total payment, and run both the itemized and standard-deduction calculations.
Bring in a CPA or Enrolled Agent when your facts stop being simple:
- Rental property: Schedule E reporting, depreciation, and passive-activity limits require property-level accounting.
- HELOC proceeds: Mixed personal and home-improvement uses demand a tracing calculation.
- Older mortgage debt: A loan incurred on or before December 15, 2017, or a later refinance may require reviewing the grandfathered treatment.
- Home office or business use: Personal and business portions may follow different schedules.
- Multiple states or AMT exposure: State filing and alternative-minimum-tax issues can change the result.
- Unusual points or closing costs: Immediate deductions and amortization must be separated.
- IRS correspondence: A notice should be answered from the documents, not from memory.
The IRS describes the Tax Cuts and Jobs Act mortgage rules as applying for tax years 2018 through 2025, so the treatment for 2026 should be reviewed rather than assumed. The possible change in the debt cap and standard-deduction framework makes a targeted planning appointment worthwhile for homeowners refinancing, buying a second home, or carrying a large balance.
Allied Tax Advisors can review your Form 1098, loan history, HELOC tracing, points, rental schedules, and itemized-deduction comparison before you file. Visit Allied Tax Advisors to request tax preparation or planning support for your mortgage-related questions.