
Deciding whether to file as Single or Head of Household isn't just a box you check on a form—it's a choice that can dramatically change your tax bill. If you're unmarried and are the primary financial support for a qualifying person in your home, the Head of Household status is designed specifically to give you a much-needed break.
Single vs. Head of Household: An Initial Comparison
When tax season rolls around, your filing status is one of the first and most important decisions you'll make. It sets the stage for everything else, dictating your standard deduction, your tax brackets, and even which tax credits you can claim. For most unmarried folks, it boils down to two options: Single or Head of Household.
"Single" is the straightforward choice for unmarried people without dependents. But "Head of Household" is a special status that offers significant tax relief to those who are shouldering more than half the cost of keeping a roof over a qualifying child or relative's head. The payoff comes from a much larger standard deduction and more generous tax brackets, both of which work together to lower what you ultimately owe the IRS.
At a Glance: Key Financial Differences
To see the difference in black and white, let’s look at the numbers for the 2024 tax year. This table really brings home how much more breathing room the Head of Household status can provide.
| Financial Metric | Single Filer | Head of Household |
|---|---|---|
| Standard Deduction | $14,600 | $21,900 |
| 10% Tax Bracket | Up to $11,600 | Up to $16,550 |
| 12% Tax Bracket | $11,601 to $47,150 | $16,551 to $59,700 |
Note: Figures are for the 2024 tax year, which you'll file in 2025. These numbers are adjusted for inflation annually.
The numbers don't lie. As a Head of Household filer, you get a $7,300 bigger standard deduction right off the bat. That’s a huge chunk of income that becomes non-taxable from the get-go.
This larger deduction means thousands of dollars of your income are shielded from tax right from the start, providing significant relief for those shouldering the costs of a home and dependents on their own.
On top of that, the tax brackets are wider. This means you can earn more money before you get bumped into a higher tax rate. For instance, a Head of Household can earn almost $5,000 more than a Single filer and still stay in that lowest 10% bracket. It’s a structure built to ensure more of your hard-earned money is taxed at a lower rate.
Of course, these benefits aren't handed out freely. To claim this valuable status, you have to meet some strict IRS criteria. Let's dive into exactly what it takes to qualify.
Meeting the Head of Household Eligibility Tests
So, you think you might qualify for Head of Household? It’s a fantastic filing status, but the IRS has some very specific hoops you need to jump through. It's not as simple as just being single and having a child. You must pass three distinct tests, and there's no room for error. If you fail even one, you'll have to file as Single.
Let's walk through what it really takes. This chart gives you a quick visual of the first steps in the process.
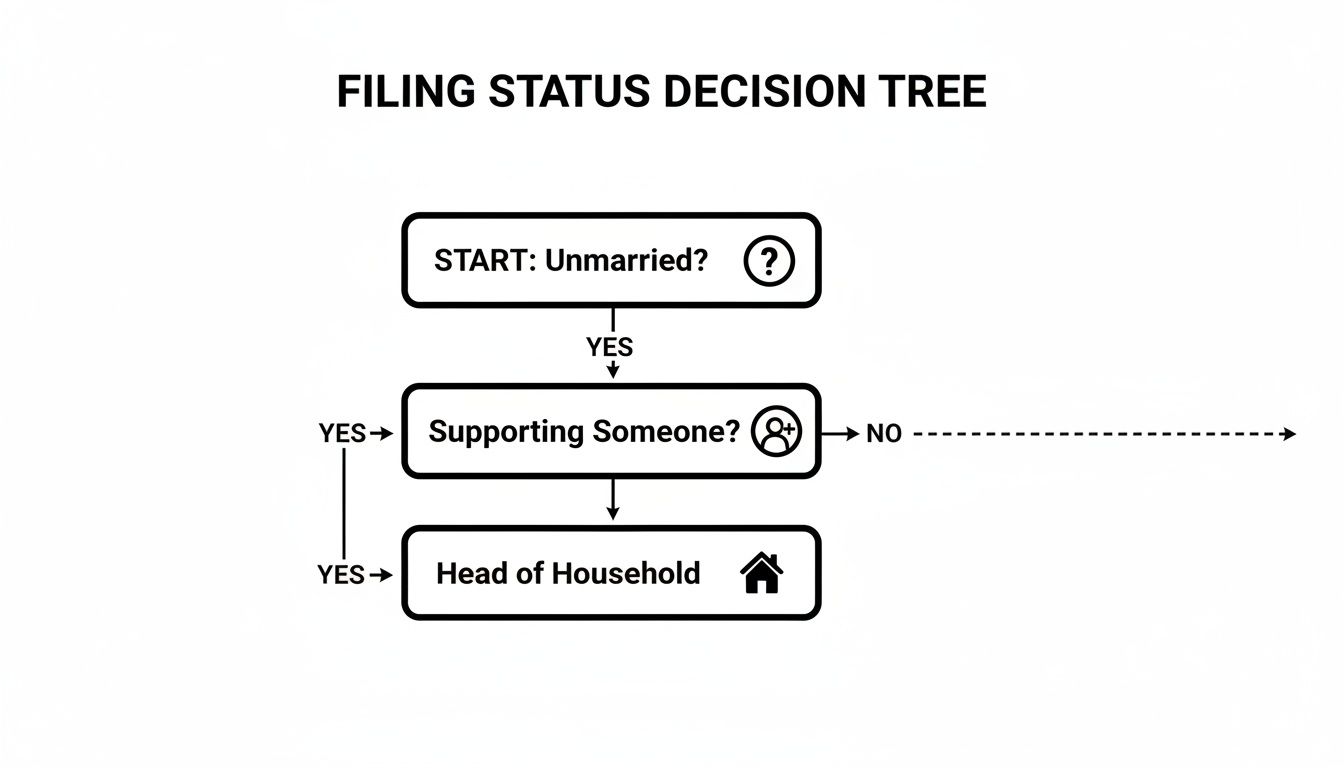
As you can see, being unmarried and supporting someone are the first two big questions. But the official rules get a lot more detailed from there.
Test 1: The Unmarried Requirement
First things first: you have to be unmarried on December 31, the last day of the tax year. For anyone who is single, divorced, or legally separated through a court decree, this part is pretty straightforward. Your status at the very end of the year is what matters to the IRS.
But what if you're married but living apart? The IRS has a special rule for this situation. You can be "considered unmarried" for tax purposes if you meet every single one of these conditions:
- You and your spouse file separate tax returns.
- Your spouse didn't live in your home for the last six months of the tax year.
- Your home was the primary residence for your child, stepchild, or foster child for over half the year.
- You paid more than half the cost of maintaining your home for the year.
This is a critical provision for separated parents who are financially on their own but haven't finalized a divorce.
Test 2: The Qualifying Person Test
This is where a lot of people get tripped up. You need to have a "qualifying person" who lived with you for more than half the year. Temporary absences for things like school or vacation don't count against you.
But a "qualifying person" isn't just any relative you're helping out. They must fall into one of two specific categories:
-
A Qualifying Child: This is usually your son, daughter, stepchild, foster child, sibling, or a descendant like a grandchild. To qualify, they must be under age 19 (or under 24 if they're a full-time student), or any age if they are permanently and totally disabled. A key detail is that they cannot have provided more than half of their own support.
-
A Qualifying Relative: This could be a parent, grandparent, or certain other relatives who aren't your qualifying child. For them to count, you must provide more than half of their total support for the year, and their gross income has to be less than the annual exemption amount.
There's a really important exception for dependent parents. If you financially support your parent and can claim them as a dependent, they don't actually have to live with you. You can still qualify for Head of Household as long as you pay more than half the cost of keeping up their main home for the entire year.
This distinction is huge. For example, a live-in partner you support won't make you eligible for Head of Household unless they also happen to meet the strict IRS definition of a qualifying relative.
Test 3: The Cost of Keeping Up a Home Test
The final piece of the puzzle is proving you're the one footing the bills. You must have paid more than half the cost of keeping up a home for the year. This test solidifies your role as the primary provider for the household.
The IRS is specific about what counts. These are the direct costs of running the home:
- Rent or mortgage interest
- Property taxes and homeowner's insurance
- Utilities (gas, electricity, water, etc.)
- Repairs and general maintenance
- Groceries and food eaten in the home
What doesn't count are personal expenses like clothing, medical care, education, or transportation. To pass this test, you have to total up all qualifying household costs for the year and show that you paid more than 50% of that total.
This is where meticulous records become your best friend. Having a clear grasp of your Adjusted Gross Income helps put these expenses in context, but if the IRS ever asks, you'll need proof of payment.
How Filing Status Impacts Your Tax Bill: Brackets and Deductions
Choosing between filing as Single or Head of Household isn't just a box to check on your tax form; it has a real, direct impact on your bottom line. The two biggest financial perks of qualifying as Head of Household are a much larger standard deduction and more forgiving tax brackets. When you combine these two advantages, the tax savings can be substantial.
Think of the standard deduction as an upfront reduction of your taxable income. It’s a set dollar amount that the IRS lets you subtract from your adjusted gross income (AGI) right off the bat. For those who qualify as Head of Household, this initial tax shield is significantly larger than for Single filers, giving you a powerful head start before tax rates even enter the picture.
The Power of a Larger Standard Deduction
For the 2024 tax year, if you file as Single, your standard deduction is $14,600. But if you meet the criteria for Head of Household, that deduction jumps to $21,900.
That’s a $7,300 difference. It means you get to immediately protect an extra $7,300 of your hard-earned money from being taxed, just by having the correct filing status. This initial drop in taxable income is a huge deal—it can even be enough to keep you in a lower tax bracket, saving you even more.
Of course, you always have the option to itemize if your deductible expenses are greater. You can learn more about making that call by reading our guide on the standard deduction vs itemized deductions.
How Wider Tax Brackets Save You Money
The second major advantage comes from the tax brackets themselves. The U.S. has a progressive tax system, where different chunks of your income are taxed at different rates. The tax brackets for Head of Household filers are wider, meaning more of your income gets taxed at the lower rates.
This is where the savings really add up, especially for people with moderate incomes. Let’s look at the 2025 tax year brackets:
- A Head of Household filer pays 10% on income up to $17,000, and the 12% bracket goes all the way up to $64,850.
- A Single filer, however, pays 10% only up to $11,925, and their 12% bracket ends at $48,475.
This structure allows $16,375 more of your income to be taxed at the lower 12% rate instead of being pushed into the next bracket. For anyone earning between $50,000 and $80,000, this can slash your effective tax rate.
The real power of the Head of Household status is this one-two punch: the bigger deduction shrinks your taxable income, and then the wider brackets tax that smaller amount more favorably. It’s a systematic way to lower your tax liability.
To see how these differences play out with your specific numbers, using a quality financial planning software can be incredibly helpful. These tools let you run different scenarios to visualize the outcome of each filing status.
A Practical Tax Savings Calculation
Let's put this into practice with an example. Meet Alex, who earns $70,000 a year and is trying to figure out the best way to file.
Scenario 1: Alex Files as Single
- Gross Income: $70,000
- Standard Deduction: -$14,600
- Taxable Income: $55,400
Scenario 2: Alex Files as Head of Household
- Gross Income: $70,000
- Standard Deduction: -$21,900
- Taxable Income: $48,100
Simply by qualifying for Head of Household, Alex’s taxable income is instantly $7,300 lower. That difference alone creates significant savings once the tax rates are applied, showing just how much money is on the line when choosing your filing status.
Seeing Head of Household in Action: Real-World Scenarios
Tax rules can feel a bit abstract until you see them applied to real-life situations. Let's move past the technical definitions and walk through a few common scenarios. This is often where the lightbulb goes on, helping you connect the dots between the IRS requirements and your own family's circumstances.
These examples will show you exactly how the eligibility tests play out and what the financial difference can really look like.
Scenario 1: The Recently Divorced Parent
Meet Sarah. She’s a graphic designer who finalized her divorce in May. Her 8-year-old son, Leo, lives with her full-time, except for weekend visits with his dad, easily spending more than half the year in her home. Sarah earns $65,000 and pays all the bills for their apartment—rent, utilities, groceries, you name it.
Let's run through the Head of Household checklist for her:
- Unmarried? Yes. Since her divorce was final before December 31st, the IRS considers her unmarried for the entire tax year. (Check)
- Qualifying Person? Absolutely. Leo is her son, well under the age of 19, and lived with her for more than six months. (Check)
- Paying for the Home? Yes. Sarah pays for well over half the cost of keeping a roof over their heads. (Check)
Sarah easily qualifies. By filing as Head of Household, she gets a $21,900 standard deduction. If she filed as Single, it would only be $14,600. That’s an instant $7,300 reduction in her taxable income, a significant saving that puts real money back in her pocket.
Scenario 2: Supporting an Elderly Parent
Now, let's look at David. He's an unmarried software developer living on his own. His 72-year-old mother, Mary, lives in her own apartment across town. Mary’s only income is her Social Security, which comes to $9,000 a year. David helps her make ends meet by paying her rent, utilities, and medical co-pays, covering the majority of her living expenses.
A lot of people think a qualifying relative has to live with you, but that’s not always true. For a dependent parent, the rules are different. As long as you provide more than half of their financial support and pay to maintain their home, they can qualify you for Head of Household status.
Here’s how David’s situation breaks down:
- Unmarried? Yes, David is unmarried. (Check)
- Qualifying Person? Yes. Mary is his mother. Since her gross income is low enough and David provides more than half her support, she counts as his qualifying relative. (Check)
- Paying for the Home? Yes, David pays over 50% of the costs to maintain his mother's home. (Check)
David is a perfect example of how this filing status extends beyond just having children at home. By taking financial responsibility for his aging mother—even from a distance—he unlocks the same tax benefits as Sarah, which simply wouldn’t be possible if he filed as Single.
Scenario 3: The "Considered Unmarried" Spouse
Finally, let's untangle a more complex case. Maria is still legally married, but she and her husband separated back in April. He lives in another city, and they haven’t filed for divorce yet. Maria lives with their 10-year-old daughter, Sofia, and has paid for everything related to the household since her husband moved out.
This is where the special "considered unmarried" rule comes into play. It’s designed for situations just like this.
For Maria to file as Head of Household, she has to meet four specific conditions:
- She must file her own separate tax return.
- Her husband cannot have lived in the home at all during the last six months of the year (from July 1st to December 31st).
- Her home must be the main home for her child, Sofia, for more than half the year.
- She must have paid more than half the cost of keeping up the home for the year.
Maria checks all four boxes. The IRS allows her to be considered unmarried for tax purposes. Because she also has a qualifying child and shouldered the financial burden of the household, she can file as Head of Household. This rule provides a critical lifeline, preventing people in her situation from being stuck with the far less advantageous Married Filing Separately status.
Common Filing Mistakes and How to Avoid Them
Filing as Head of Household can be a fantastic way to lower your tax bill, but the rules are strict and often trip people up. An incorrect claim is a huge red flag for the IRS. It can easily trigger an audit, leaving you with a bill for back taxes, penalties, and interest. Knowing the common pitfalls is the best way to file correctly and with confidence.
Many taxpayers get stuck when trying to decide whether to file single or head of household, usually because the eligibility tests get tricky. Steering clear of these frequent errors not only keeps you compliant but also makes sure you get the tax benefits you've rightfully earned.
Misunderstanding the Qualifying Person Rule
One of the most common blunders is claiming someone who simply doesn't meet the IRS definition of a "qualifying person." It’s easy to assume that anyone you live with and support financially counts, but that’s not the case.
For example, a live-in partner usually won't be your qualifying person unless they pass a specific, multi-part test to be considered a "qualifying relative." This involves strict income limits and relationship rules. In the same way, a child who earns enough to pay for more than half of their own expenses, maybe from a part-time job, won't make you eligible for this status.
How to Avoid This Mistake:
- Double-check the relationship tests: Your qualifying person must be a child, stepchild, sibling, parent, grandparent, or another relative on a specific list. A roommate or partner almost never qualifies.
- Verify income and support limits: For a qualifying relative, their gross income has to be below the annual threshold, and you must provide over half of their total support for the year.
Errors in Shared Custody Situations
This is a big one for divorced or separated parents. The rule is crystal clear: only one parent can claim Head of Household status using the same child. That right belongs to the custodial parent—the one the child lived with for more nights during the year.
Even if the non-custodial parent provides a large chunk of financial support, they can't claim Head of Household if the child didn't physically live with them for more than half the year. If both parents try to claim it, you can bet the IRS will send notices to both of you.
In the eyes of the IRS, residency is the deciding factor. The parent who has physical custody for more than 183 nights of the year is generally the only one eligible to claim the child for Head of Household purposes, regardless of financial contributions.
To keep things smooth, separated parents really need to communicate or have a solid custody agreement that spells out who gets to claim the child for tax purposes.
Miscalculating the Cost of Keeping Up a Home
The rule says you must pay more than 50% of the cost of keeping up the home, and this is another spot where mistakes are common. People often fail to track these expenses properly or, worse, include costs that don't even qualify.
The IRS has a very specific list of what counts. These are the expenses tied directly to running the household:
- Rent or mortgage interest
- Property taxes and insurance
- Utilities (gas, electric, water)
- Repairs and maintenance
- Food eaten in the home
Things like clothing, education, medical bills, or car expenses are personal and do not count toward this total. Your best defense here is meticulous record-keeping. Hang on to receipts and bank statements for all qualifying household expenses all year long.
The choice between single and head of household can make a huge difference to your bottom line. For 2025, the standard deduction for head of household is projected to be $23,625, a full 50% more than the $15,750 for single filers. That difference alone can save you thousands.
Using the best tax software can also be a big help in preventing these kinds of filing mistakes, as it guides you through the process and helps reduce the chance of errors.
Navigating the choice between Single and Head of Household can feel straightforward at first glance, but life isn't always that simple. While guides like this one can lay out the rules, applying them to your specific circumstances is where things can get tricky.
Making the wrong call isn't just about missing out on tax savings—it could also put you on the IRS's radar. That’s why knowing when to call in a professional is so important. It’s not about admitting defeat; it’s about making a smart, strategic move to protect your finances.
When Life Gets Complicated
Some situations are practically designed to make tax rules feel ambiguous. If you're nodding along to any of the scenarios below, it’s a strong sign that an expert’s perspective would be a wise investment.
-
Complex Custody Arrangements: A 50/50 split or an unconventional schedule can muddy the waters on who is truly the "custodial parent" in the eyes of the IRS. It's often not as simple as counting the days.
-
Blended Families: When you have stepchildren or other relatives living in your home, untangling the support and residency tests to determine who counts as a qualifying dependent requires a sharp eye for detail.
-
Supporting Multiple Relatives: Are you helping out more than one family member? A tax pro can run the numbers to see if any of them meet the strict criteria to be your "qualifying relative."
A tax professional does more than just fill out forms; they apply years of experience to your unique circumstances, ensuring you meet every requirement to legally claim the most beneficial filing status available.
Sometimes, the value of an expert comes after the fact. If you look back and realize you filed as Single when you actually qualified for Head of Household, an advisor can help you amend those past returns to claim the refund you’re owed. They can also look ahead, helping you with tax planning to keep you on the right track for years to come.
Instead of guessing and hoping for the best, get personalized advice to move forward with confidence. For guidance on picking the right person, our article on how to find a tax preparer near you is a great place to start.
Frequently Asked Questions
Even with a comprehensive guide, applying tax rules to your own life can bring up some very specific questions. Let's tackle some of the most common issues people run into when deciding between filing as Single or Head of Household. Getting these details right is the key to filing with confidence.
Can My Child's Other Parent and I Both Claim Head of Household?
This is a classic point of confusion, and the answer is a firm no. Only one person can claim Head of Household status using the same child as a qualifying person.
The right to claim this status almost always goes to the custodial parent—that’s the parent the child lived with for more nights during the year. Even if a non-custodial parent provides a huge amount of financial support, they can't file as Head of Household if the child didn't physically live with them for over half the year. If both parents try to claim it, you can bet the IRS will flag both tax returns for a closer look.
What Expenses Count Towards "Keeping Up a Home"?
The IRS has a pretty clear definition of what falls under the "cost of keeping up a home." The core rule is that you must have paid for more than 50% of these combined costs for the whole year.
So, what counts?
- Rent or mortgage interest
- Property taxes and homeowner's insurance
- Utilities (gas, electricity, water, etc.)
- Home repairs
- Groceries and food eaten in the home
Things like clothing, school tuition, car payments, or medical bills don't make the cut for this specific test. Keeping good records of your household expenses is your best friend if the IRS ever has questions about your filing status.
I Should Have Filed as Head of Household Last Year. Can I Fix It?
Absolutely. If you look back and realize you filed as Single when you actually met all the requirements for Head of Household, you can correct it. The tool for this job is Form 1040-X, Amended U.S. Individual Income Tax Return.
You generally have up to three years from the date you filed your original return (or two years from the date you paid the tax, whichever is later) to file an amendment. This is your window to claim any additional refund you're owed.
It’s more common than you think, and a successful amendment can lead to a substantial refund. Because amending a return has a few moving parts, it's often a smart move to get a professional to walk you through it.
Wrestling with these rules can be tricky, but you don't have to do it alone. The experts at Allied Tax Advisors offer one-on-one consultations to confirm your eligibility, help amend prior-year returns, and make sure you're claiming the filing status that benefits you most. Visit us at https://alliedtax.com to get the peace of mind you deserve.