
You open your tax return expecting a manageable balance, or maybe even a refund, and instead you see an amount you can't comfortably pay. Then the questions start. Do I wait? Do I call the IRS? Will they empty my bank account? Did I just create a much bigger problem?
If that's where you are, take a breath. Owing the IRS is serious, but it isn't unusual, and it doesn't automatically mean aggressive collection is around the corner if you respond the right way. In practice, paying taxes in installments is often the cleanest path for taxpayers who can file on time, pay something now, and spread the rest over a realistic timeline.
What matters most is choosing the right option for your situation, not grabbing the first plan name you see on an IRS page. A W-2 employee with a one-time stock sale has a different decision to make than a landlord with uneven rental cash flow or an S corporation owner juggling payroll deposits and income taxes.
Table of Contents
- Can't Pay Your Tax Bill? You Have Options
- Are You Eligible for an IRS Payment Plan?
- Choosing Your IRS Installment Agreement
- The Application Process for an Installment Plan
- Alternatives and Special Scenarios
- FAQ on Managing Your Tax Installment Plan
Can't Pay Your Tax Bill? You Have Options
A lot of taxpayers freeze after they open an IRS notice. They assume that if they can't pay in full, they've already failed. That mindset causes more damage than the tax bill itself, because silence is what turns a manageable problem into a collection problem.
Many individuals I speak with aren't trying to avoid taxes. They filed, they learned what they owed, and they don't have the cash to write one large check. The IRS has systems for exactly that situation. On the federal side, the IRS reports that the projected gross tax gap for tax year 2022 was $696 billion, and the underpayment component alone was $94 billion, which is the category most closely tied to taxpayers who filed on time but didn't pay on time, according to the IRS tax gap data.
That matters for one reason. It shows this is a routine compliance issue, not some rare exception. Paying taxes in installments is an official resolution channel, not a workaround.
What usually works first
The strongest first move is simple:
- File on time: Even if you can't pay in full, filing keeps the problem from getting worse in ways that are avoidable.
- Pay what you can: Any amount you pay now reduces the balance that will continue to generate interest and penalties.
- Choose a structured plan: A formal arrangement is usually better than sending inconsistent payments with no agreement in place.
Practical rule: Don't wait until the IRS chooses the pace for you. It's better to propose a payment structure while your options are wider.
If you're sorting through the basics, Allied Tax Advisors has a useful overview of IRS payment plan options that can help you match the debt to the right path. The key is to treat the bill as a cash-flow problem first, then decide whether an installment agreement is enough or whether you need a different form of relief.
Are You Eligible for an IRS Payment Plan?
Before you think about plan length or monthly amount, check whether you qualify at all. Taxpayers often jump straight to payment terms and overlook the two issues that stop many applications. missing returns and an ineligible balance structure.
For most individual long-term installment agreements, the IRS uses an operational benchmark of $50,000 or less in assessed tax, penalties, and interest, and the taxpayer must have filed all required returns, as described on the IRS payment plans and installment agreements page. The same IRS guidance says the balance must be fully paid by the Collection Statute Expiration Date, which is generally 10 years from assessment.
The non-negotiables
If you're evaluating whether paying taxes in installments is available to you, start with this checklist:
- All required returns filed: If prior-year returns are missing, fix that first. The IRS generally won't approve a standard plan while you still have filing gaps.
- Balance within the common benchmark: For many individual long-term plans, the usual threshold is $50,000 or less including tax, penalties, and interest.
- A full-pay path exists: The IRS expects the balance to be resolved before the collection statute expires.
- You can propose payment details: For eligible long-term requests, the IRS requires you to choose a monthly payment amount and a day of the month for payment or withdrawal.
Why filing status matters more than people think
Some taxpayers owe a manageable amount but still can't move forward because they never filed an older return. Others filed everything, but the current balance has grown enough from penalties and interest that it no longer fits the easier approval lane.
That distinction matters. A taxpayer with complete filings and a clean record often has a more straightforward process than someone with a lower balance but unresolved filing years.
Get current before you negotiate. The IRS tends to discuss collection options more productively when the filing side is already cleaned up.
A quick self-test
You may be a strong candidate for a standard installment agreement if these statements are true:
- You've filed every required federal return.
- You know your current assessed balance, not just your original tax due.
- You can support a monthly amount you won't miss.
- You understand the plan won't stop interest and penalties from accruing.
If one or more of those isn't true, don't assume you're out of options. It may just mean the standard online route isn't the right starting point. In those cases, the strategy often shifts from simple enrollment to financial disclosure, negotiation, or another resolution method.
Choosing Your IRS Installment Agreement
Once eligibility is clear, the main question becomes tactical. Which arrangement fits your cash flow without setting you up to default later? The wrong plan isn't always the one with the highest monthly payment. Often it's the one that looks good on paper but doesn't survive a tight month.
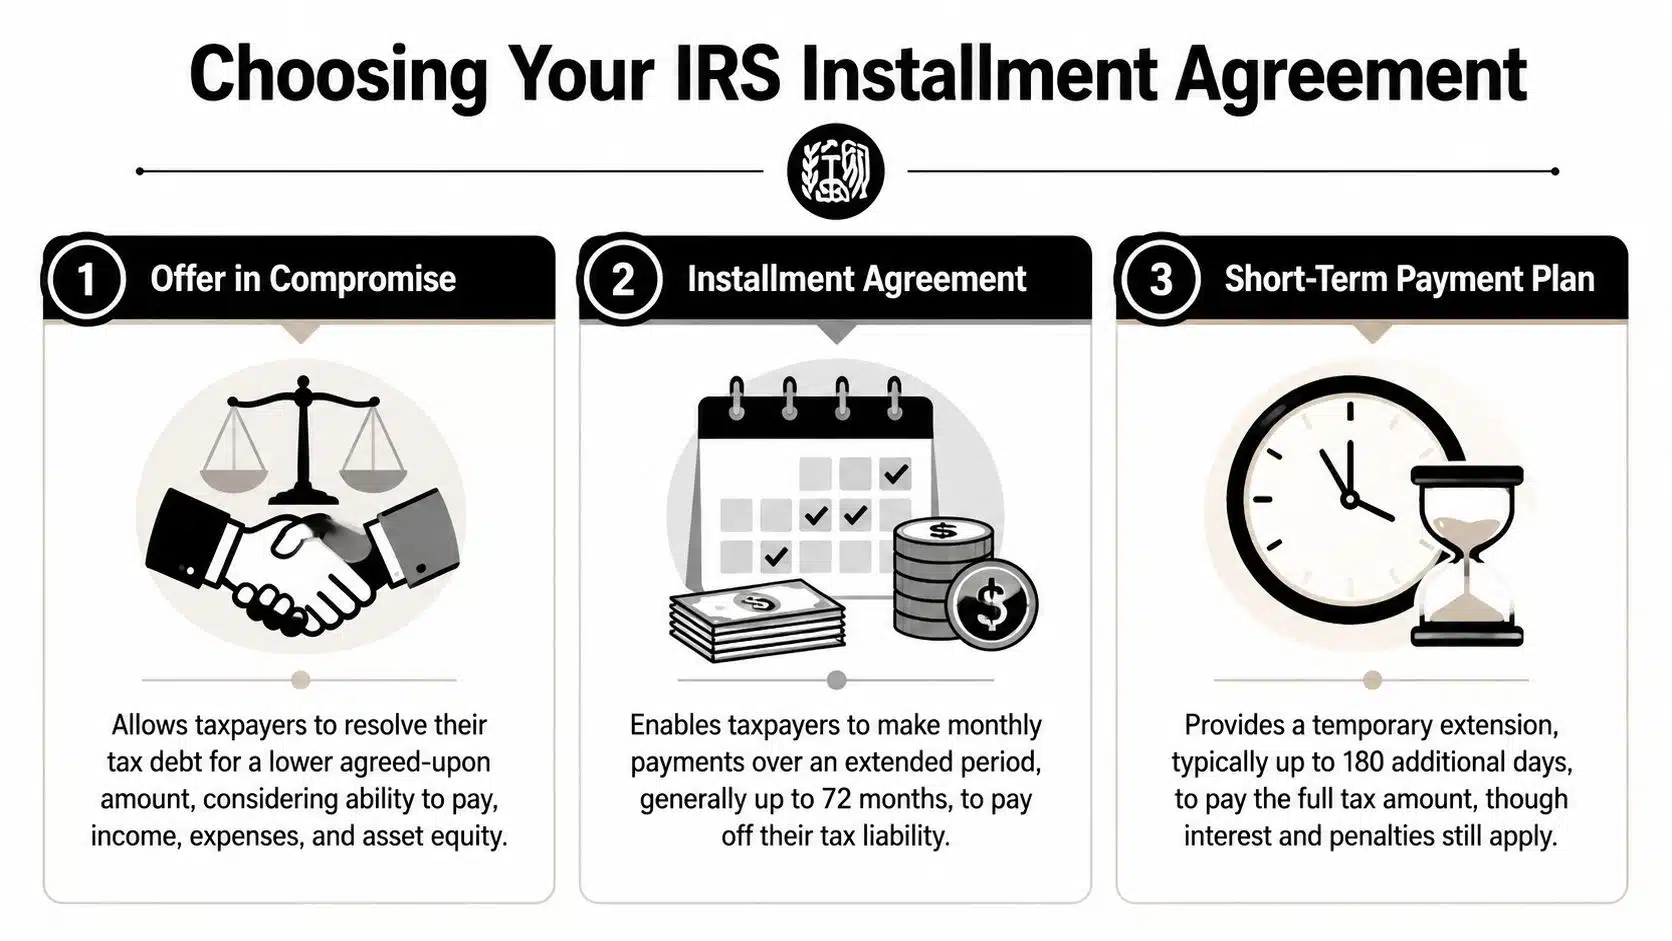
IRS-related guidance cited in practice materials says over 70% of taxpayers using these plans rely on one of the three common long-term structures, and those plans can stretch up to six years in many cases. The same guidance notes that simplified agreements are generally available for taxpayers owing $50,000 or less, as explained in this installment plan guidance summary.
Short-term relief versus monthly payments
Some taxpayers don't need a full installment agreement. They need time.
A short-term payment plan is usually the better fit when you expect to pay the full amount soon from a bonus, receivable, property closing, or another near-term source of cash. If the money is realistically coming, avoid locking yourself into a monthly structure you don't need.
A long-term installment agreement makes more sense when the balance has to be spread over time because the household or business budget can't absorb a lump-sum payment. That's often the case when discussing paying taxes in installments.
IRS payment plan options at a glance
| Plan Type | Total Debt Limit | Payment Term | Setup Fee (Online) | Best For |
|---|---|---|---|---|
| Short-Term Payment Plan | Varies by IRS eligibility rules | Up to 180 days | Varies by IRS method and circumstances | Taxpayers who can pay in full soon but need extra time |
| Guaranteed Installment Agreement | Use IRS eligibility rules and account history | Common long-term structure | Varies by IRS method and circumstances | Smaller individual balances with predictable income |
| Streamlined Installment Agreement | Generally available for balances of $50,000 or less | Commonly structured over monthly payments, often up to six years in practice guidance | Varies by IRS method and circumstances | Individuals who qualify for a simpler approval path |
| Full-Pay Non-Streamlined Agreement | Above streamlined limits or more complex facts | Must still fully pay within the collection window | Varies by IRS method and circumstances | Taxpayers who need a formal plan but don't fit the streamlined lane |
How to choose the right lane
A useful way to decide is to ignore the label at first and focus on your payment reality.
If your income is stable and the tax debt came from a one-time event, a standard monthly plan is often enough. This is common with stock sales, capital gains, crypto transactions, retirement withdrawals, or a surprise balance after self-employment income wasn't covered by estimates.
If your income swings month to month, be careful about volunteering a payment amount based on your best month. Landlords, contractors, and business owners do this all the time. Then a vacancy, repair, or slow quarter hits, and the agreement starts to wobble.
The IRS cares whether the payment is consistent. Your budget should care whether it's survivable.
A few practical decision rules help:
- Choose short-term only if the payoff source is real: Pending isn't the same as guaranteed.
- Don't confuse eligibility with affordability: Qualifying for a simplified payment plan doesn't mean the proposed payment fits your life.
- Prioritize automatic payments when cash flow is dependable: That reduces missed-payment risk.
- Leave room for current-year taxes: A payment plan fails quickly if you solve old taxes but fall behind on new ones.
For taxpayers who need broader tax resolution help, one option is working with a firm such as Allied Tax Advisors, which handles IRS and state payment plan matters along with related notice and collection issues. The value isn't the form itself. It's matching the plan to the facts before a preventable default happens.
The Application Process for an Installment Plan
The application is not difficult, but it goes more smoothly when you prepare before logging in. Most delays happen because the taxpayer starts the request without the balance details, payment date, bank information, or filing history at hand.
What to gather before you apply
Have these items ready before you begin:
- Your identifying information: Social Security number or employer identification number, depending on the account.
- A recent IRS notice or balance information: Use the latest figure you have so your request starts from the right number.
- Your banking details if you plan direct debit: This helps if you want automatic withdrawals.
- Your monthly budget view: Not a perfect spreadsheet, just a realistic sense of what you can sustain.
- Your prior return information if identity verification is needed: Tax software users often have this handy. Paper filers sometimes need to pull records first.
If any of your tax records or financial support documents are in another language, it's smart to line up accurate financial translation services before submitting anything. That can prevent confusion when the IRS or your advisor needs to review income records, foreign account documents, or entity paperwork.
How the online request usually works
For many taxpayers, the IRS online payment agreement route is the cleanest starting point. The basic flow is straightforward:
- Access your IRS online account.
- Review the balance shown for the tax period involved.
- Select the payment arrangement you qualify for.
- Propose a monthly amount and choose a payment date.
- Enter bank information if you're using direct debit.
- Submit and save the confirmation.
The most common mistake is choosing a payment date without thinking about payroll, rent, mortgage drafts, or business vendor cycles. Pick a date that works with how money moves through your account.
Keep a copy of the confirmation and every notice that follows. If the IRS later shows a gap or a pending issue, your records matter.
If you want a practical walkthrough before you apply, this guide on how to set up an IRS payment plan is useful for understanding the steps and common sticking points.
When paper or phone makes more sense
Online isn't always the right tool.
Mailing a request may be necessary when the account has unusual facts, identity issues, or unresolved notices that need to travel with the application. Phone contact can also be appropriate when the online system doesn't reflect the account accurately, when a recent filing hasn't posted yet, or when the taxpayer needs to discuss alternatives instead of a standard plan.
A final point that matters in real life. Applying is only half the job. The agreement works only if you can stay current afterward. That means filing future returns on time and paying new taxes as they come due. If you're solving an old balance while underwithholding this year, fix the current-year problem at the same time.
Alternatives and Special Scenarios
Not every tax debt should go into a standard installment agreement. Sometimes the monthly payment needed to full-pay the balance is too high. Sometimes the taxpayer's finances are too unstable. Sometimes the account involves business taxes, amended returns, or a pending refund issue that changes the strategy.
When an installment plan isn't the best fit
Two alternatives come up often in practice.
An Offer in Compromise may be worth reviewing when full payment isn't realistic and the taxpayer's income, expenses, and asset picture support a reduced settlement analysis. A plain-language overview of what an Offer in Compromise is can help you understand where that fits.
Currently Not Collectible status can be appropriate when paying anything would interfere with basic living expenses. It doesn't erase the debt, but it can pause active collection pressure while the taxpayer stabilizes.
Neither option should be treated as an easy escape hatch. They require careful financial review, and the wrong application can waste time while interest and penalties keep building.
Scenario one with a W-2 taxpayer and a surprise gain
A common San Diego case is the salaried employee who had good withholding from wages but sold stock, crypto, or an inherited asset and triggered a larger balance than expected.
In that situation, a standard installment agreement often works if the problem was a one-time event and current withholding is now corrected. The planning question isn't just, "Can you afford the monthly payment?" It's also, "Will next year's return be balanced so this doesn't repeat?"
What tends to work:
- Adjust withholding quickly: Solve the current-year issue before the next filing season.
- Use a monthly amount that fits take-home pay: Don't build the plan around hoped-for bonuses.
- Review whether an amended return is still pending: If you already filed a correction and are waiting on the result, that can affect the amount you need to finance. For taxpayers trying to track that part of the process, this guide to finding amended tax return status can be helpful.
What usually doesn't work is setting a payment amount based on temporary optimism. A payment plan should survive ordinary life, not only a perfect month.
Scenario two with a landlord and uneven rental income
Landlords often look strong on paper and tight on cash. Rent comes in, but then insurance renews, a water heater fails, a unit sits vacant, or a tenant pays late. That's why landlords need to treat IRS payment planning differently from a salaried employee.
A landlord's better move is usually to build the payment amount around conservative net cash flow, not gross rental receipts. If the tax issue came from depreciation recapture, passive loss limits, or years of uneven estimates, the repayment plan should leave room for repairs and reserves.
A practical approach is to ask:
- What does the property portfolio produce in an average month after ordinary costs?
- How much volatility do vacancies or repairs create?
- Are estimated taxes for the current year being handled now?
If the answers are uncertain, a lower but reliable payment often beats a higher payment that collapses after the first major repair.
Rental income can support an IRS plan. Rental volatility can also break one. Build around the second fact, not the first.
Scenario three with an LLC or S corporation owner
Business owners face a different risk. The tax debt may be tied to pass-through income, payroll obligations, or both. That changes the pressure because the owner has to keep the business compliant while paying down old debt.
For an LLC or S corporation owner, the first question is whether the tax problem is isolated or ongoing. If payroll deposits are still slipping, an installment plan on old balances won't solve much. The business needs current compliance first, then a debt strategy.
Strong moves for owners include:
- Separate old debt from current operations: Don't let every new tax deposit get absorbed by yesterday's problem.
- Get bookkeeping current: If the books are stale, the proposed payment amount is usually guesswork.
- Protect payroll compliance: Owners can sometimes survive income tax debt longer than payroll tax issues.
- Realistically assess entity cash flow: If owner draws are inconsistent and vendor pressure is rising, a standard plan may be the wrong tool.
Where owners get into trouble is assuming the business will "catch up next quarter." Sometimes it does. Often it doesn't. When the company can't support both current taxes and back taxes, that's the point to evaluate alternatives rather than forcing an installment agreement that won't hold.
FAQ on Managing Your Tax Installment Plan
What happens if you miss a payment
A missed payment can put the agreement at risk of default. If that happens, don't ignore the notice. Review whether the payment failed because of timing, banking changes, or a deeper cash-flow problem, then act quickly to correct it or request another solution.
Can you pay the plan off early
Yes. If your cash position improves, early payoff usually makes sense because it shortens the period during which interest and penalties continue to accrue. Keep records showing the extra payment and confirm how the IRS applied it.
Will an IRS installment agreement affect your credit
The payment plan itself isn't the same thing as a consumer loan tradeline. The larger concern is whether the IRS files a public lien or whether the tax issue disrupts a refinancing, sale, or other transaction that requires clean tax documentation.
What about state tax installment plans
State tax agencies use their own systems, forms, and collection procedures. Don't assume a federal installment agreement automatically solves a California balance or any other state issue. Treat state notices separately and respond on their own deadlines.
Should you change the plan if your income changes
Usually, yes. If income drops or rises materially, review the plan before it becomes unworkable. The worst time to revisit an installment agreement is after you've already missed payments and new tax debt has started stacking up.
If you're dealing with IRS debt and need help choosing between an installment agreement, a short-term plan, or a more strategic resolution path, Allied Tax Advisors can help you review the facts, organize the account, and decide on a realistic next step.